
Today's bond market may represent the most important shift in retirement strategy in over a decade. To understand why, we need to start with where equities have been. Over the 15 years ending in September 2026, the Vanguard S&P 500 ETF (VOO) generated an annualized return of more than 15%. For investors approaching or already in retirement, those returns may have helped create a welcome problem: their portfolios are larger and potentially more equity-heavy than they once expected.
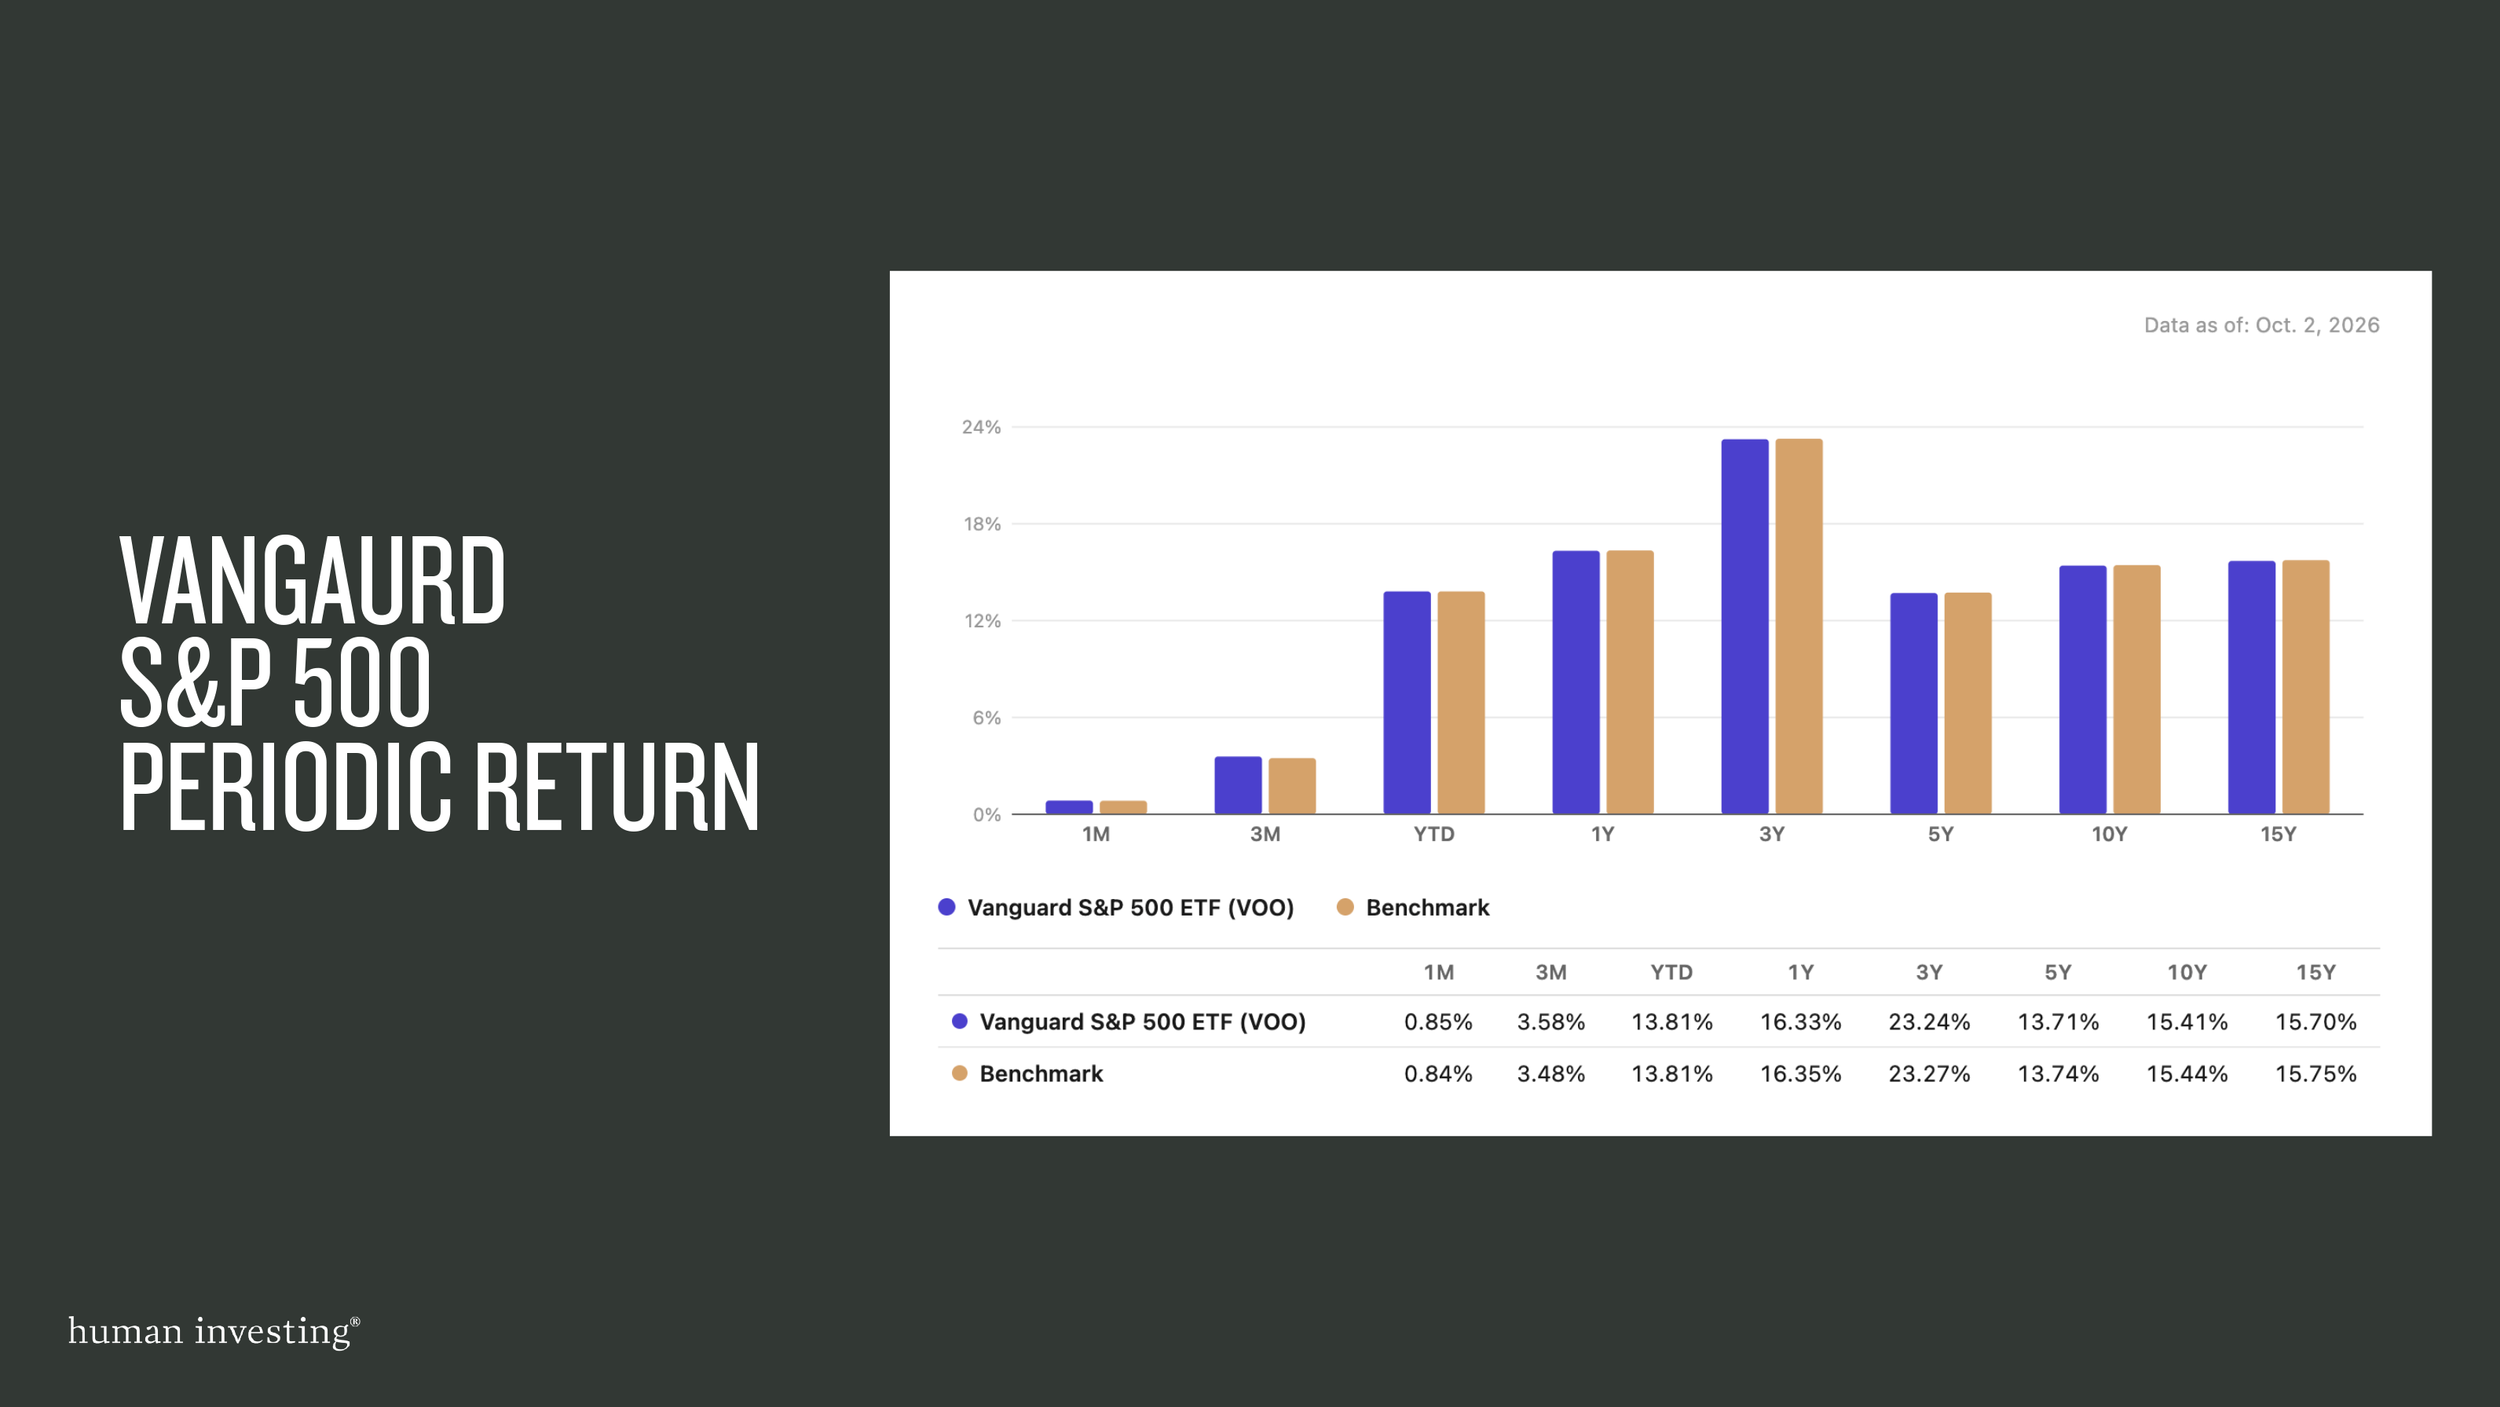
Note: The Benchmark here is the S&P 500. Data courtesy of YCharts.
The reason for an investor's portfolio being potentially over-exposed to equities based on their age could be for one of two reasons.
They intentionally selected to be more aggressive based on their comfort level with risk and economic conditions.
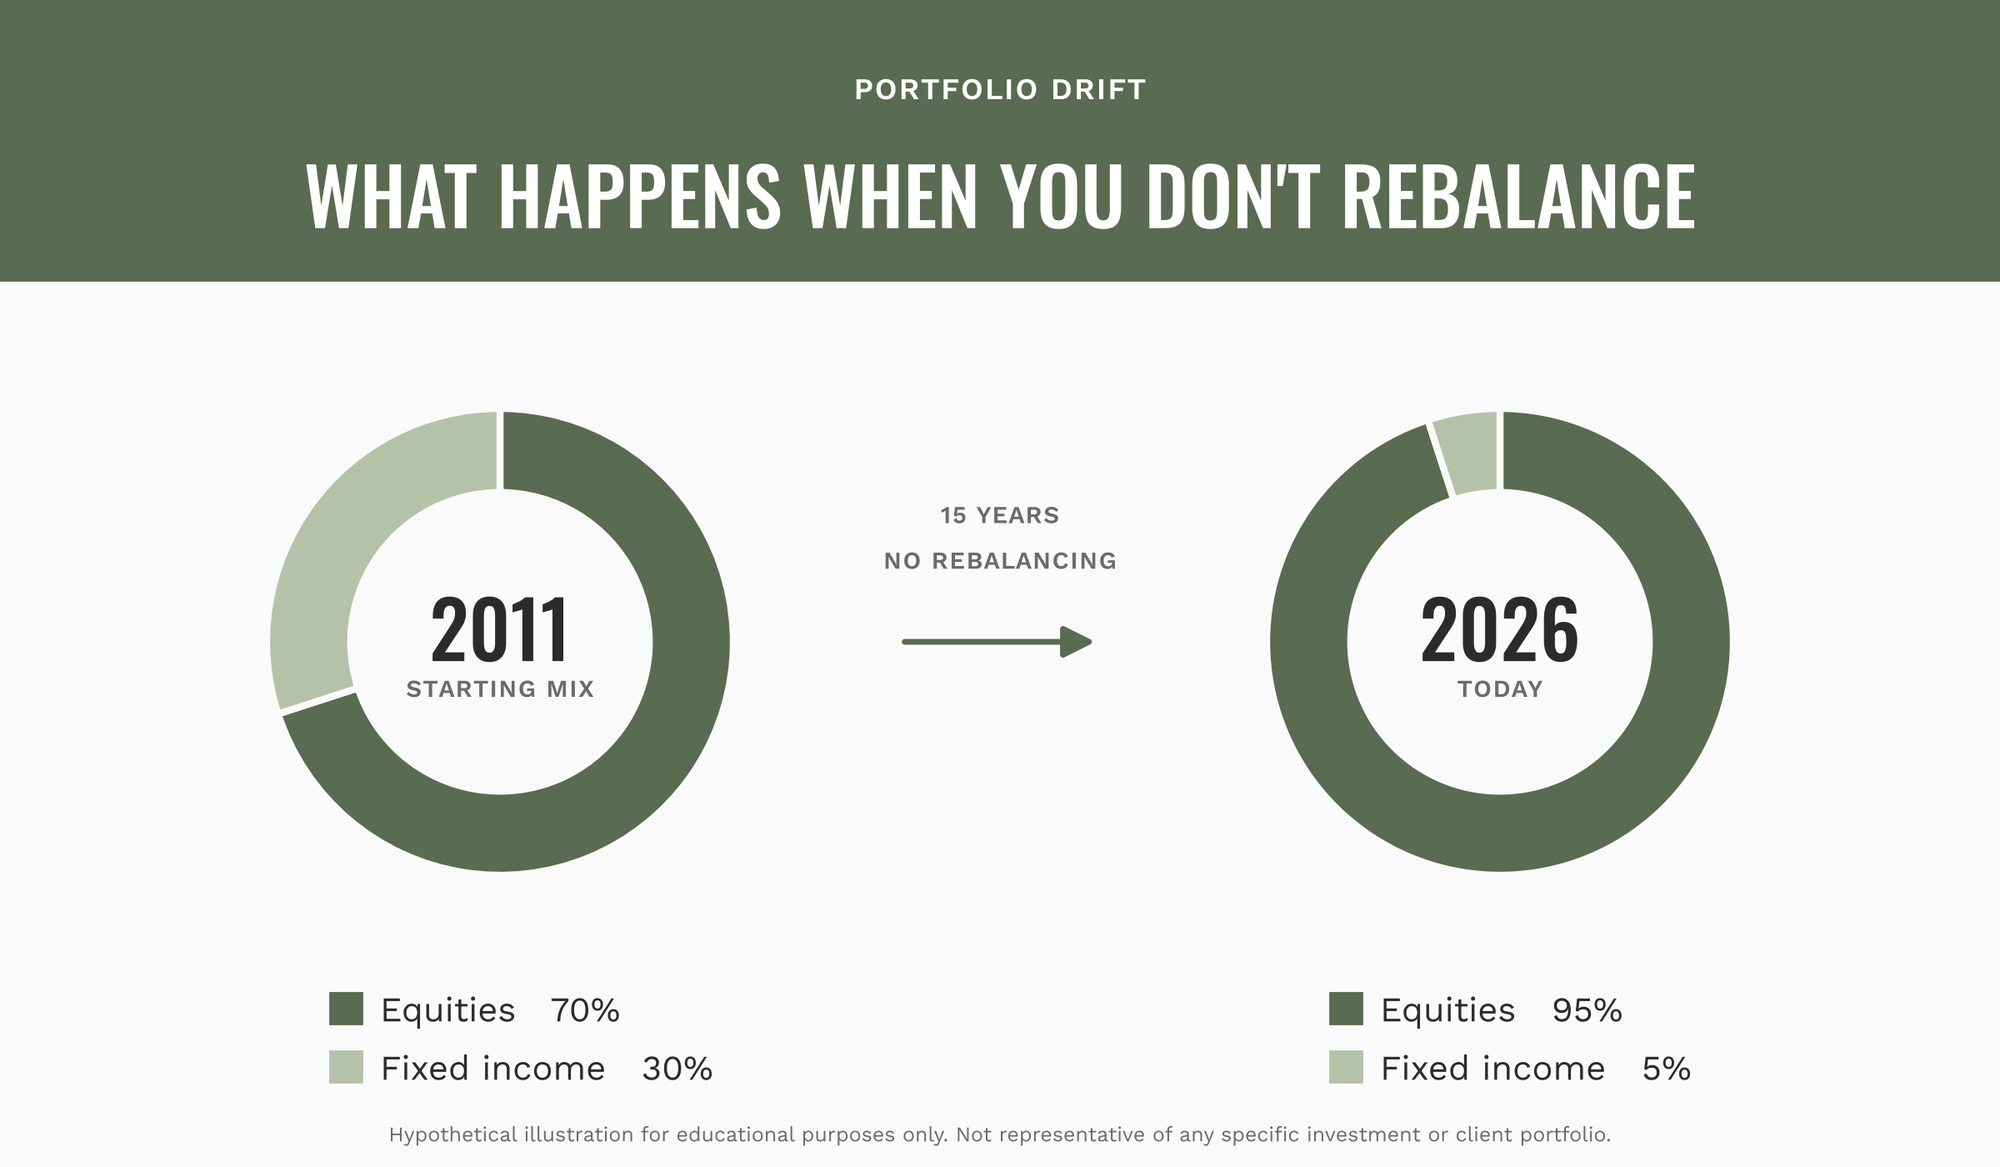
They initially invested their portfolio in a more balanced methodology and did not rebalance their portfolio as equity markets grew. Take a portfolio that was invested in 70% equities and 30% fixed income 15 years ago. That portfolio left without rebalancing is now 95% equities and 5% fixed income in 2026.
That 15% annualized return from the S&P 500 came with real volatility and its share of drawdowns. For many investors, those moments made it easy to avoid rebalancing. Whether it was COVID 19, peak tariff volatility in 2025, or more recently a steep increase in the price of oil with the closing of the Strait of Hormuz, there were plenty of reasons to hold tight.
The point being risk feels very different after you’ve been rewarded for taking it on for more than a decade.
While stocks were soaring, bonds went through a different period
For much of the 2010’s interest rates were low by historical standards. Then during the pandemic Treasury yields fell to extraordinary lows. For someone building a retirement portfolio, this presented a challenge. Imagine your financial plan required roughly a 5% rate of return to be considered “successful”. If high-quality bonds were yielding 1-2%, investors needed to find growth from somewhere else. Stocks were a great source of growth over the last 15 years, but we can never count on markets to repeat themselves.
One lesson our team applied during these years, and one we regularly enforce with clients, is that every financial plan has an implicit return hurdle. The lower the expected return from the conservative portion of a portfolio, the more work the growth portion of the portfolio has to do. Today that equation looks different.
The Bond Market Has Changed Dramatically & It’s Changing Retirement Math
For investors looking to rebalance funds away from equities or cash and into bonds, it’s important to recognize that today’s starting point for the bond market is fundamentally different than it was for much of the past 15 years. For a retiree, the important takeaway isn't why rates moved from below 1% to above 5%. It's what those higher yields mean for the role bonds can play in a retirement portfolio. Bonds can once again contribute meaningfully toward achieving your financial goals. And importantly, they can do so while playing the traditional roles we'd expect from fixed income: generating income, providing diversification and generally taking less risk than equities.
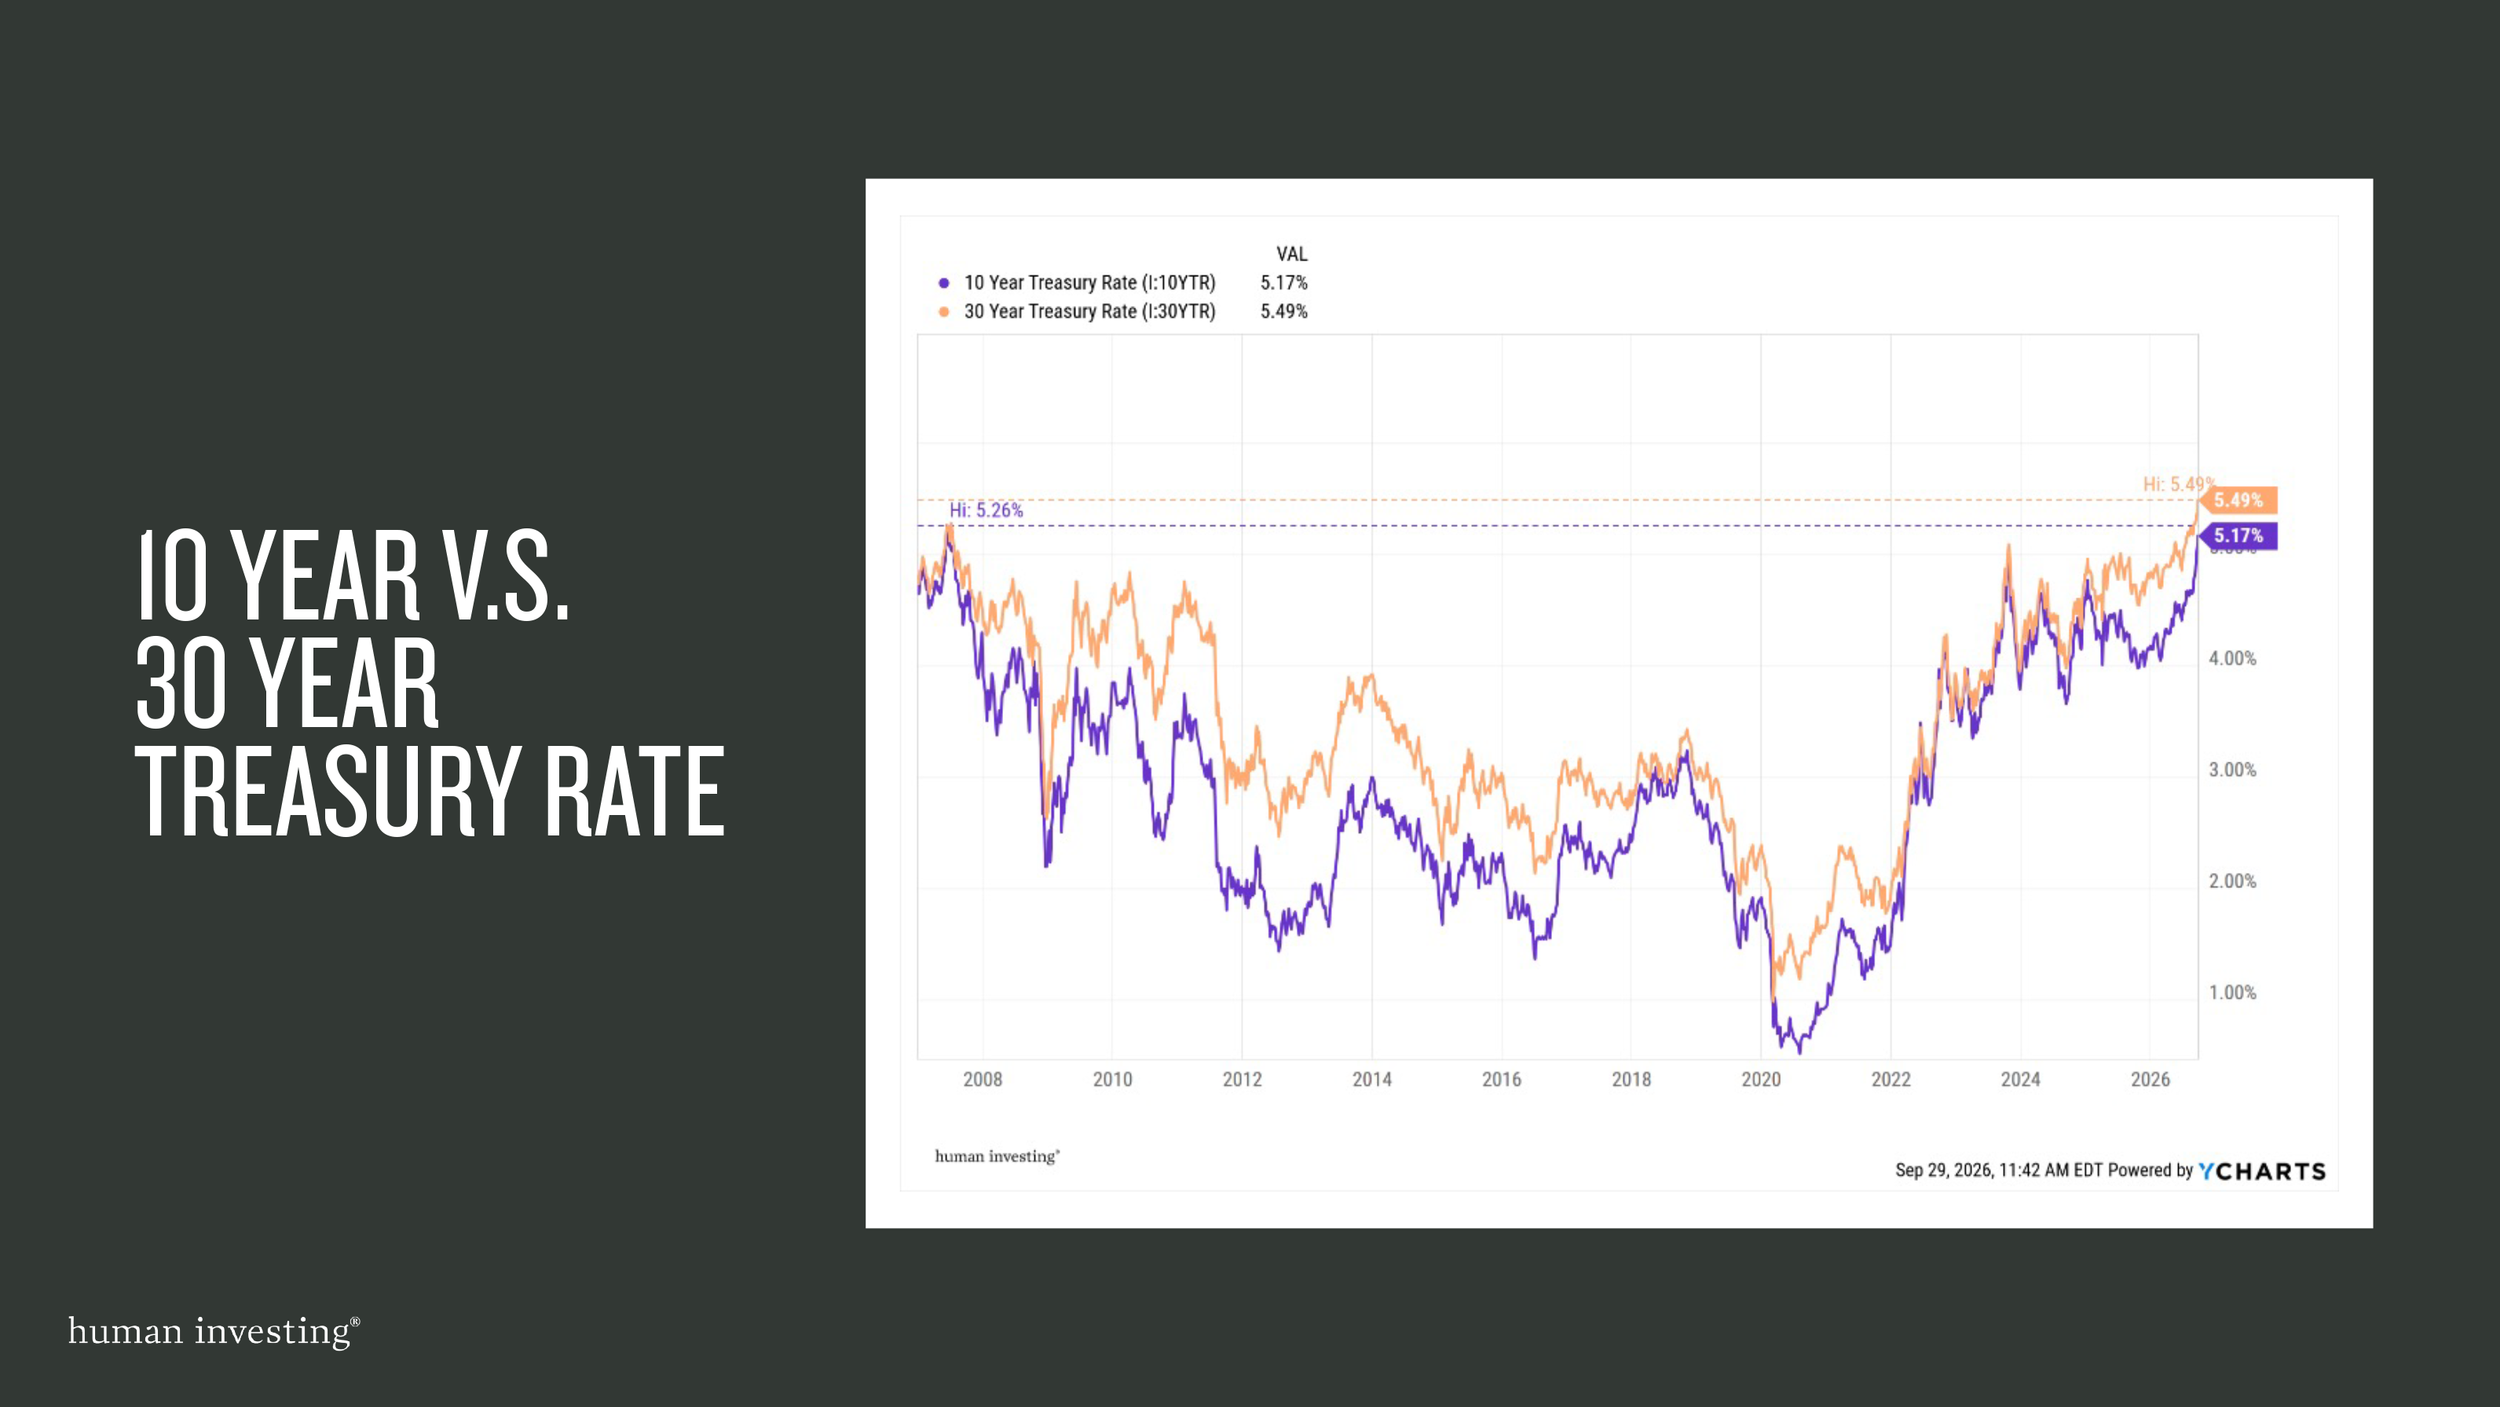
Data courtesy of YCharts.
How does this change the Math for retirees? Let’s assume that someone has completed their financial plan. After accounting for spending, social security, inflation, taxes, longevity, and other goals the plan indicates that their portfolio needs to earn between 5.25% and 5.5% over the long run for their plan to succeed. This leads to the key question:
“How much risk do I need to take to reasonably pursue the return this plan requires?”
In 2020, answering that question was difficult. With high-quality bonds offering very low yields, a portfolio targeting a moderate return generally needed to rely more heavily on equities for growth.
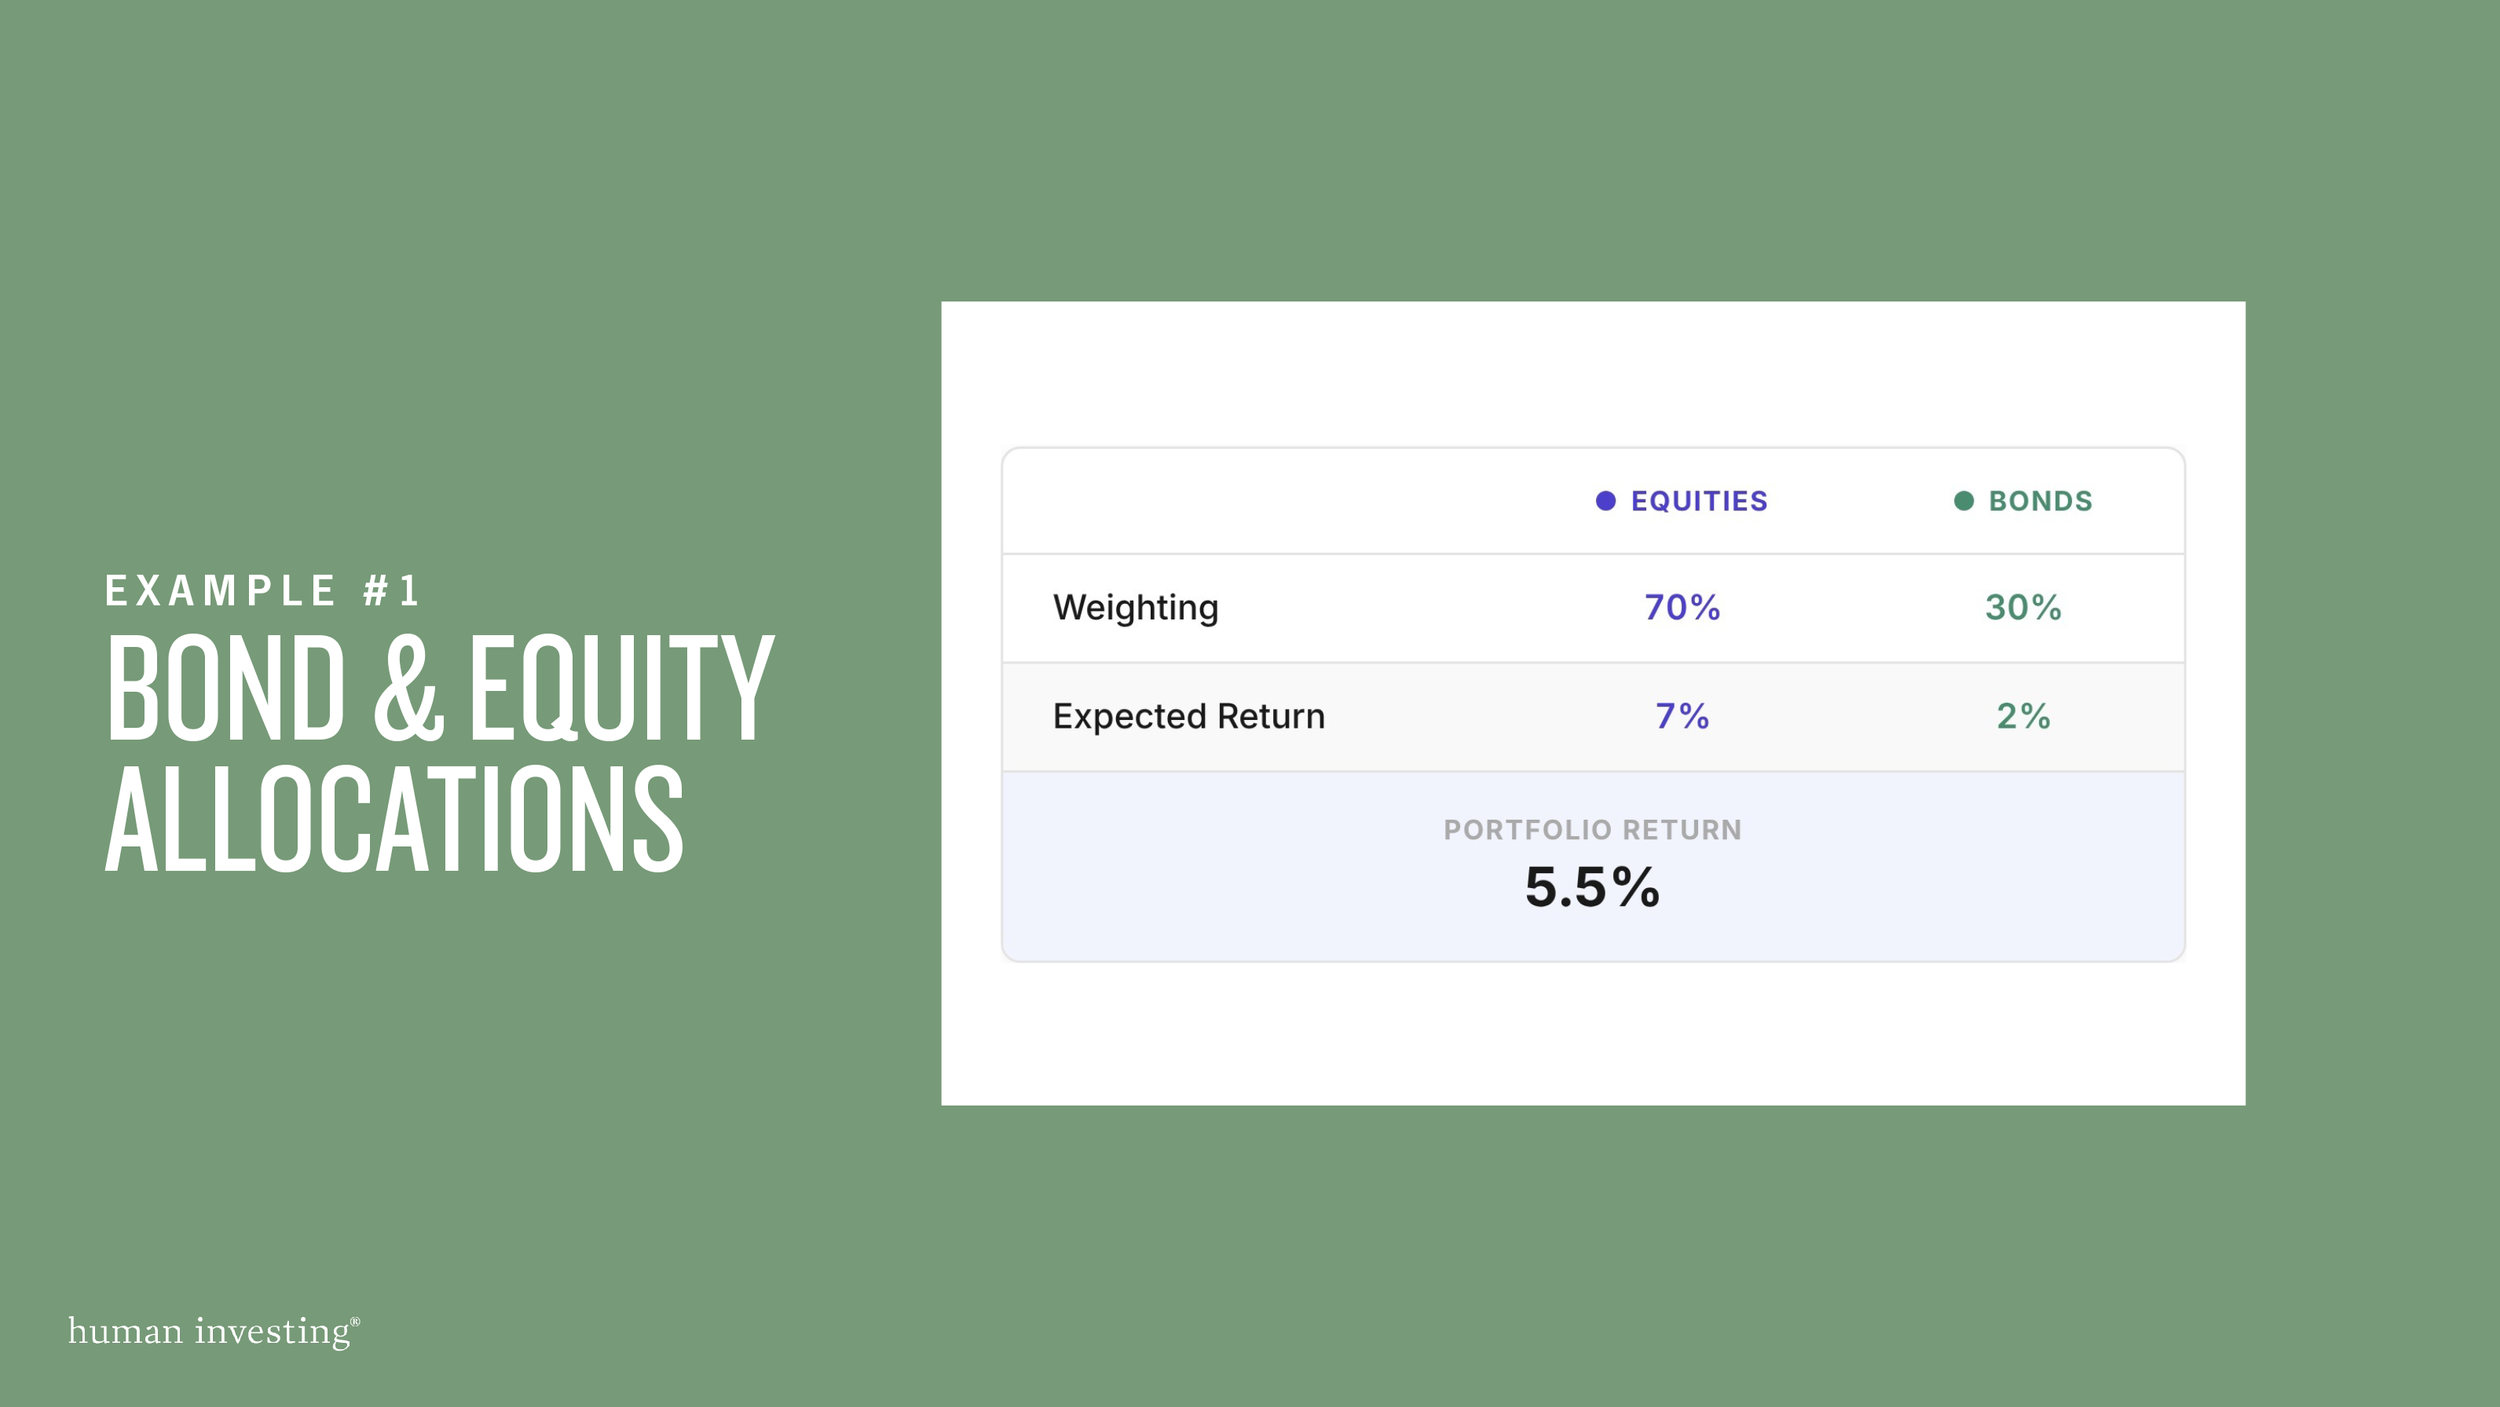
All numbers used in the above table are examples and should be used as educational material, not advice. (Nerd Wallet)
Today, higher starting bond yields allow us to potentially accomplish two things at once:
Use a more conservative expected return assumption for equities rather than relying on the exceptional returns of the recent past.
Increase the bond allocation while still maintaining an expected portfolio return consistent with the financial plan.
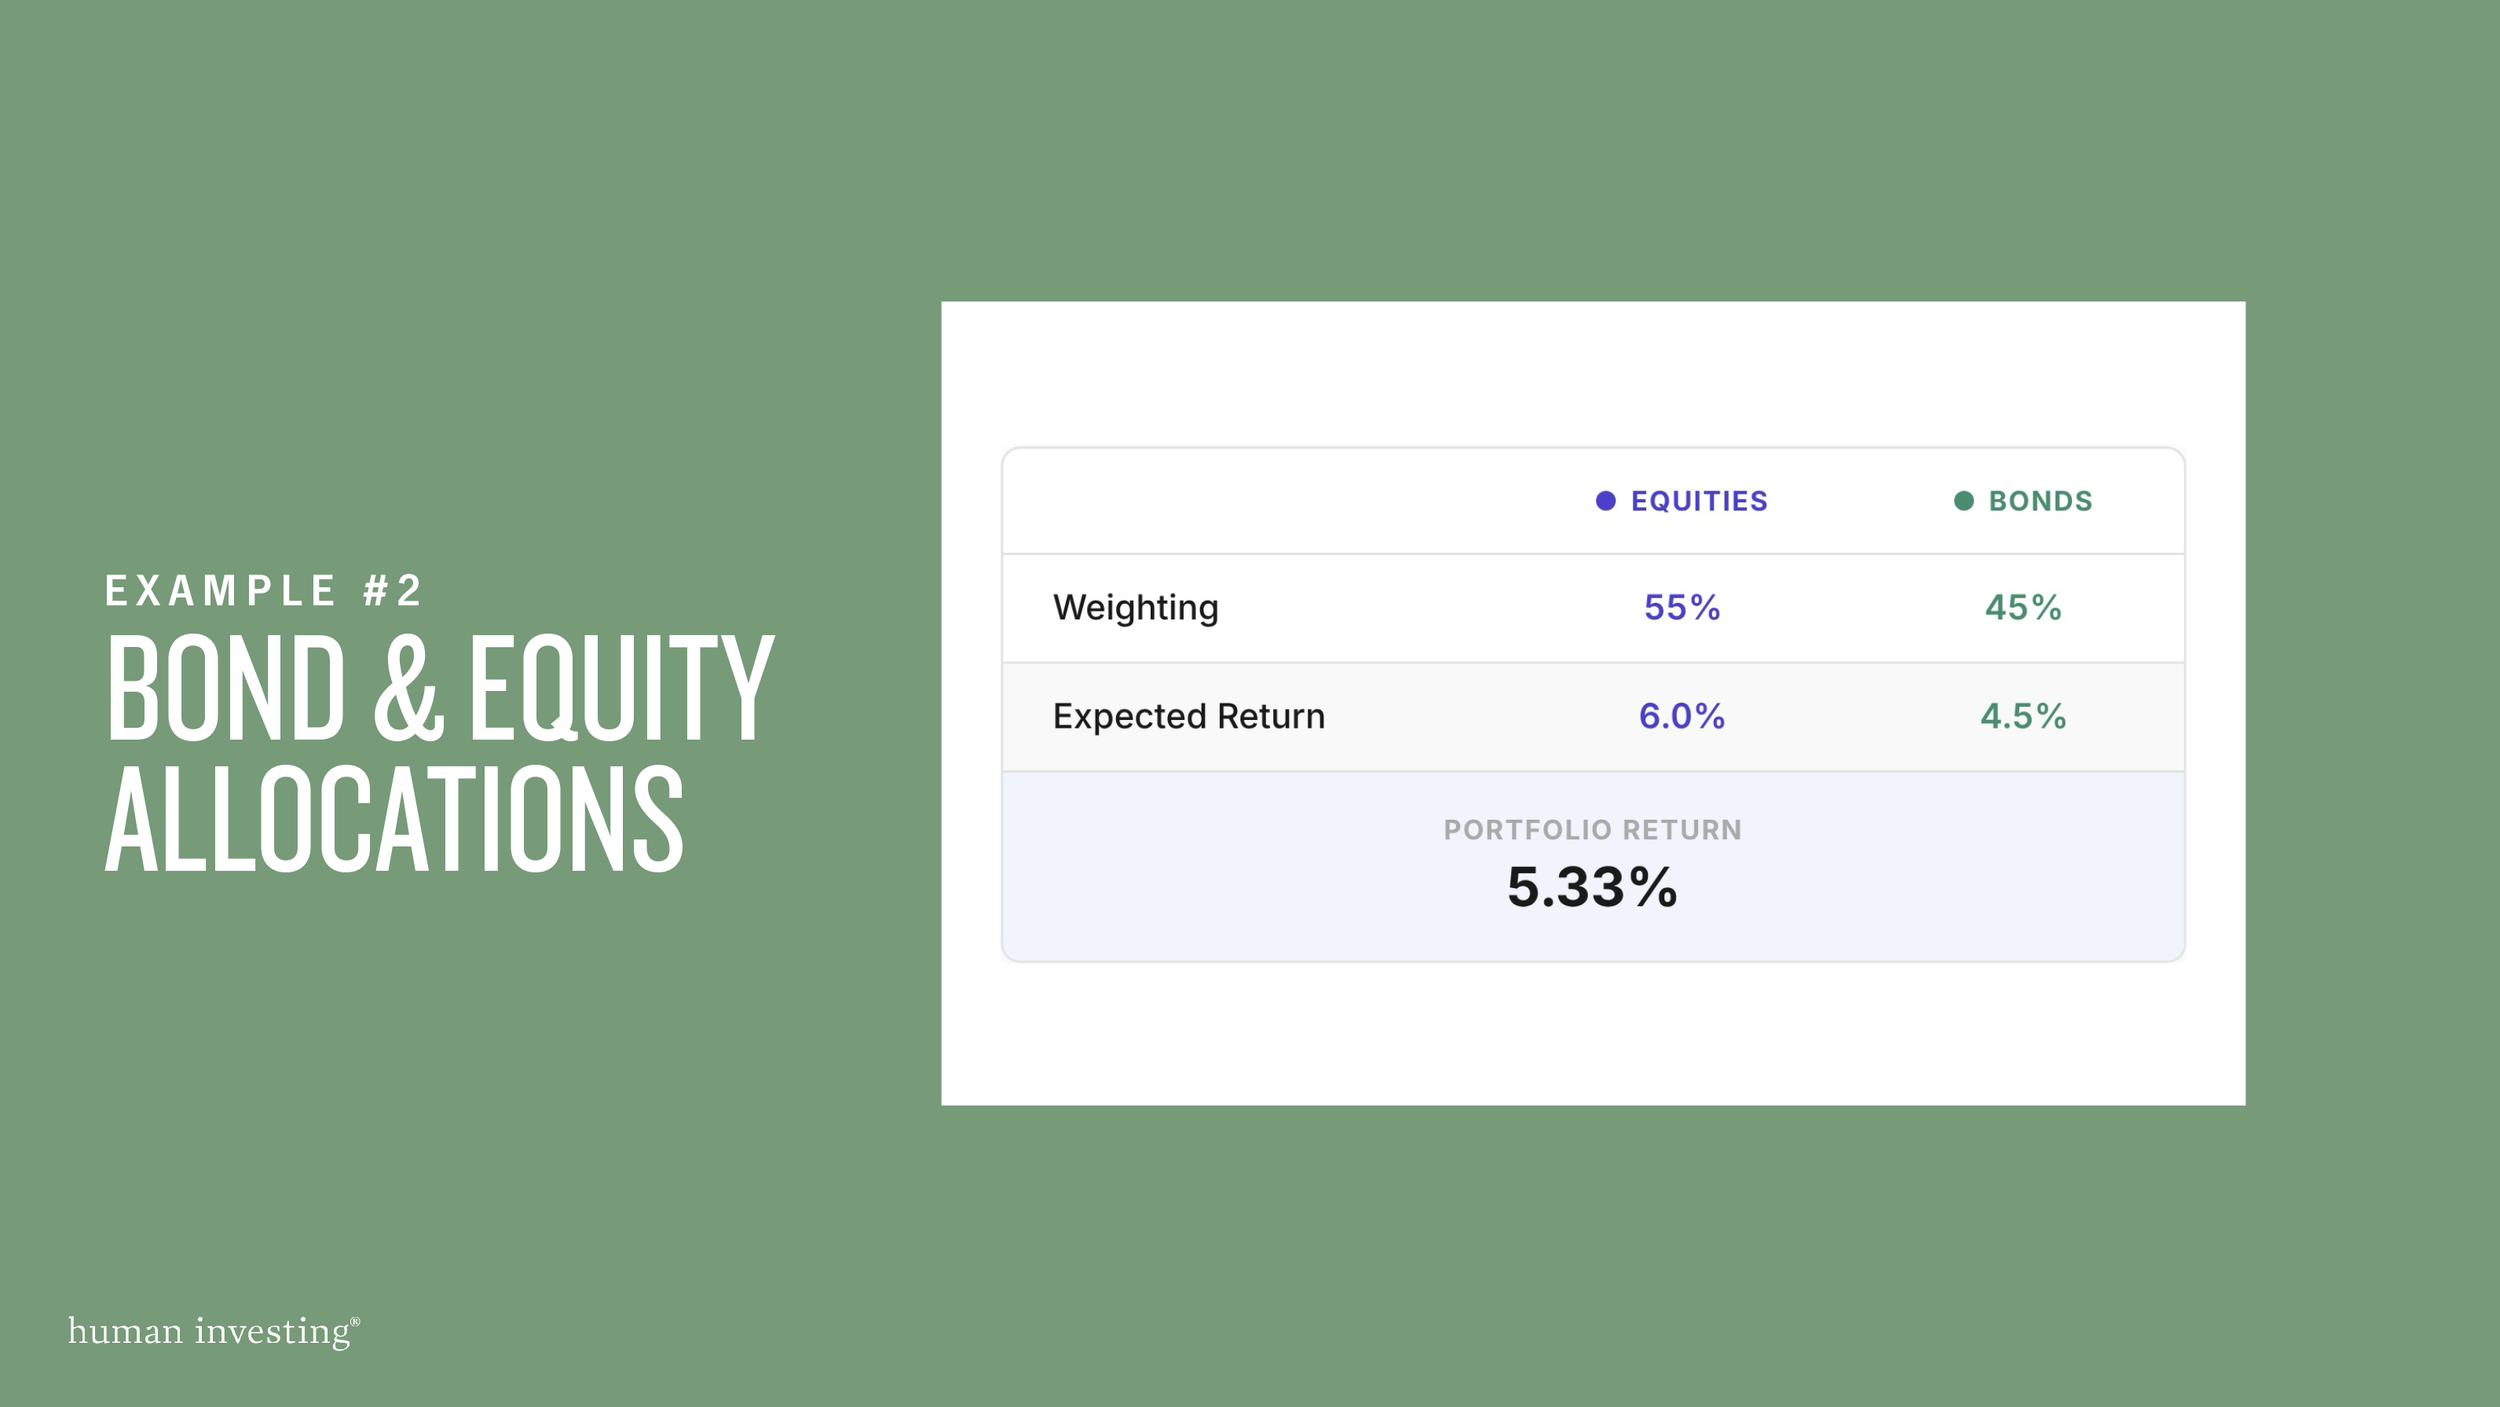
All numbers used in the above table are examples and should be used as educational material, not advice. (Nerd Wallet)
The point isn't that retirees no longer need stocks. It's that bonds can now contribute considerably more toward the portfolio's return objective, potentially reducing how much equity risk is required.
Today's Higher Yield Also Provides Something Bonds Didn't Have in 2020: A Cushion
As a reminder, when rates rise, existing bond prices fall, and when rates fall existing bond prices rise. That’s why 2022 was such a painful year for bond investors. But there's another part of the equation that sometimes gets overlooked: the income you're receiving from the bond.
In the chart below, Fidelity looks at the Bloomberg U.S. 7–10 Year Treasury Index and estimates the effect of a 100-basis-point (or 1-percentage-point) move in yields. August 2020 shows that if at that time rates went up 1% the index would fall 7.2% and if rates decreased 1% it would return a positive 8.2%.
Compare that to today where the starting yield is 5% where if rates increase 1% the index would decrease 1.9% vs. if rates decrease by 1% the index would increase 11.9%.
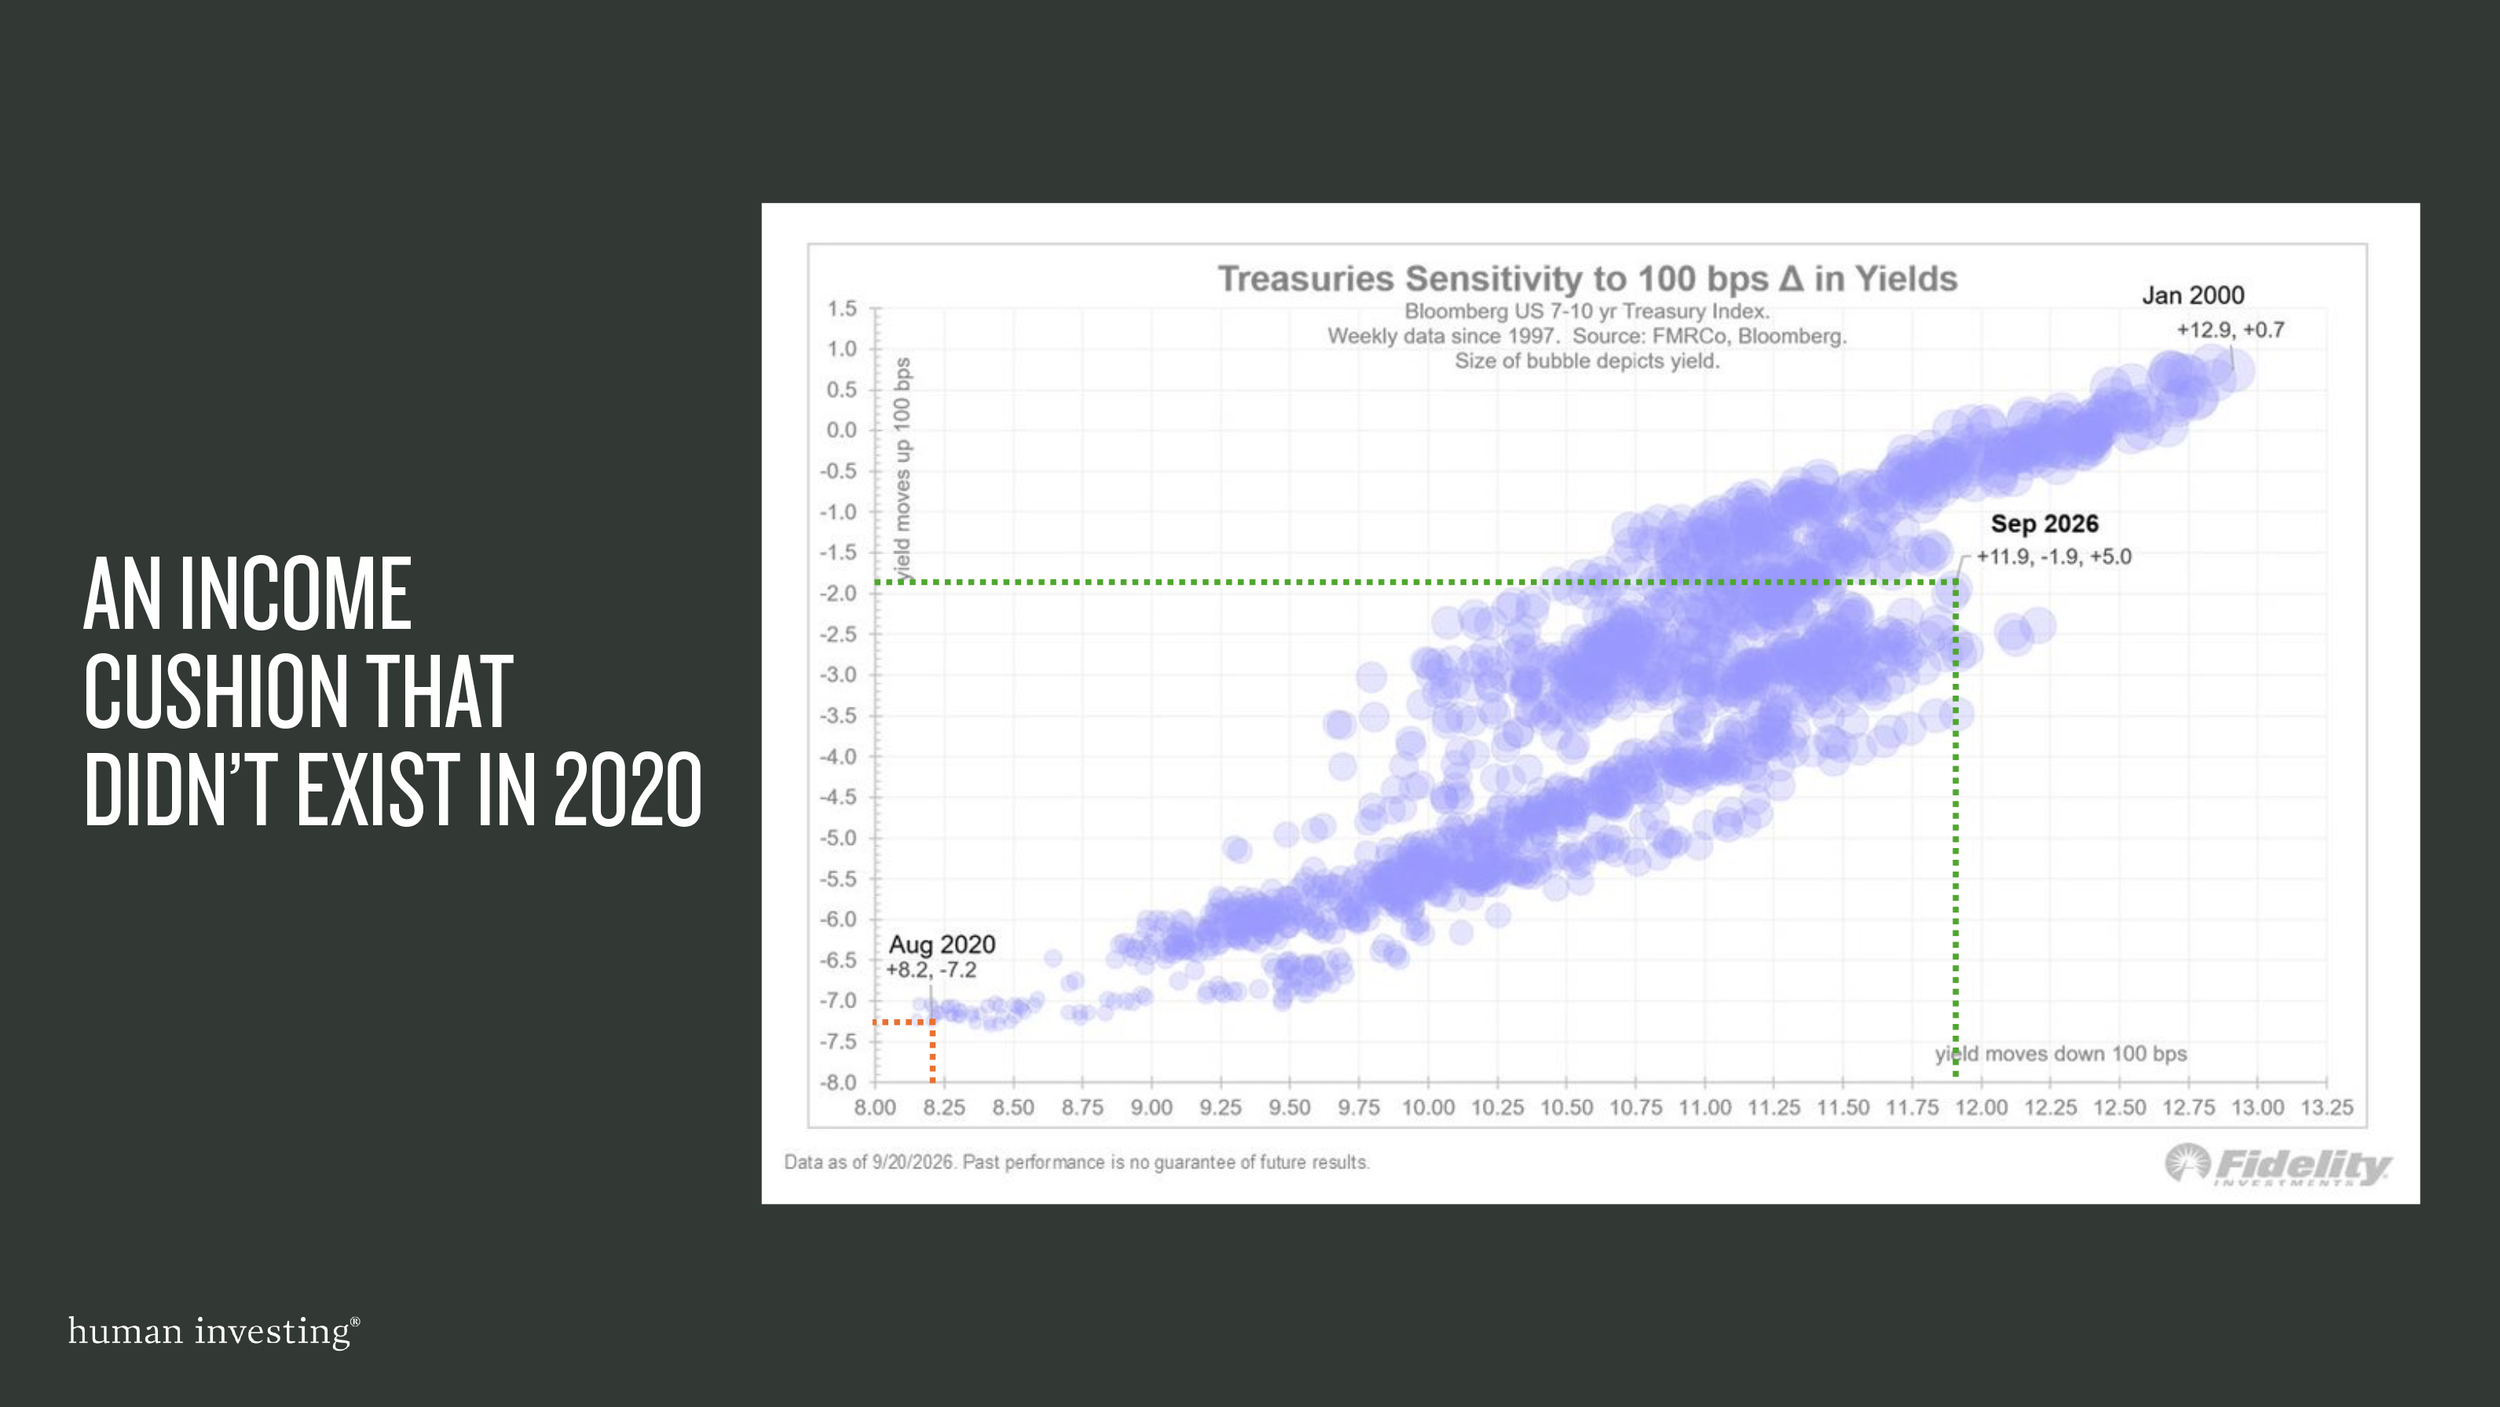
This scenario occurs when the investor is starting with considerably more yield. Higher yields don't eliminate interest-rate risk. But they change the starting point. When yields were near zero, there was very little income available to offset falling bond prices. With yields around 5%, investors begin with considerably more income working in their favor. If rates decline, bond investors may benefit from both the income they are receiving and price appreciation.
This is by no means a prediction of where interest rates are heading. The key point is that the starting economics of owning bonds are considerably different today then is was at any point over the last 15 years.
So, What Now?
A few closing thoughts for investors considering what this changing environment means for their portfolio.
This post is not a call to get out of stocks. My hope is that this post allows investors to review their portfolio and take inventory of their allocation. Reducing risk because you think the stock market is about to fall is market timing. Reducing risk because your financial plan no longer requires you to take as much risk is financial planning. This post is asking you to consider the latter.
For individuals nearing or already in retirement, the consequences of investment risk are also different than they were earlier in life. For someone who is 35 and accumulating assets, volatility can actually be useful. They're continuing to buy investments and have decades before they'll need the money. The equation changes as retirement approaches. A significant market decline during the first few years of retirement can be particularly damaging because an investor may simultaneously be experiencing investment losses and withdrawing money from the portfolio to fund their lifestyle. That's when the amount of risk you take and the risk you actually need to take, becomes increasingly important.
Don’t start with your investment allocation; start with your plan. We have an amazing team of CFP’s at Human Investing who remind me of this frequently.
Instead of starting with questions like:
"Should I own 60% stocks?"
"Should I move from 70/30 to 60/40?"
"Are bonds attractive?"
"Is the stock market overvalued?"
Start with one step earlier: What does my money need to accomplish, and what rate of return does my financial plan require to get me there?
Once you understand that number, many of the other questions become easier to answer.
The goal of retirement investing isn't to earn the highest return possible. It's to earn the return necessary to accomplish your goals while taking an appropriate amount of risk along the way.
After 15 years of strong equity returns and a dramatic change in the bond market, this may be an especially good time for pre-retirees and retirees to revisit that calculation.

Disclosure: Human Investing is an SEC-registered investment adviser. Registration does not imply a certain level of skill or training. This content is for informational and educational purposes only and does not constitute personalized investment advice or a recommendation. Past performance is not indicative of future results. All investments carry risk, including potential loss of principal. Readers should consult with a qualified professional regarding their specific financial situation.