The IRS has Increased Contribution Limits for 2027
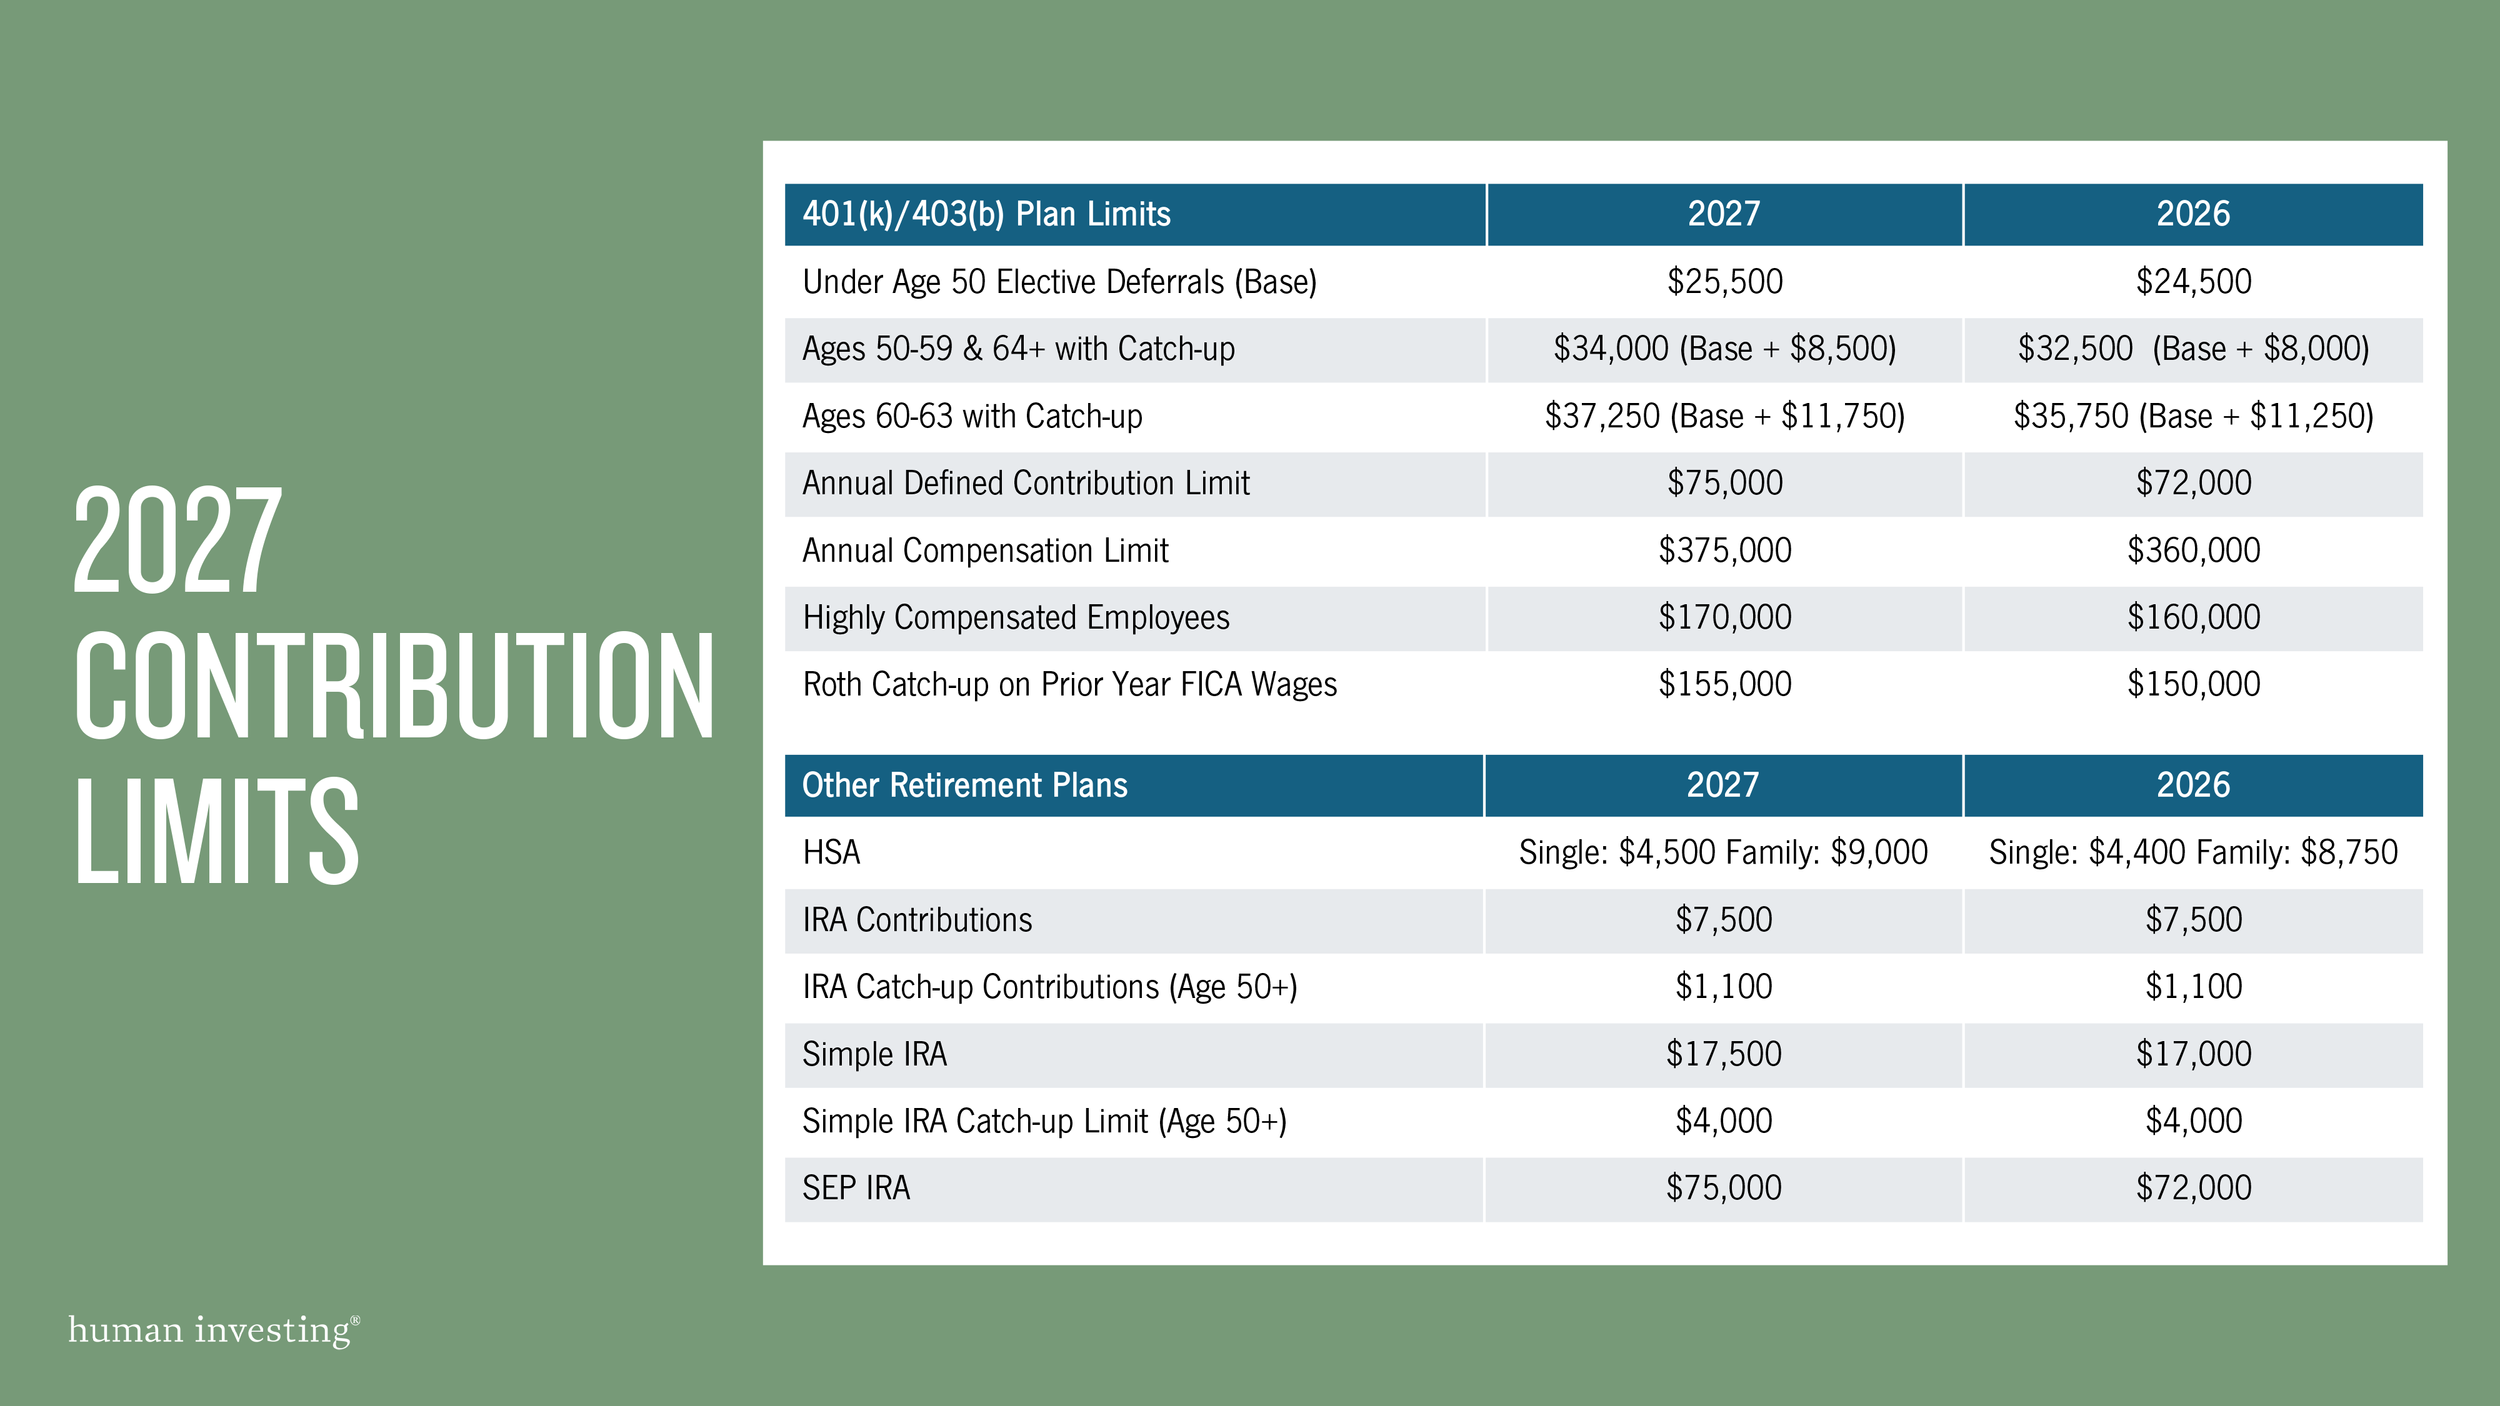
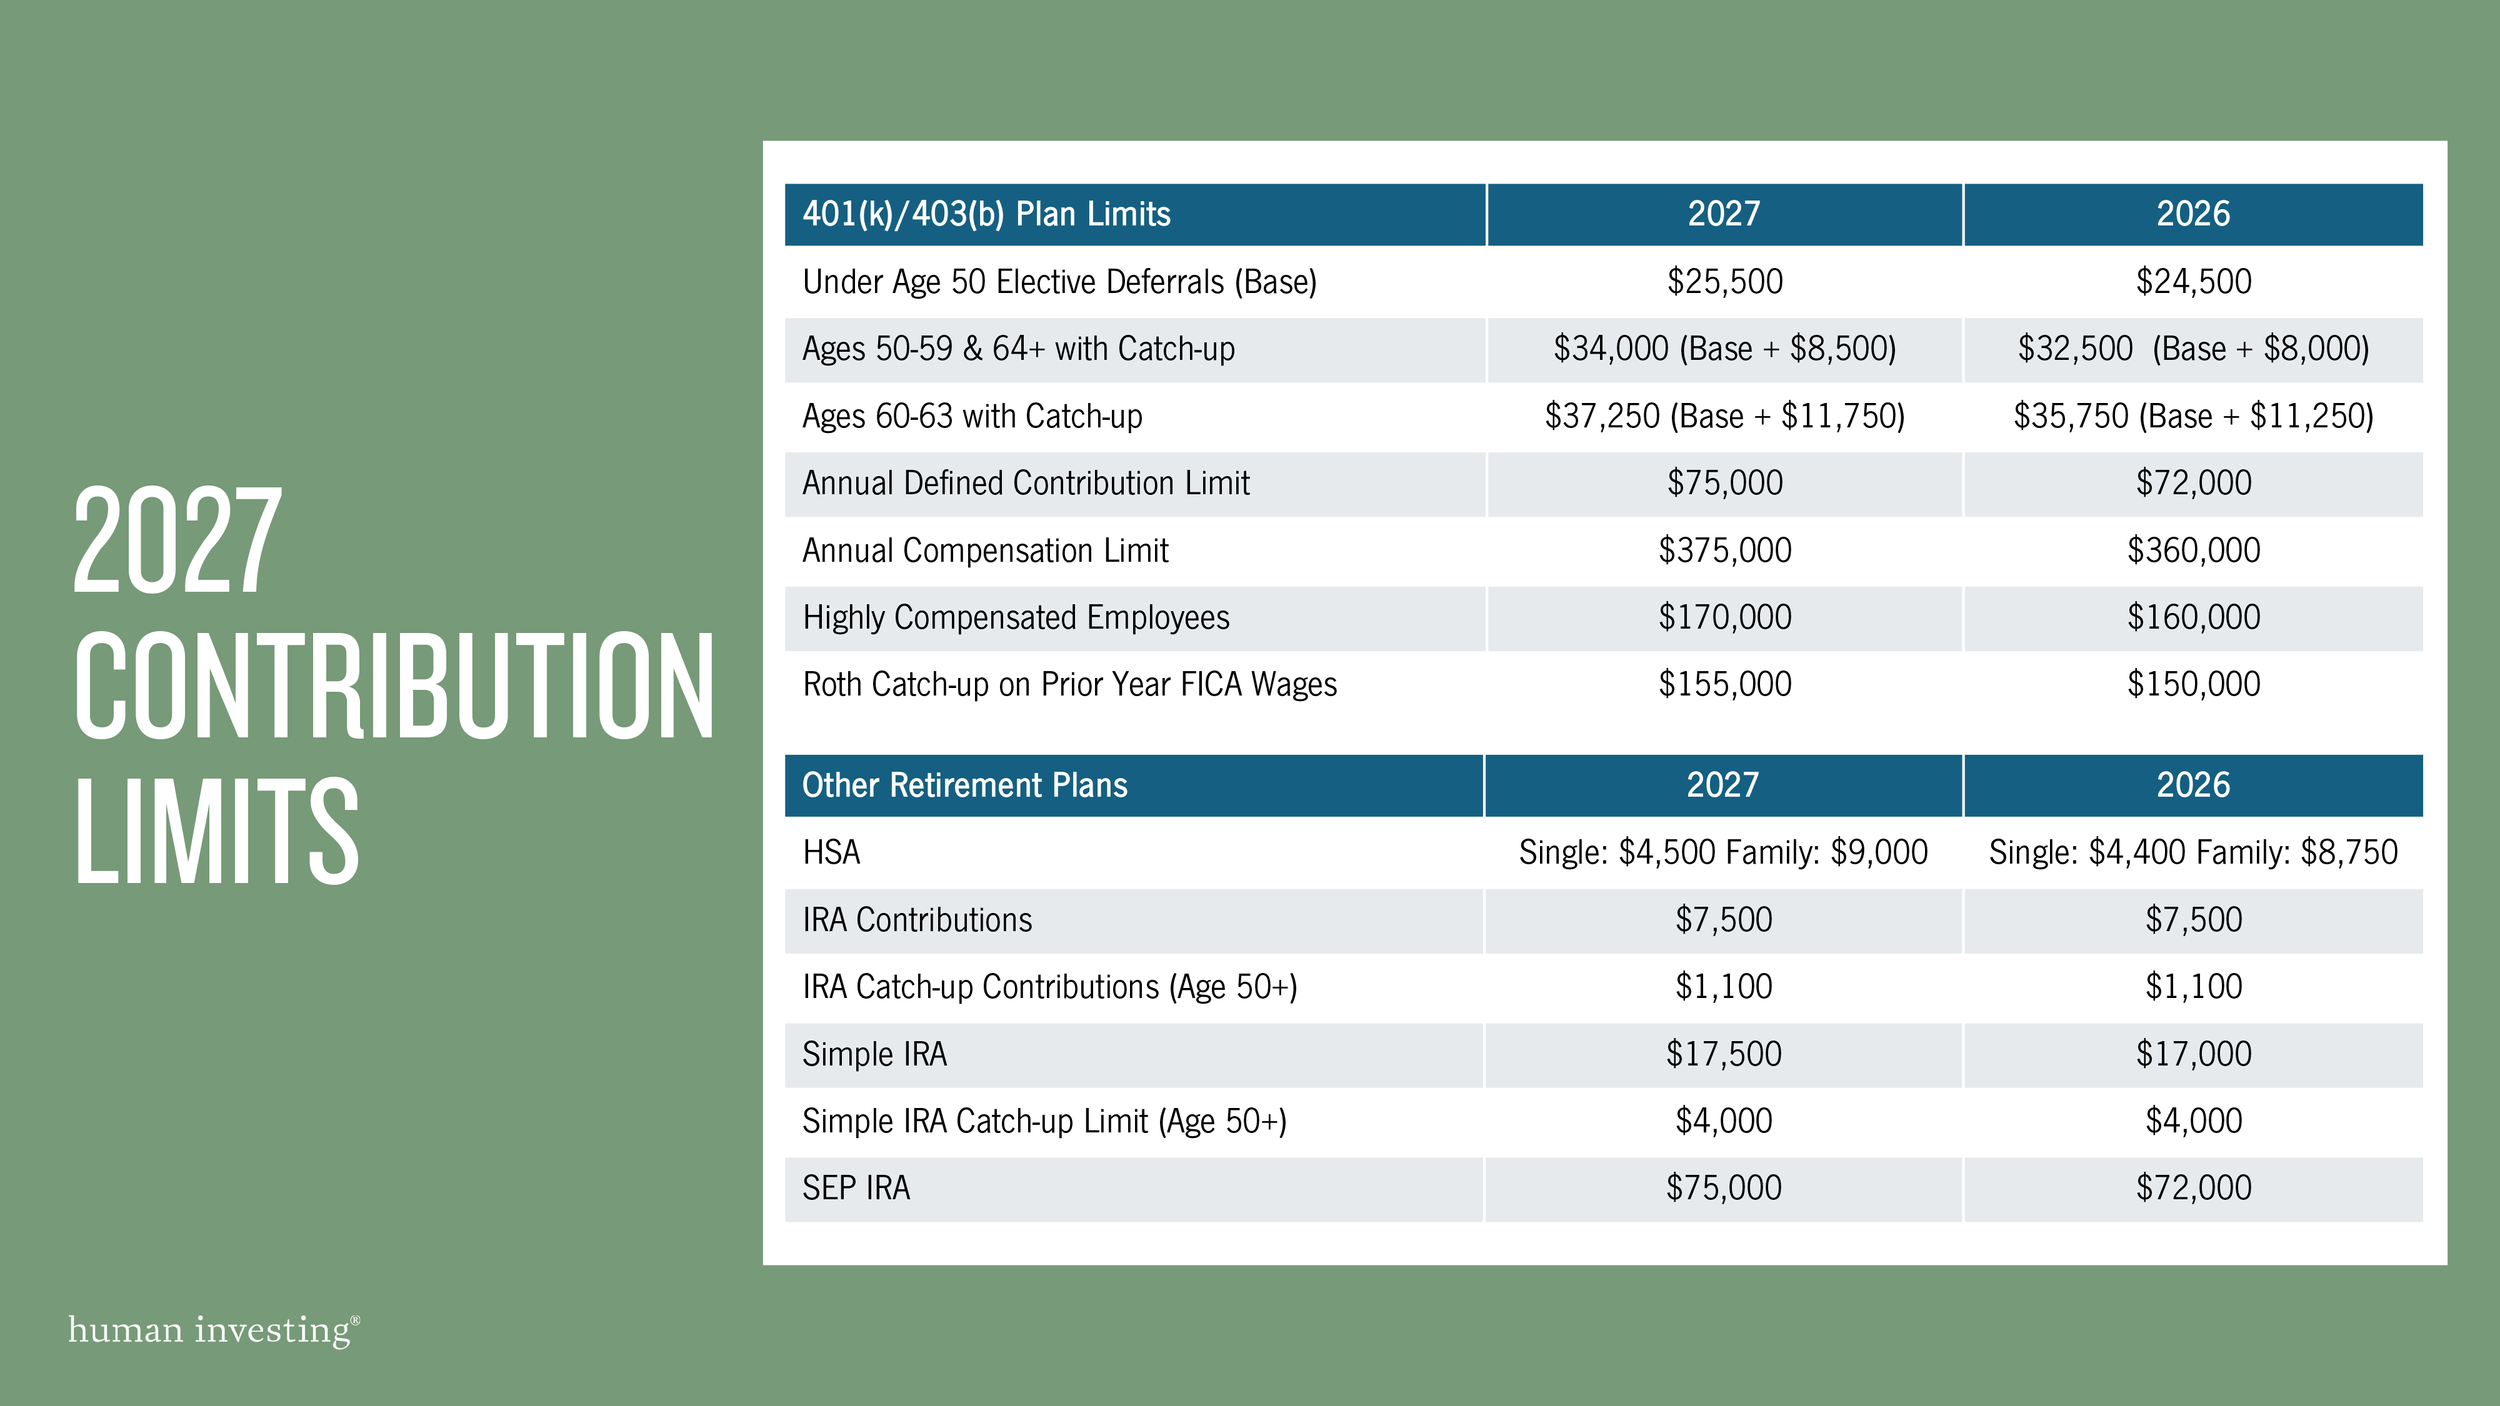
There is good news for retirement accounts next year. The IRS has released the updated contribution limits for 2027, and several of the adjustments allow investors to save more towards retirement. Seen in the table below, these new limits continue the trend of expanding opportunities for retirement savers.
For 2027, the enhanced “super” catch-up remains in place, giving later career savers another year to take advantage of increase contribution amounts.
Source: IRS.gov
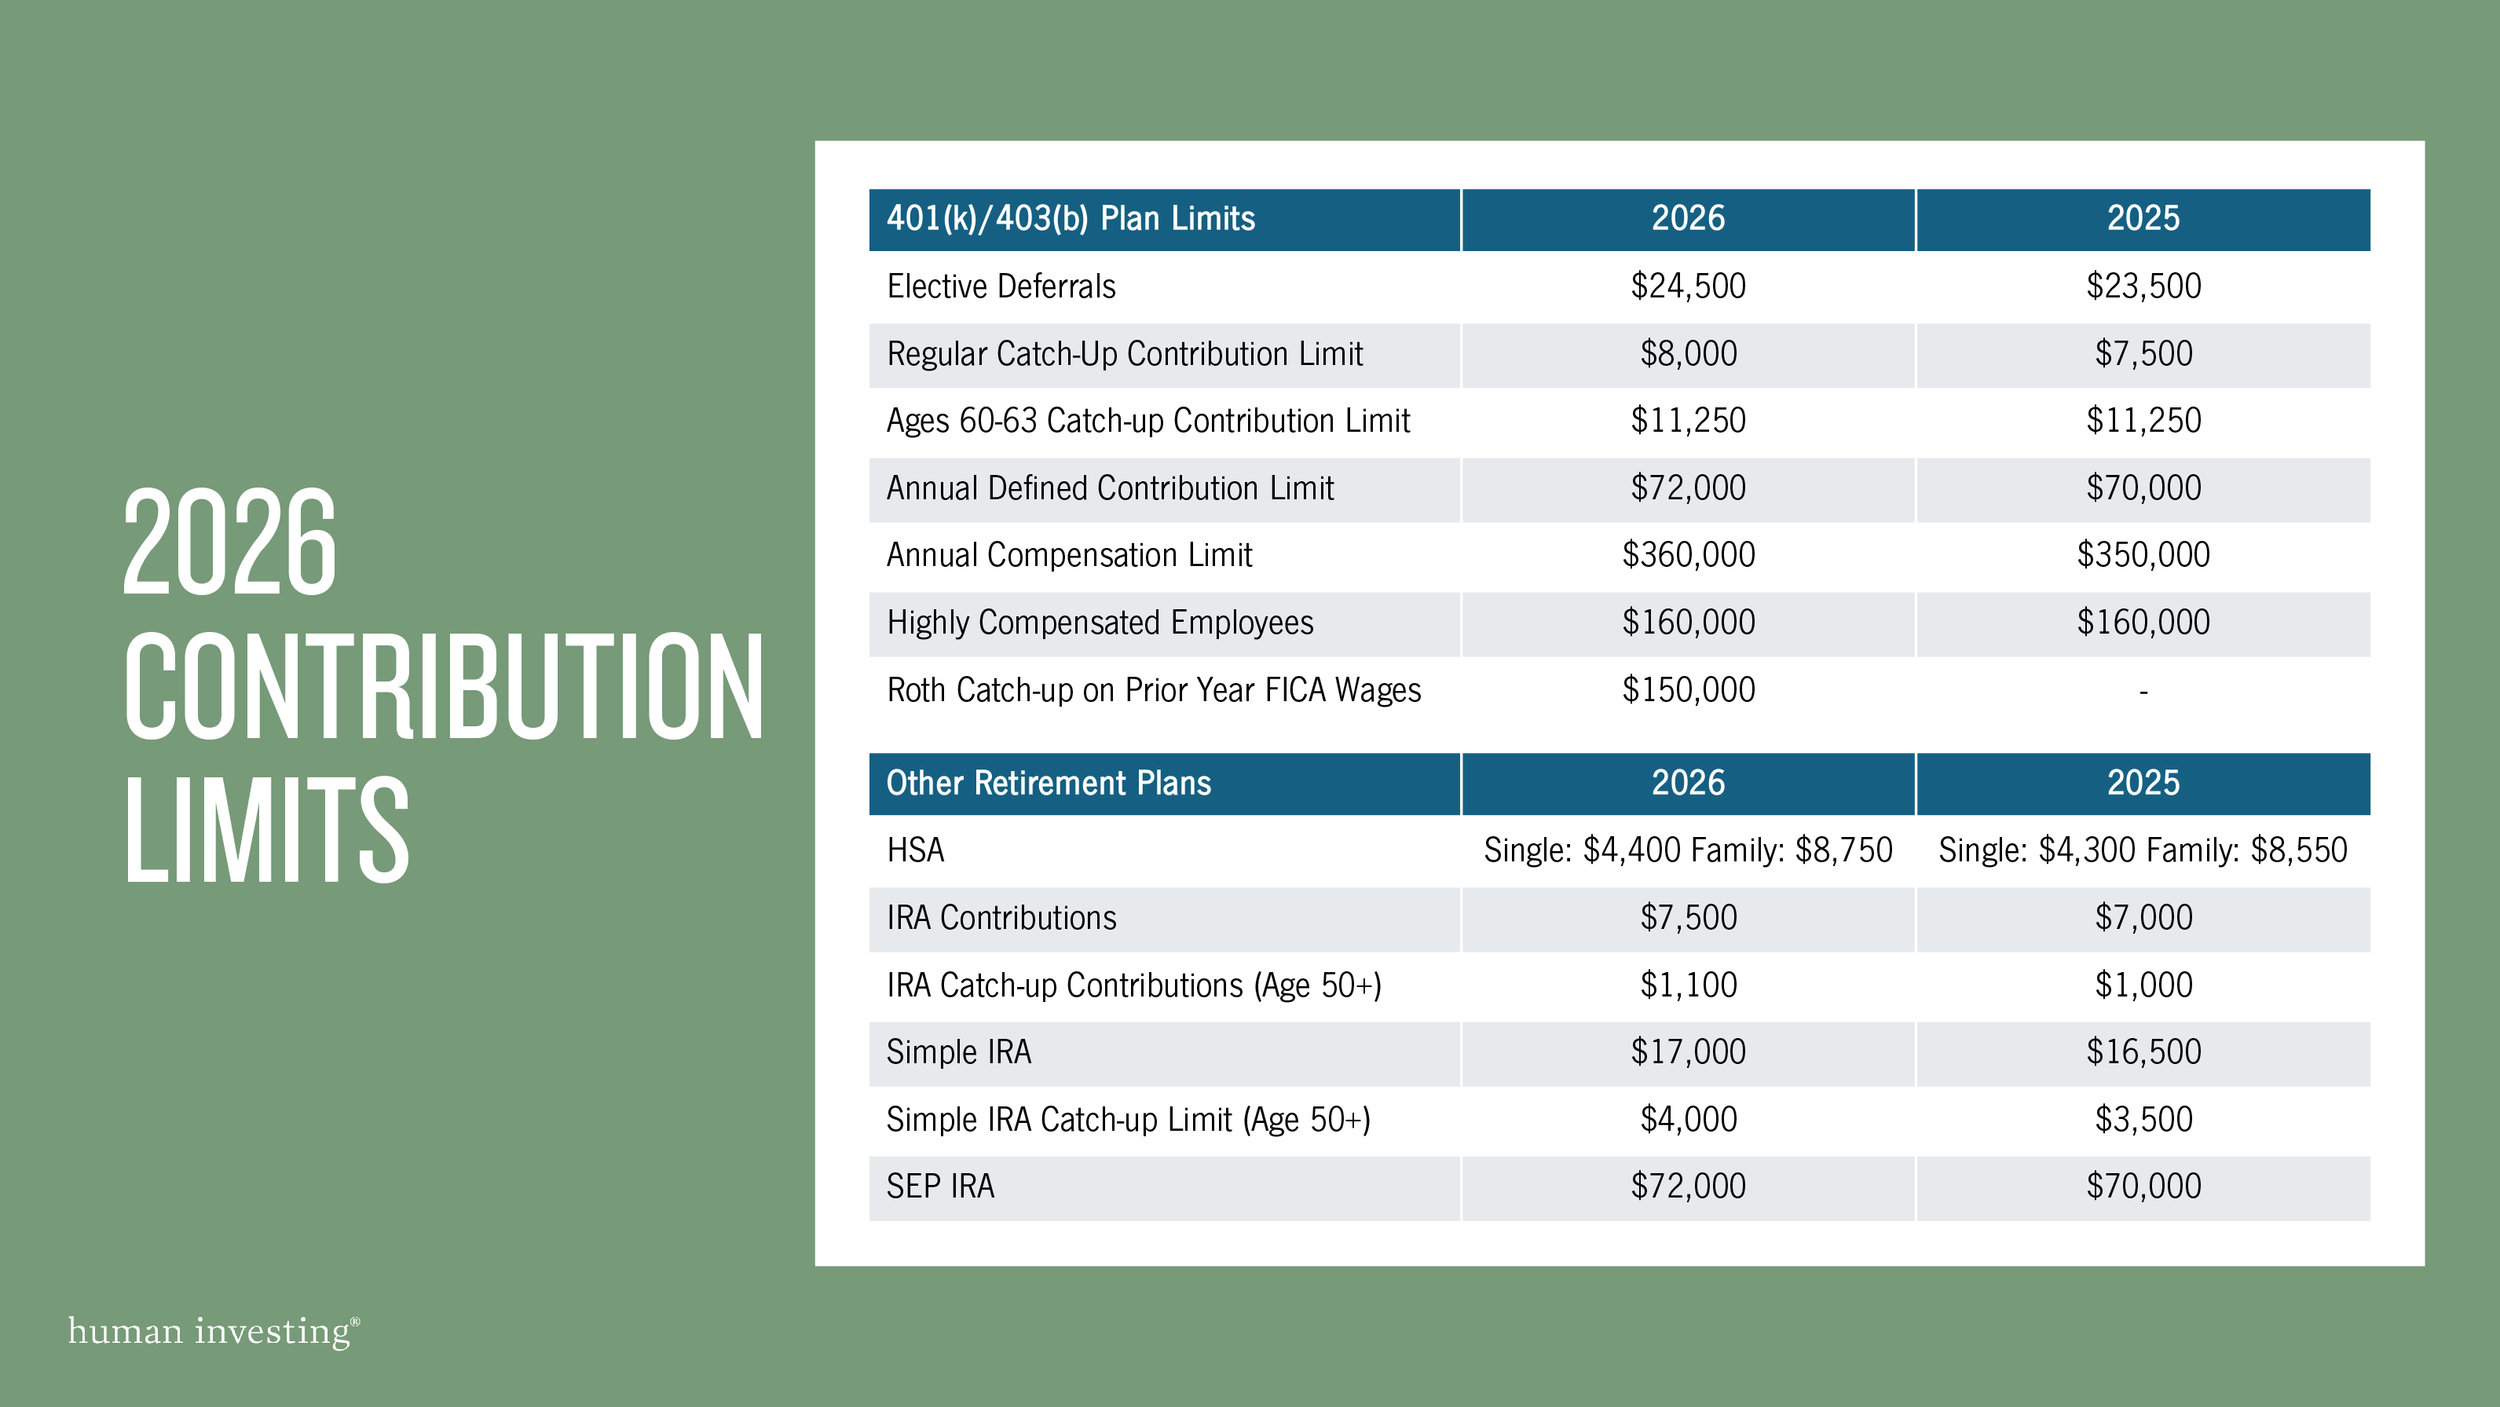
On top of the increased limits above, another important item to be aware of is the Roth Catch-Up Requirement. 2026 was the first year this rule was in place, and it required certain high-earning employees to make their catch-up contributions on a Roth basis. The rule applied to employees whose prior-year FICA wages from the employer sponsoring the plan exceeded $150,000.
In 2027 the FICA wage threshold has increased to $155,000. That means you are subject to this rule if you:
Are eligible to make catch-up contributions because you are or will be age 50 or above in 2027, and
Your prior-year FICA wages from the employer sponsoring your retirement plan are greater than $155,000
If you fit these conditions, then your catch-up contributions must be made as Roth.
This does not impact your regular contribution limit of $25,500, and if you want to maximize your pre-tax contributions you need to do so before making any Roth contributions. Think of your retirement savings as two buckets: normal contributions and catch-up contributions. Your normal contribution bucket has to be filled before the catch-up bucket is filled, and any Roth contributions that you make prior to contributing $25,500 will count as normal contributions.
How do these changes impact your savings in the upcoming year? Are there any changes you should be making? Schedule a time to meet one-on-one with our team. We look forward to working with you in 2027!