Posts tagged will kellar
The Reality Behind Social Security: What the 2032 Deadline Really Means
 

It sounds bleak. And when I talk with people who are getting close to retirement, they feel the same way.

It doesn’t help that headlines about Social Security “running out of money” have become more common. And, with congress approaching a funding deadline that is no longer decades away, it's understandable that people nearing retirement want to know what that means for them.

Our team went through the 273-page 2026 Social Security Trustees Report to get a clear picture of what is actually happening. And… the future of Social Security may not be quite as grim as the headlines suggest.

The short version is that Social Security is spending more than they are bringing in, and something needs to change. But I think there is an important part of the story that gets lost in the headlines.

Running out reserves is not the same thing as Social Security disappearing. Understanding this distinction matters, especially for retirees tempted to make decisions out of fear rather than what’s best for their financial plan.  

The Real Issue: Social Security’s Trust Fund

Quick background on Social Security, it is primarily a pay-as-you-go system. Payroll taxes collected from today’s workers and their employers are funneled to pay benefits to today’s retirees.

For much of Social Security’s history the taxes collected amounted to more than it needed to pay current benefits and that surplus of dollars accumulated in the current trust funds. However, today, the opposite is happening. Benefits and other program costs are greater than the revenue coming in, so Social Security is using those reserves to cover the difference.
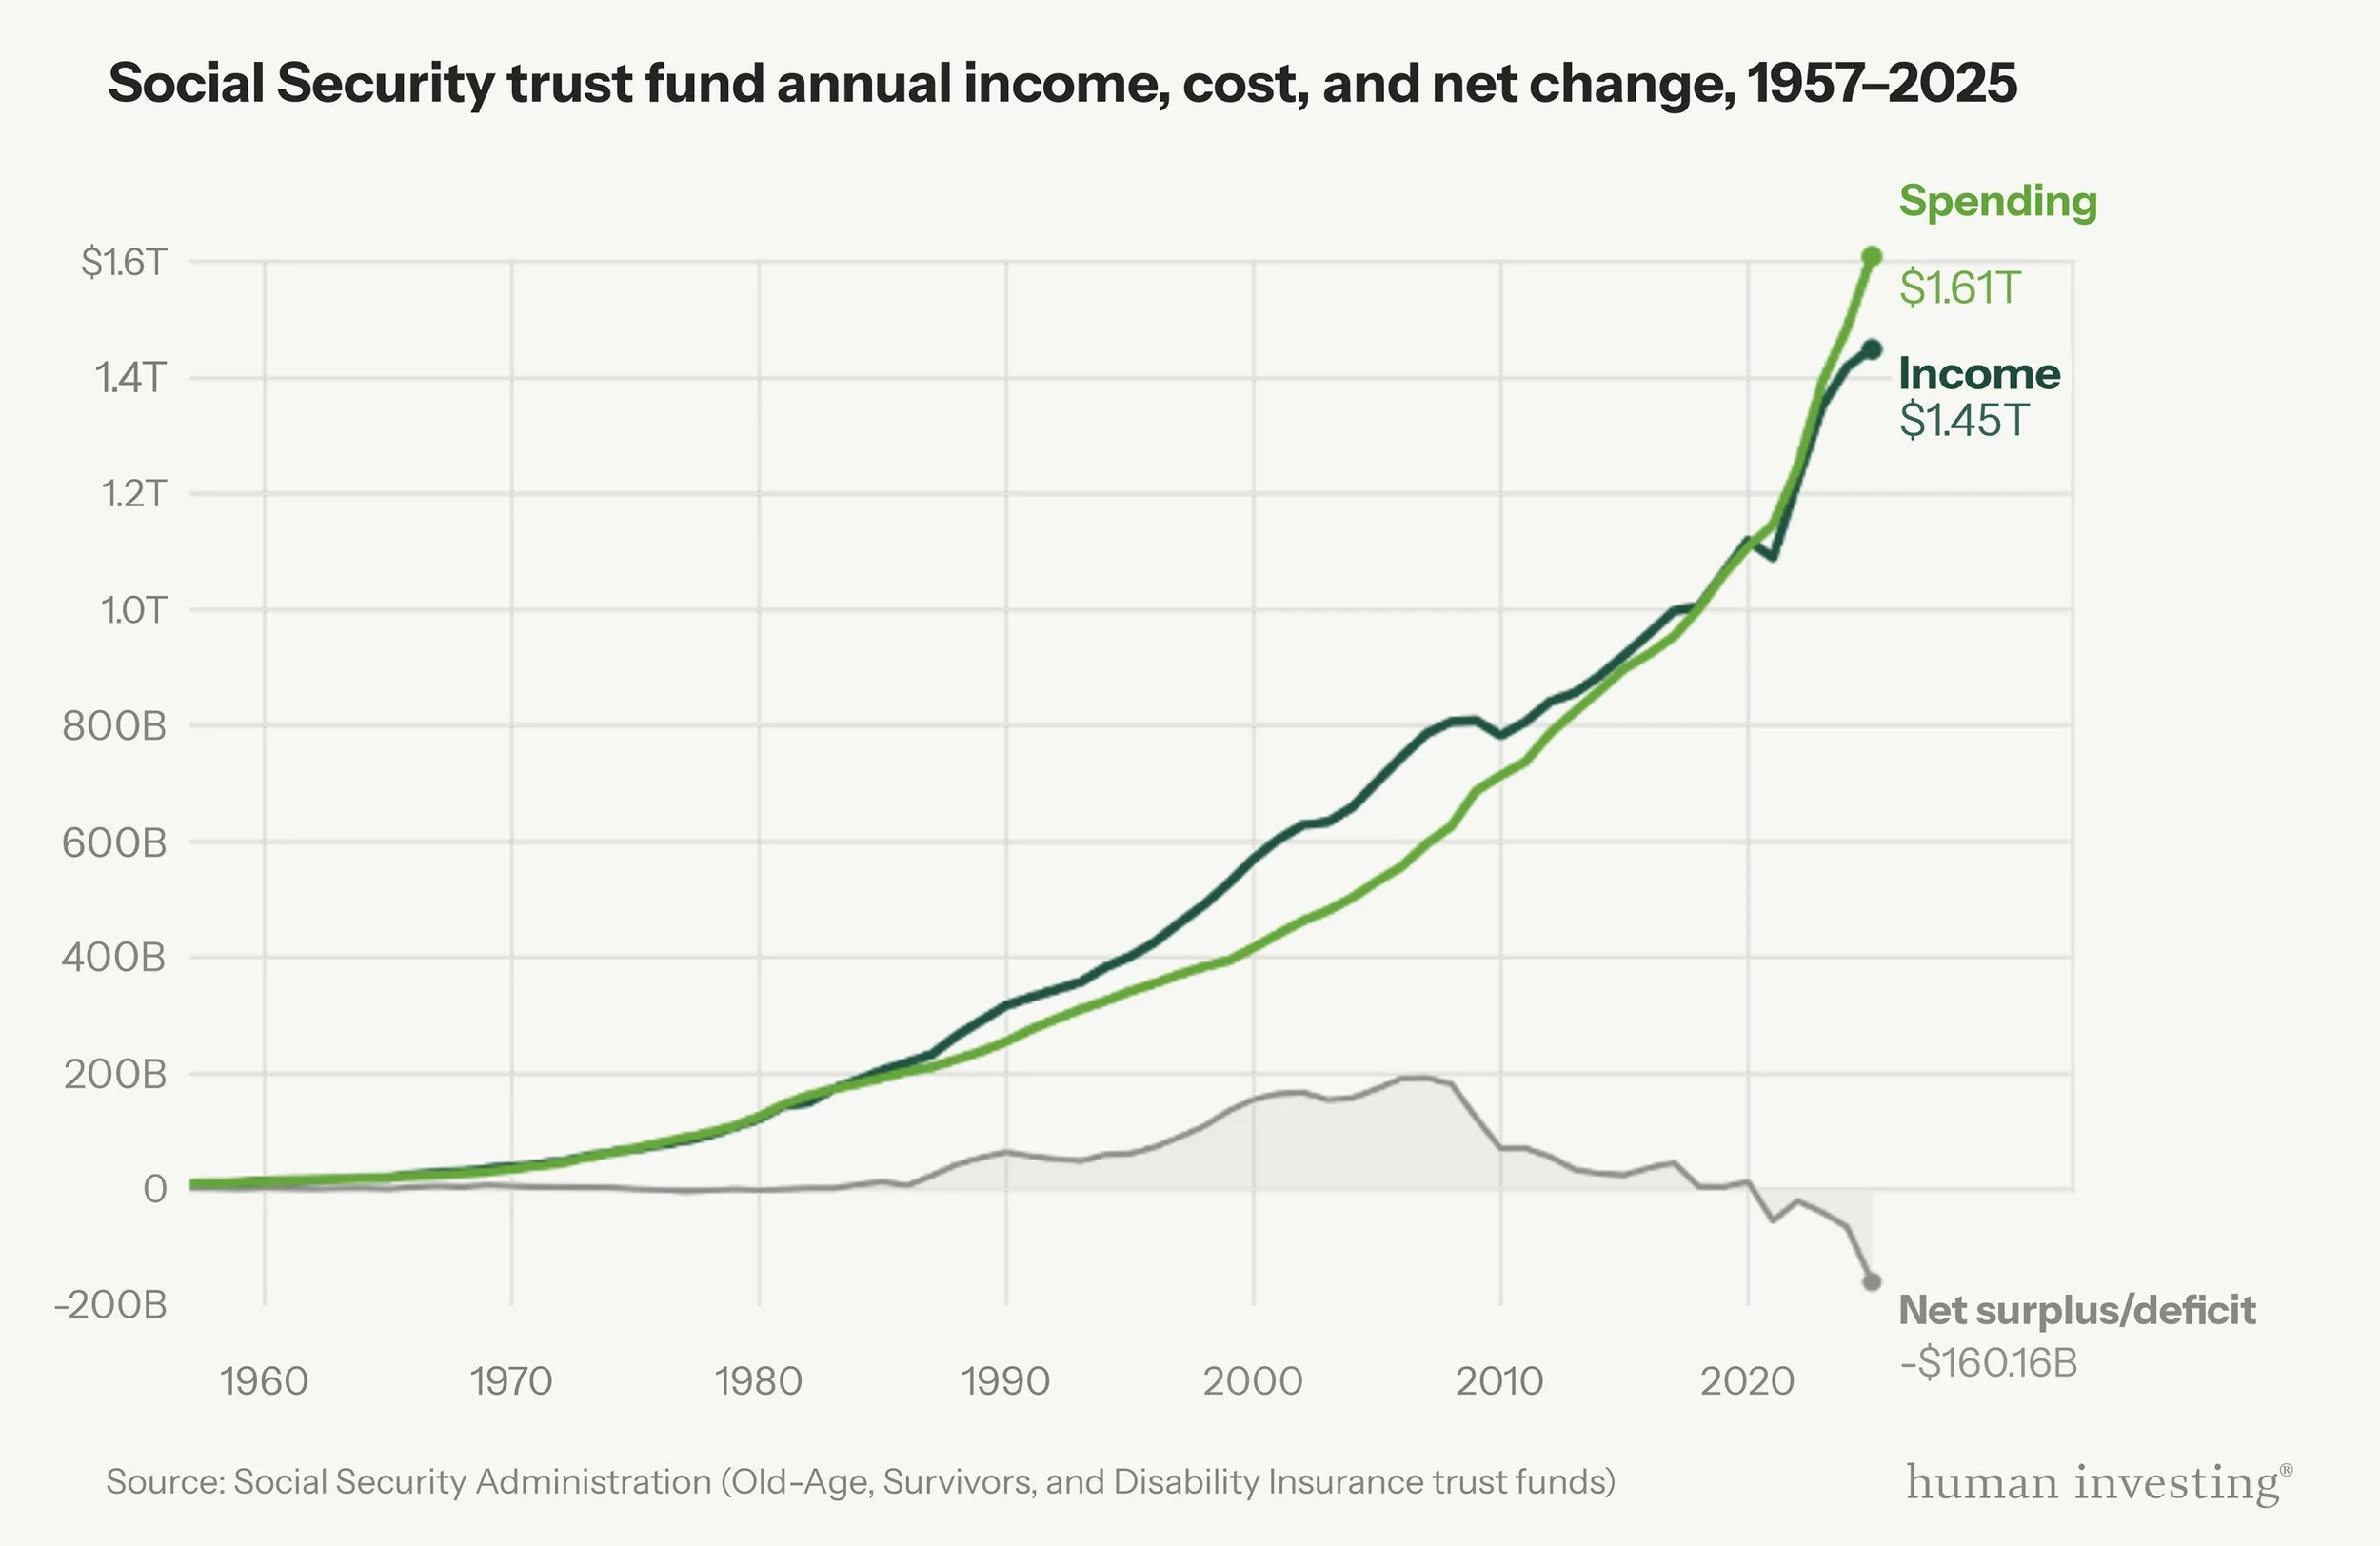
The issue comes from a demographic imbalance. Baby boomers are retiring, which leaves fewer workers to support each Social Security beneficiary. This creates a pretty straightforward math problem: benefits are growing faster than the payroll tax revenue available to support them.

Since 2021, Social Security’s total costs have surpassed its total income, requiring the program to draw down its reserves. With the current projections, the OASI trust fund, that pays retirement and survivor benefits, is expected to exhaust those reserves in 2032.

While this sounds alarming, it doesn't mean Social Security will vanish.

What Happens in 2032?

The common misconception is that the depletion of the trust fund means Social Security will go bankrupt and cease to exist.

The Social Security trust fund that pays retirement and survivor benefits is projected to run out of its reserves in the fourth quarter of 2032. If Congress makes no changes before then, the programs income would be enough to pay approximately 78% of scheduled retirement and survivor benefits ([1] pg.5).

This doesn’t mean Social Security benefits suddenly stop when the trust fund is depleted. Workers would still be paying Social Security taxes, and these taxes would continue to provide a significant portion of benefits.

I also don’t want to downplay what a potential 22% would mean for retirees. For someone expecting $4,000 per month from Social Security, a 22% reduction would mean $880 less each month, or more than $10,000 per year. This is considerable difference for someone counting on this income.

This is why I have a hard time with either extreme. Saying Social Security is “going bankrupt” overstates the problem but saying there is nothing to worry about understates it.

Congress Has Options, but None Are Painless

The Social Security administration has given congress several ways to improve Social Security’s finances. Here are some potential strategies:

  1. Increase Social Security Payroll Tax – Today, employees pay 6.2% of wages into Social Security, with employers contributing another 6.2%. If you’re self-employed, you’re generally responsible for both, 12.4%. Congress could increase those percentages which would help close the long-term funding gap, although it would mean higher taxes for workers and employers.

  2. Increase the Social Security Wage Base – In 2026, Social Security taxes only apply to the first $184,500 of earned income. Anything above that amount is not subject to Social Security payroll taxes. Congress could raise the wage base limit, eliminating it all together, or begin taxing again above a higher income level. These approaches could generate additional revenue but at the cost of higher earners.

  3. Adjust Future Benefits – Another option would be to change how Social Security is calculated. This can include changing the benefit formula, annual cost-of-living increases, or benefits paid out to higher-income retirees. These changes could improve Social Security’s finances, but future retirees would still receive less than they are currently expecting.

  4. Increase Full Retirement Age (FRA) – For anyone born in 1960 or later, Full Retirement Age is currently 67. Congress could push that age higher. This might sound like a small change, but it would effectively reduce benefits for future recipients. Someone who wanted to retire at the same age would receive a smaller monthly check, or they'd need to wait longer to receive their full benefit.

    We've seen this before. Social Security's Full Retirement Age was originally 65, and legislation passed in 1983 gradually increased it to 67.

  5. Invest in Equities – The SSA has proposals that would simulate a portion of the reserves to be invested in equities instead of solely in government securities. Higher expected returns could improve solvency, but investment changes alone would not eliminate the funding shortfall

If I had to guess, the eventual solution will be some combination of changes rather than one simple fix. The longer Congress waits, the harder it becomes to phase those changes in gradually, which is a reason the discussion is becoming more urgent.

Should the Funding Problem Change When You Claim Social Security?

This is where the policy discussion becomes much more personal.

For many retirees, deciding when to claim Social Security is one of the most pivotal decisions they will make around retirement. It can affect not only their own monthly income for life, but also a spouse’s survivor benefit, their tax situation, and how much they need to withdraw from their portfolio.

As an advisor I sometimes hear investors say, “I should take Social Security as soon as possible because I want to get my money before it runs out.” I understand the instinct: if future benefits might be reduced, why not start collecting now?

Whether to claim at 62, Full Retirement Age, or 70 should consider many factors including life expectancy, marital status, survivor benefits, taxes, other retirement income, portfolio withdrawals, and the value of securing a larger guaranteed lifetime benefit.

Claiming early permanently reduces your monthly benefit. While delaying can meaningfully increase it. Someone who claims early because they are worried about a future cut may be giving up a larger lifetime income stream to protect against a change that Congress may ultimately address in a very different way.

Social Security’s finances should absolutely be part of the conversation. They just should not be the only part of it.

Build a Plan That Doesn’t Depend on Predicting Congress

I have my guesses about how Congress might address this, but that’s all they are.

For those planning for retirement, rather than trying to predict the outcome, a better approach is to stress-test the retirement plan under different Social Security assumptions. Model the impact of receiving 100% of your projected benefit, then look at what happens if only 80% of that benefit is available beginning around 2032.

The goal here is not to predict a 20% cut, but rather to understand how dependent the plan is on Social Security and where it may be vulnerable. Does the plan still work if benefits are reduced? Can the portfolio provide enough additional income? Would spending need to change? Are there other reliable income sources? Does the claiming strategy still make sense under each scenario?

We use this same approach with other uncertainties like markets, inflation, taxes and longevity. A resilient plan does not require every assumption to be right. What it needs is to be built with enough flexibility and margin to remain successful when things don’t go as expected.

And I think Social Security should be treated the same way. It's an important source of retirement income for millions of Americans, but we don't know exactly what Congress will do or when they'll do it.

What we can do is understand how dependent your retirement plan is on Social Security, consider what happens if benefits change, and make decisions today that give you flexibility down the road.


Disclosure:
This material is provided for informational and educational purposes only. It should not be construed as investment, legal, or tax advice, nor does it constitute a recommendation or solicitation to buy or sell any security. Investors should consult with a qualified financial professional before making any investment decisions. Rebalancing and asset allocation strategies do not ensure a profit or protect against loss in declining markets. There is no guarantee that any investment strategy will achieve its objectives. Any references to historical performance, academic studies, or research are based on past data and should not be considered indicative of future results. Past performance is not a guarantee of future outcomes. Advisory services offered through Human Investing, an SEC-registered investment adviser.

Sources


Related Articles

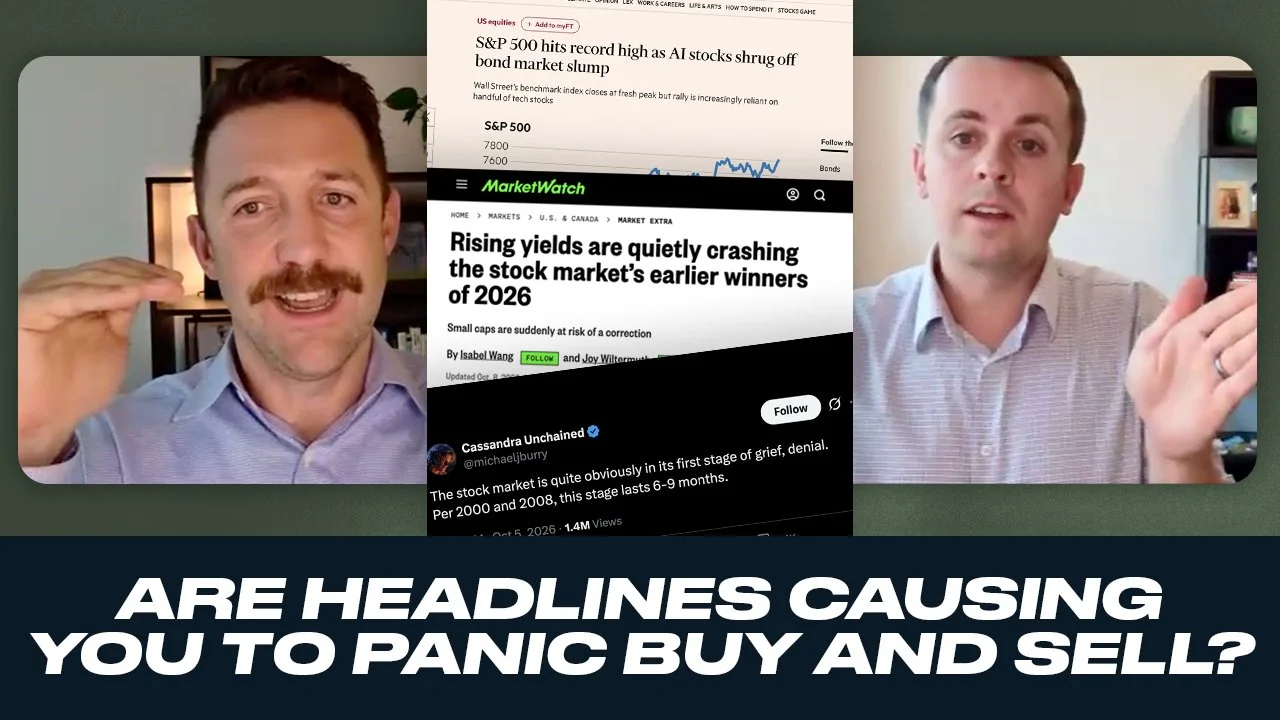
Hi Ground Episode 9: Headline Reactions; Plus 5 Year-End Financial Planning Moves To Make
 

E-mail us your questions, comments, and if you like our banter: higroundpodcast@gmail.com

Episode 9 show notes

Part 1: Headline Reactions

  • Herbert, Emily. “S&P 500 hits record high as AI stocks shrug off bond market slump” Financial Times, 6 October 2026 [Article]

  • Wang, Isabel and Wiltermuth, Joy. “Rising yields are quietly crashing the stock market’s earlier winners of 2026” Market Watch, 8 October 2026 [Article]

  • Fonda, Daren. “Here comes third-quarter earnings season. Booming profits could propel the S&P 500 to new heights” CNBC, 7 October 2026 [Article]

  • Confino, Paolo. “Michael Burry's Bearish View. The Market Is In 'Denial' About The End Of The AI Trade.” Investor’s Business Daily, 6 October 2026 [Article]

  • Detrick, Ryan [@RyanDetrick]. “When the S&P 500 is in the sweet spot going into Q4 (up YTD between 10% to 20%) the returns get even better. Higher 85% of the time in Q4 and up 5.3% on average.” X, 1 October, 2026 [Tweet]
  • Morningstar Mind the Gap US 2026 [Report]

Part 2: Bonds in Retirement Plans

  • Nelson, Andrew. “The Bond Market is Changing Retirement Math” Human Investing Journal, 6 October 2026 [Article]

Part 3: End of the Year Moves

Part 4: Local Recs

  • Dos Mundos, Newberg, Oregon [Link]

  • Mole Mole, Portland, Oregon [Link]


Disclosure:
This material is provided for informational and educational purposes only. It should not be construed as investment, legal, or tax advice, nor does it constitute a recommendation or solicitation to buy or sell any security. Investors should consult with a qualified financial professional before making any investment decisions. Rebalancing and asset allocation strategies do not ensure a profit or protect against loss in declining markets. There is no guarantee that any investment strategy will achieve its objectives. Any references to historical performance, academic studies, or research are based on past data and should not be considered indicative of future results. Past performance is not a guarantee of future outcomes. Advisory services offered through Human Investing, an SEC-registered investment adviser.


Related Articles

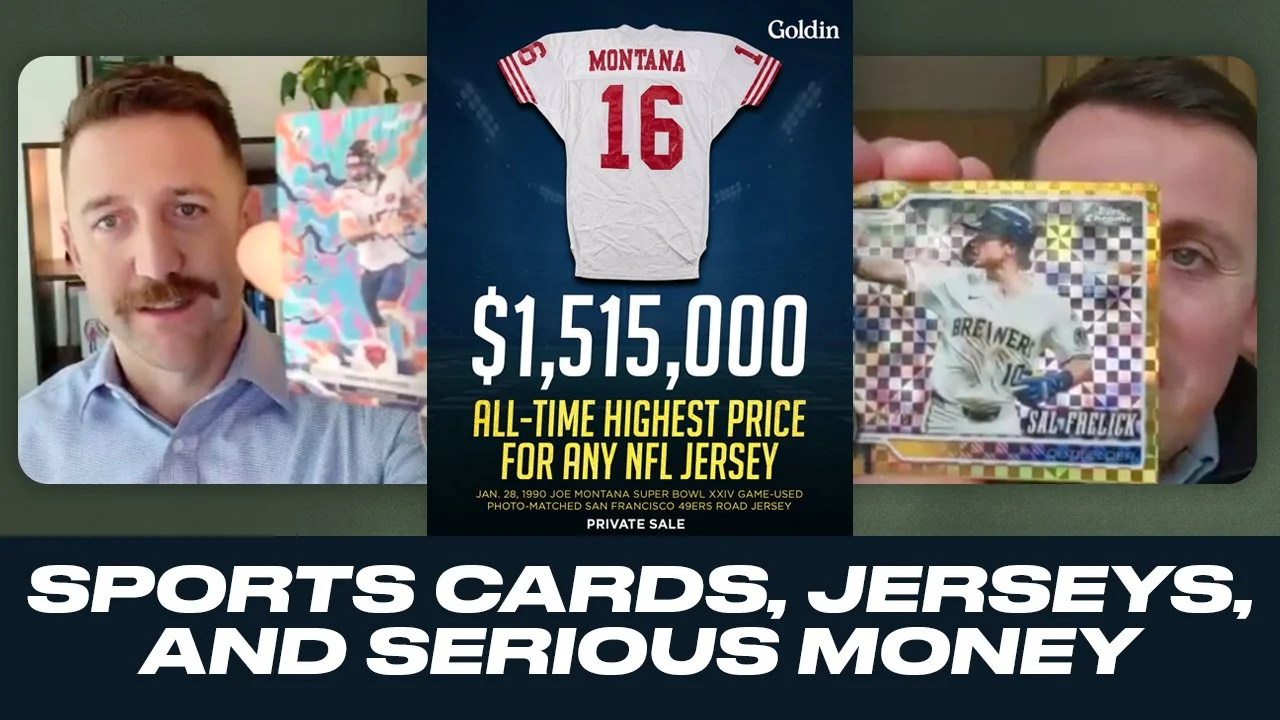
Hi Ground Episode 8: Sports Cards, Jerseys, and Serious Money
 

E-mail us your questions, comments, and your childhood attic finds: higroundpodcast@gmail.com

Episode 8 show notes

Part 1: Collectibles as an Asset Class

  • Post, J.J. “Joe Montana Super Bowl XXIV jersey fetches record price” ESPN, 13 August 2026 [Article]

  • Holder, Larry. “What’s working in the sports collectibles world: Industry leaders share what they’re seeing” The Athletic, 6 August 2026 [Article]

  • Burrows, Benjamin. “CardVault by Tom Brady adds investors including Aaron Judge, Jay-Z, Connor McDavid” The Athletic, 13 August 2026 [Article]

Part 2: Local Real Estate Updates

  • U.S. Bank. U.S. Bank 2026 Wealth Report, 2026 [Report]


Part 3: Local Recs

  • The Alley Cards and Collectibles, Lake Oswego, Oregon [Link]

  • E.Z. Orchards, Salem, Oregon [Link]


Disclosure:
This material is provided for informational and educational purposes only. It should not be construed as investment, legal, or tax advice, nor does it constitute a recommendation or solicitation to buy or sell any security. Investors should consult with a qualified financial professional before making any investment decisions. Rebalancing and asset allocation strategies do not ensure a profit or protect against loss in declining markets. There is no guarantee that any investment strategy will achieve its objectives. Any references to historical performance, academic studies, or research are based on past data and should not be considered indicative of future results. Past performance is not a guarantee of future outcomes. Advisory services offered through Human Investing, an SEC-registered investment adviser.


Related Articles

Hi Ground Episode 7: Gen-Z's Retirement Plan? Place Your Bets
 

E-mail us your questions, comments, and bad sports bet breaks: higroundpodcast@gmail.com

Episode 7 show notes

Part 1: Sports Betting Rush

  • Song, Zijia and Amponsah, Michelle. “Gen Z Is Moving Money From Stocks to Sports Betting in Wealth Plans” Bloomberg, 12 August 2026 [Article]

  • Bloomberg Originals. “Why Gen Z Is Gambling With Its Future” YouTube, uploaded by Bloomberg Originals, 10 July 2026 [Video]

  • Northwestern Mutual. “Planning & Progress Study 2026” Northwestern Mutual, 2026 [Report]


Part 2: Becoming a 401(k) Millionaire

  • Picchi, Aimee. “Sturdy stock market mints a record number of 401(k) millionaires” CBS News, 4 September 2026 [Article]

  • Fuhrmans, Vanessa. “American Workers Are Staying Put” Wall Street Journal, 9 September 2026 [Article]

  • Human Investing Retirement Contribution by Decade Calculator [Link]

  • Becoming a 401(K) Millionaire by Peter Fisher [Link]


Part 3: Local Recs

  • Swan Island Dahlias in Canby, OR [Link]

  • Hood to Coast Relay [Link]


Disclosure:
This material is provided for informational and educational purposes only. It should not be construed as investment, legal, or tax advice, nor does it constitute a recommendation or solicitation to buy or sell any security. Investors should consult with a qualified financial professional before making any investment decisions. Rebalancing and asset allocation strategies do not ensure a profit or protect against loss in declining markets. There is no guarantee that any investment strategy will achieve its objectives. Any references to historical performance, academic studies, or research are based on past data and should not be considered indicative of future results. Past performance is not a guarantee of future outcomes. Advisory services offered through Human Investing, an SEC-registered investment adviser.


Related Articles

Hi Ground Episode 6: Time to Nerd Out. Bonds Are Having A Moment
 

E-mail us your questions, comments, and if you have a blue polo too: higroundpodcast@gmail.com

Episode 6 show notes

Part 1: Why Are Bonds Acting Up?

  • Goldfarb, Sam and Rubin, Richard. “Bonds Are Getting Hammered, and Wall Street Says the Rout Won’t End Anytime Soon” Wall Street Journal, 18 August 2026 [Article]

Part 2: Where Do Bonds Fit?

  • Kellar, Will. “Managing Your Finances With The Three Bucket Approach” Human Investing Journal, 10 June 2025 [Article]


Part 3: Parking ‘Safe’ Dollars

  • Gottfried, Miriam. “Wealth Management Has a $3 Trillion Problem: Investors Are Keeping Too Much Cash” Wall Street Journal, 12 August 2026 [Article]

 
  • Damodaran, Aswath. “Historical Returns on Stocks, Bonds, Real Estate and Gold.” Stern School of Business at New York University. 1 August 2026. [Database]

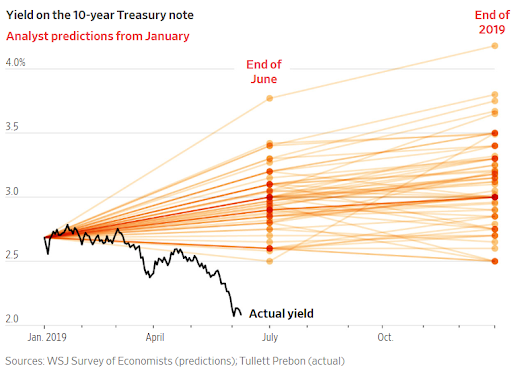
  • Chilkoti, Avantika and Kruger, Daniel. “Some Investors Had Hunch Yields Were About to Fall” Wall Street Journall, 9 June 2019 [Article]


Part 4: Local Recs

  • Portland Annual Swift Watch [Link]

  • LPGA The Standard Classic [Link]


Disclosure:
This material is provided for informational and educational purposes only. It should not be construed as investment, legal, or tax advice, nor does it constitute a recommendation or solicitation to buy or sell any security. Investors should consult with a qualified financial professional before making any investment decisions. Rebalancing and asset allocation strategies do not ensure a profit or protect against loss in declining markets. There is no guarantee that any investment strategy will achieve its objectives. Any references to historical performance, academic studies, or research are based on past data and should not be considered indicative of future results. Past performance is not a guarantee of future outcomes. Advisory services offered through Human Investing, an SEC-registered investment adviser.


Related Articles

Hi Ground Episode 5: The Economy, Staying Balanced, and Hot Dogs?
 

E-mail us your questions, comments, and hot dog stories: higroundpodcast@gmail.com

Episode 5 show notes

Part 1: The Economy vs. Stock Market

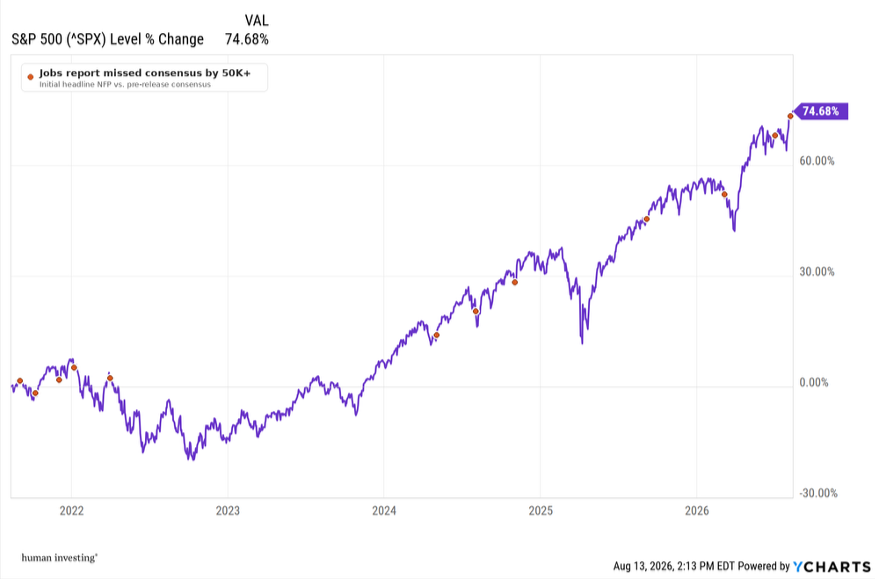
  • Heard on the Streets Staff. “Markets Rally on Surprise U.S. Job Losses” Wall Street Journal, 7 August 2026 [Article]

  • Mutikani, Lucia. “US suffers unexpected job losses in July, markets dial back rate hike expectations” Reuters, 7 August 2026 [Article]

  • Michael Burry 2023 “Sell” [Link]

  • Chart: S&P 500 % Change Over Previous 5-years


Part 2: $100 Hot Dogs & Investing Behavior

  • Chandler, Adam. “The Rise of the $100 Hot Dog” Wall Street Journal, 8 August 2026 [Article]

  • Lake, Sydney. “Costco CEO promises the $1.50 hot dog isn’t going away: The price will not change as long as I’m around” Fortune, 4 July 2026 [Article]

  • Understanding ERISA Diversification [Link]

  • “The Real Cost of Your Morning Coffee” Human Investing, 22 May 2015 [Article]

Part 3: Local Recs

  • Hot Mama Salsa Tortilla Chips [Link]

  • Farmer Johns Produce & Nursery, McMinnville OR [Link]


Disclosure:
This material is provided for informational and educational purposes only. It should not be construed as investment, legal, or tax advice, nor does it constitute a recommendation or solicitation to buy or sell any security. Investors should consult with a qualified financial professional before making any investment decisions. Rebalancing and asset allocation strategies do not ensure a profit or protect against loss in declining markets. There is no guarantee that any investment strategy will achieve its objectives. Any references to historical performance, academic studies, or research are based on past data and should not be considered indicative of future results. Past performance is not a guarantee of future outcomes. Advisory services offered through Human Investing, an SEC-registered investment adviser.


Related Articles

Quarterly Economic Update: The Market Beneath the Market
 

If you had told me at the beginning of the year that the seven largest companies would underperform, inflation would remain stubborn, tariffs would add pressure to prices, another interest-rate hike would become a real possibility, and conflict would disrupt shipping through the Strait of Hormuz, I would have guessed the stock market would be down. 

That would have been a reasonable guess….it also would have been wrong. 

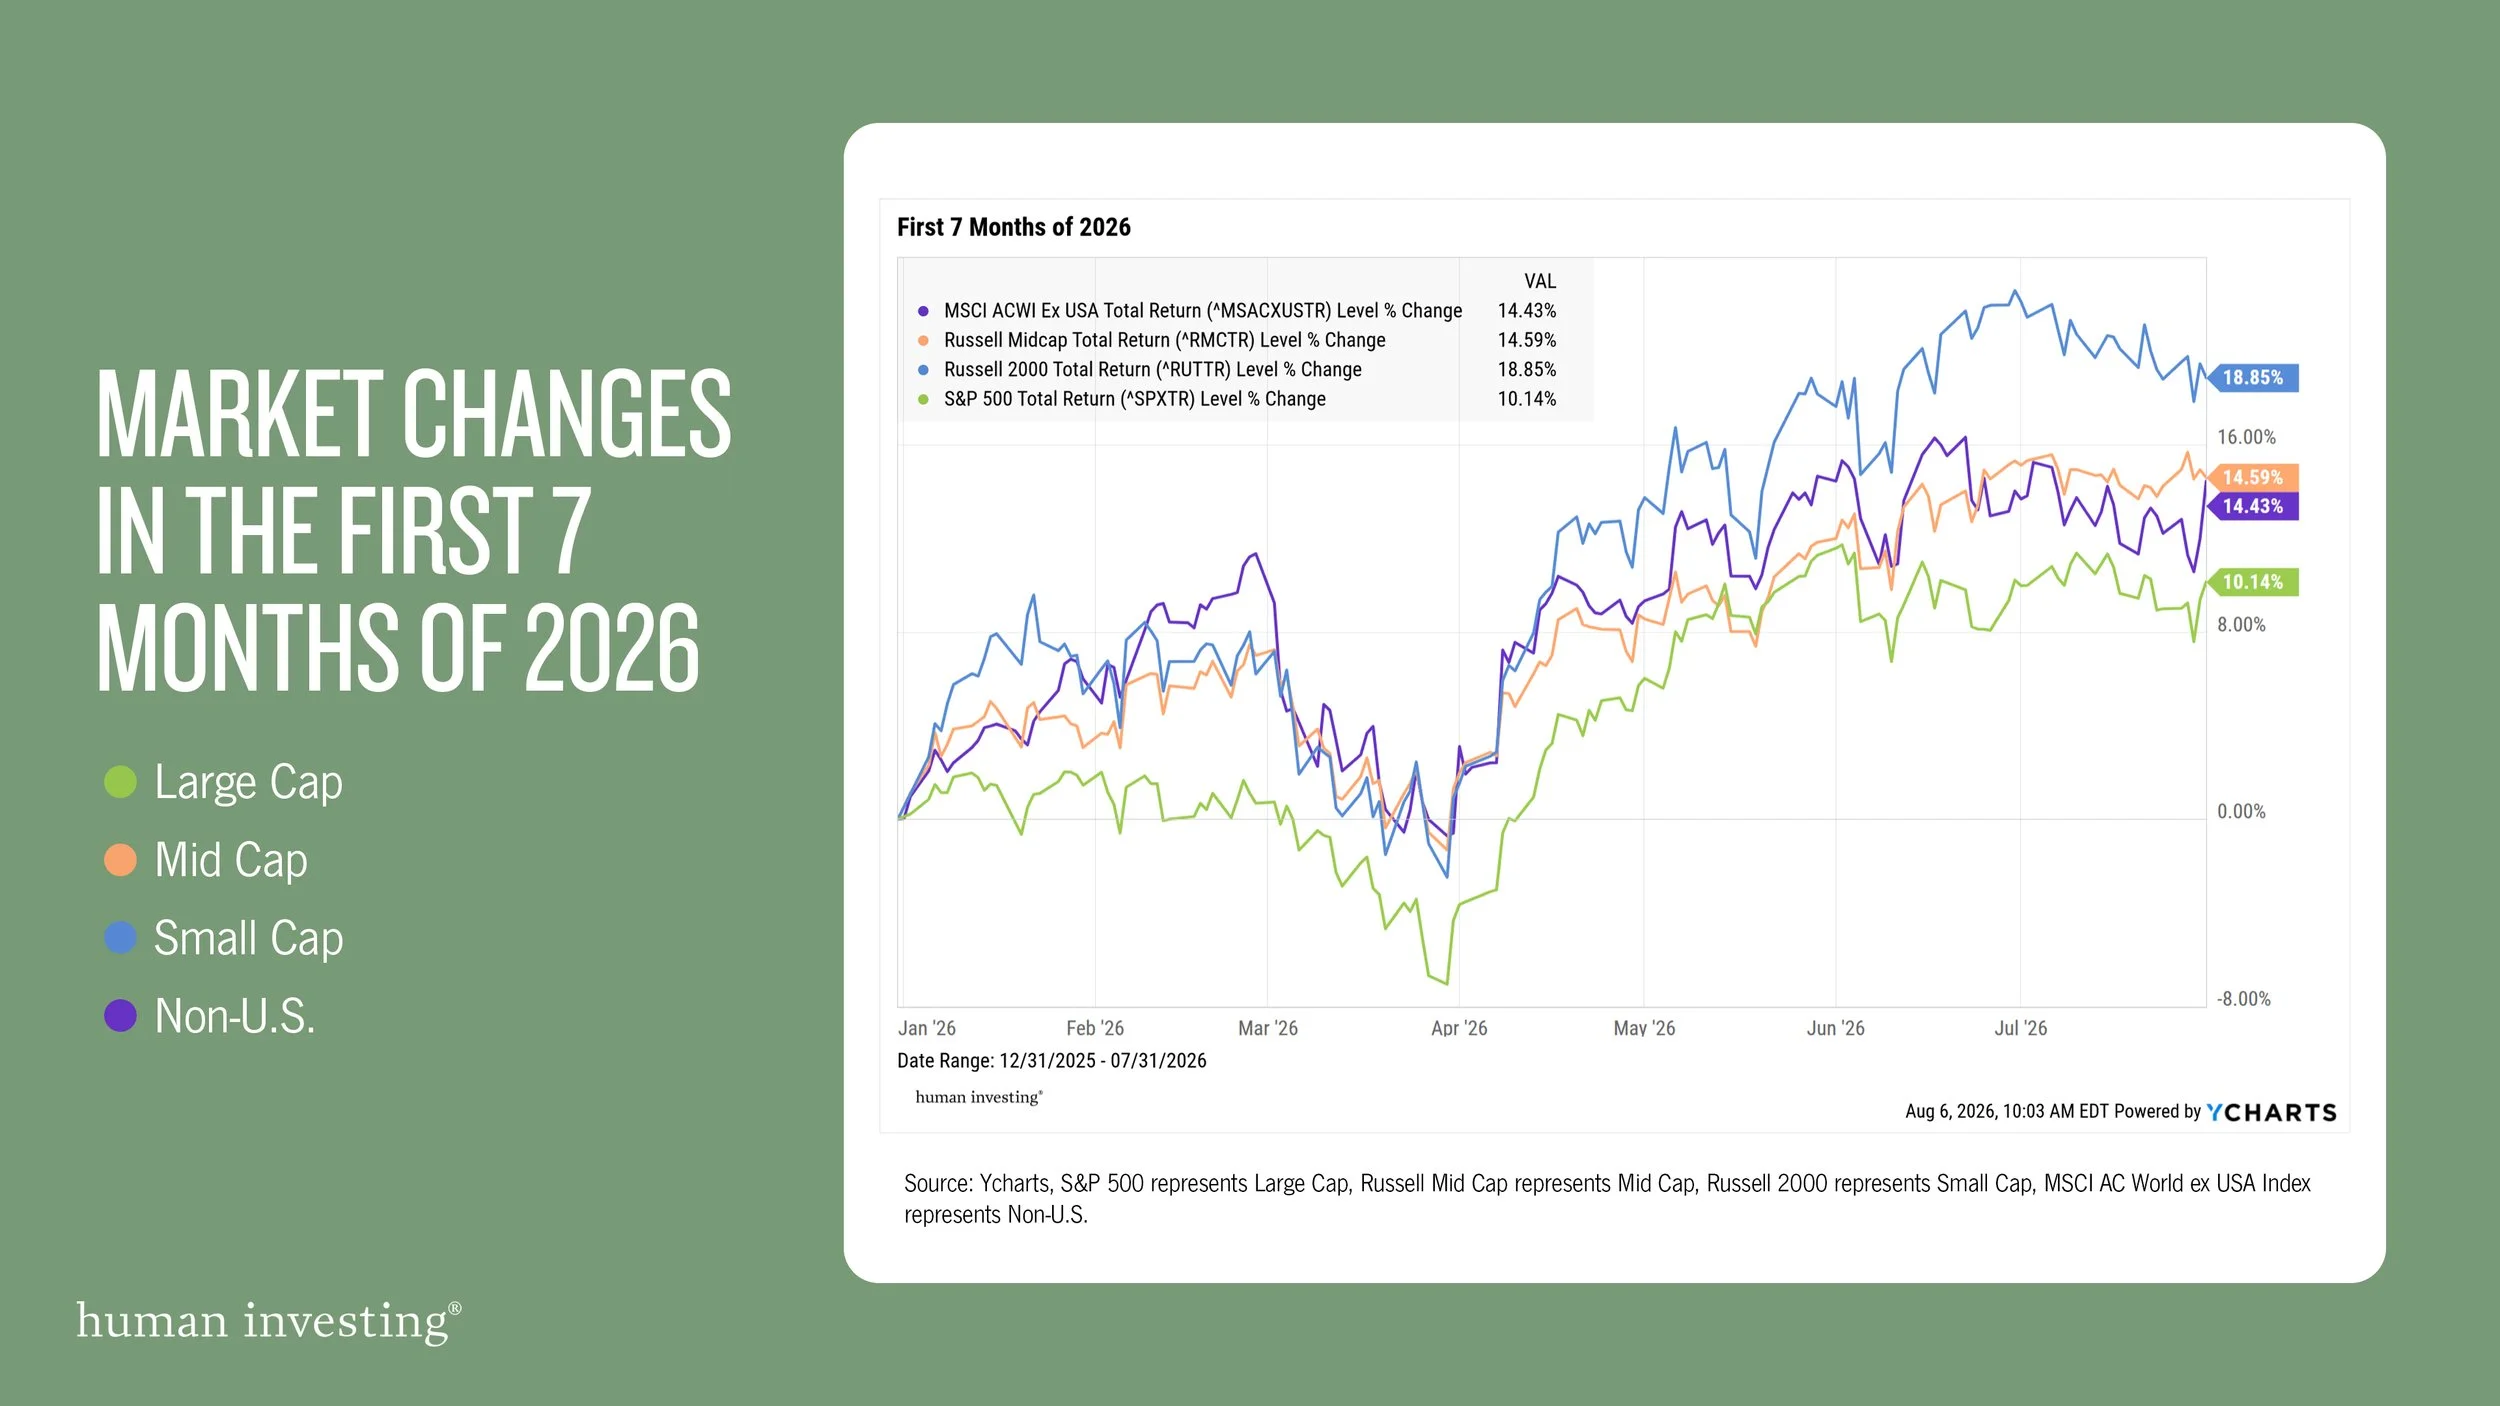
Through July, the S&P 500 has gained roughly 10% including dividends, despite an economic backdrop that seemed to hint otherwise. It’s a reminder that the future rarely unfolds exactly as we think it will. Markets have a way of surprising both optimists and pessimists.  

That brings us to one of the more interesting stories unfolding beneath the surface this year. 

A Different Kind of Market 

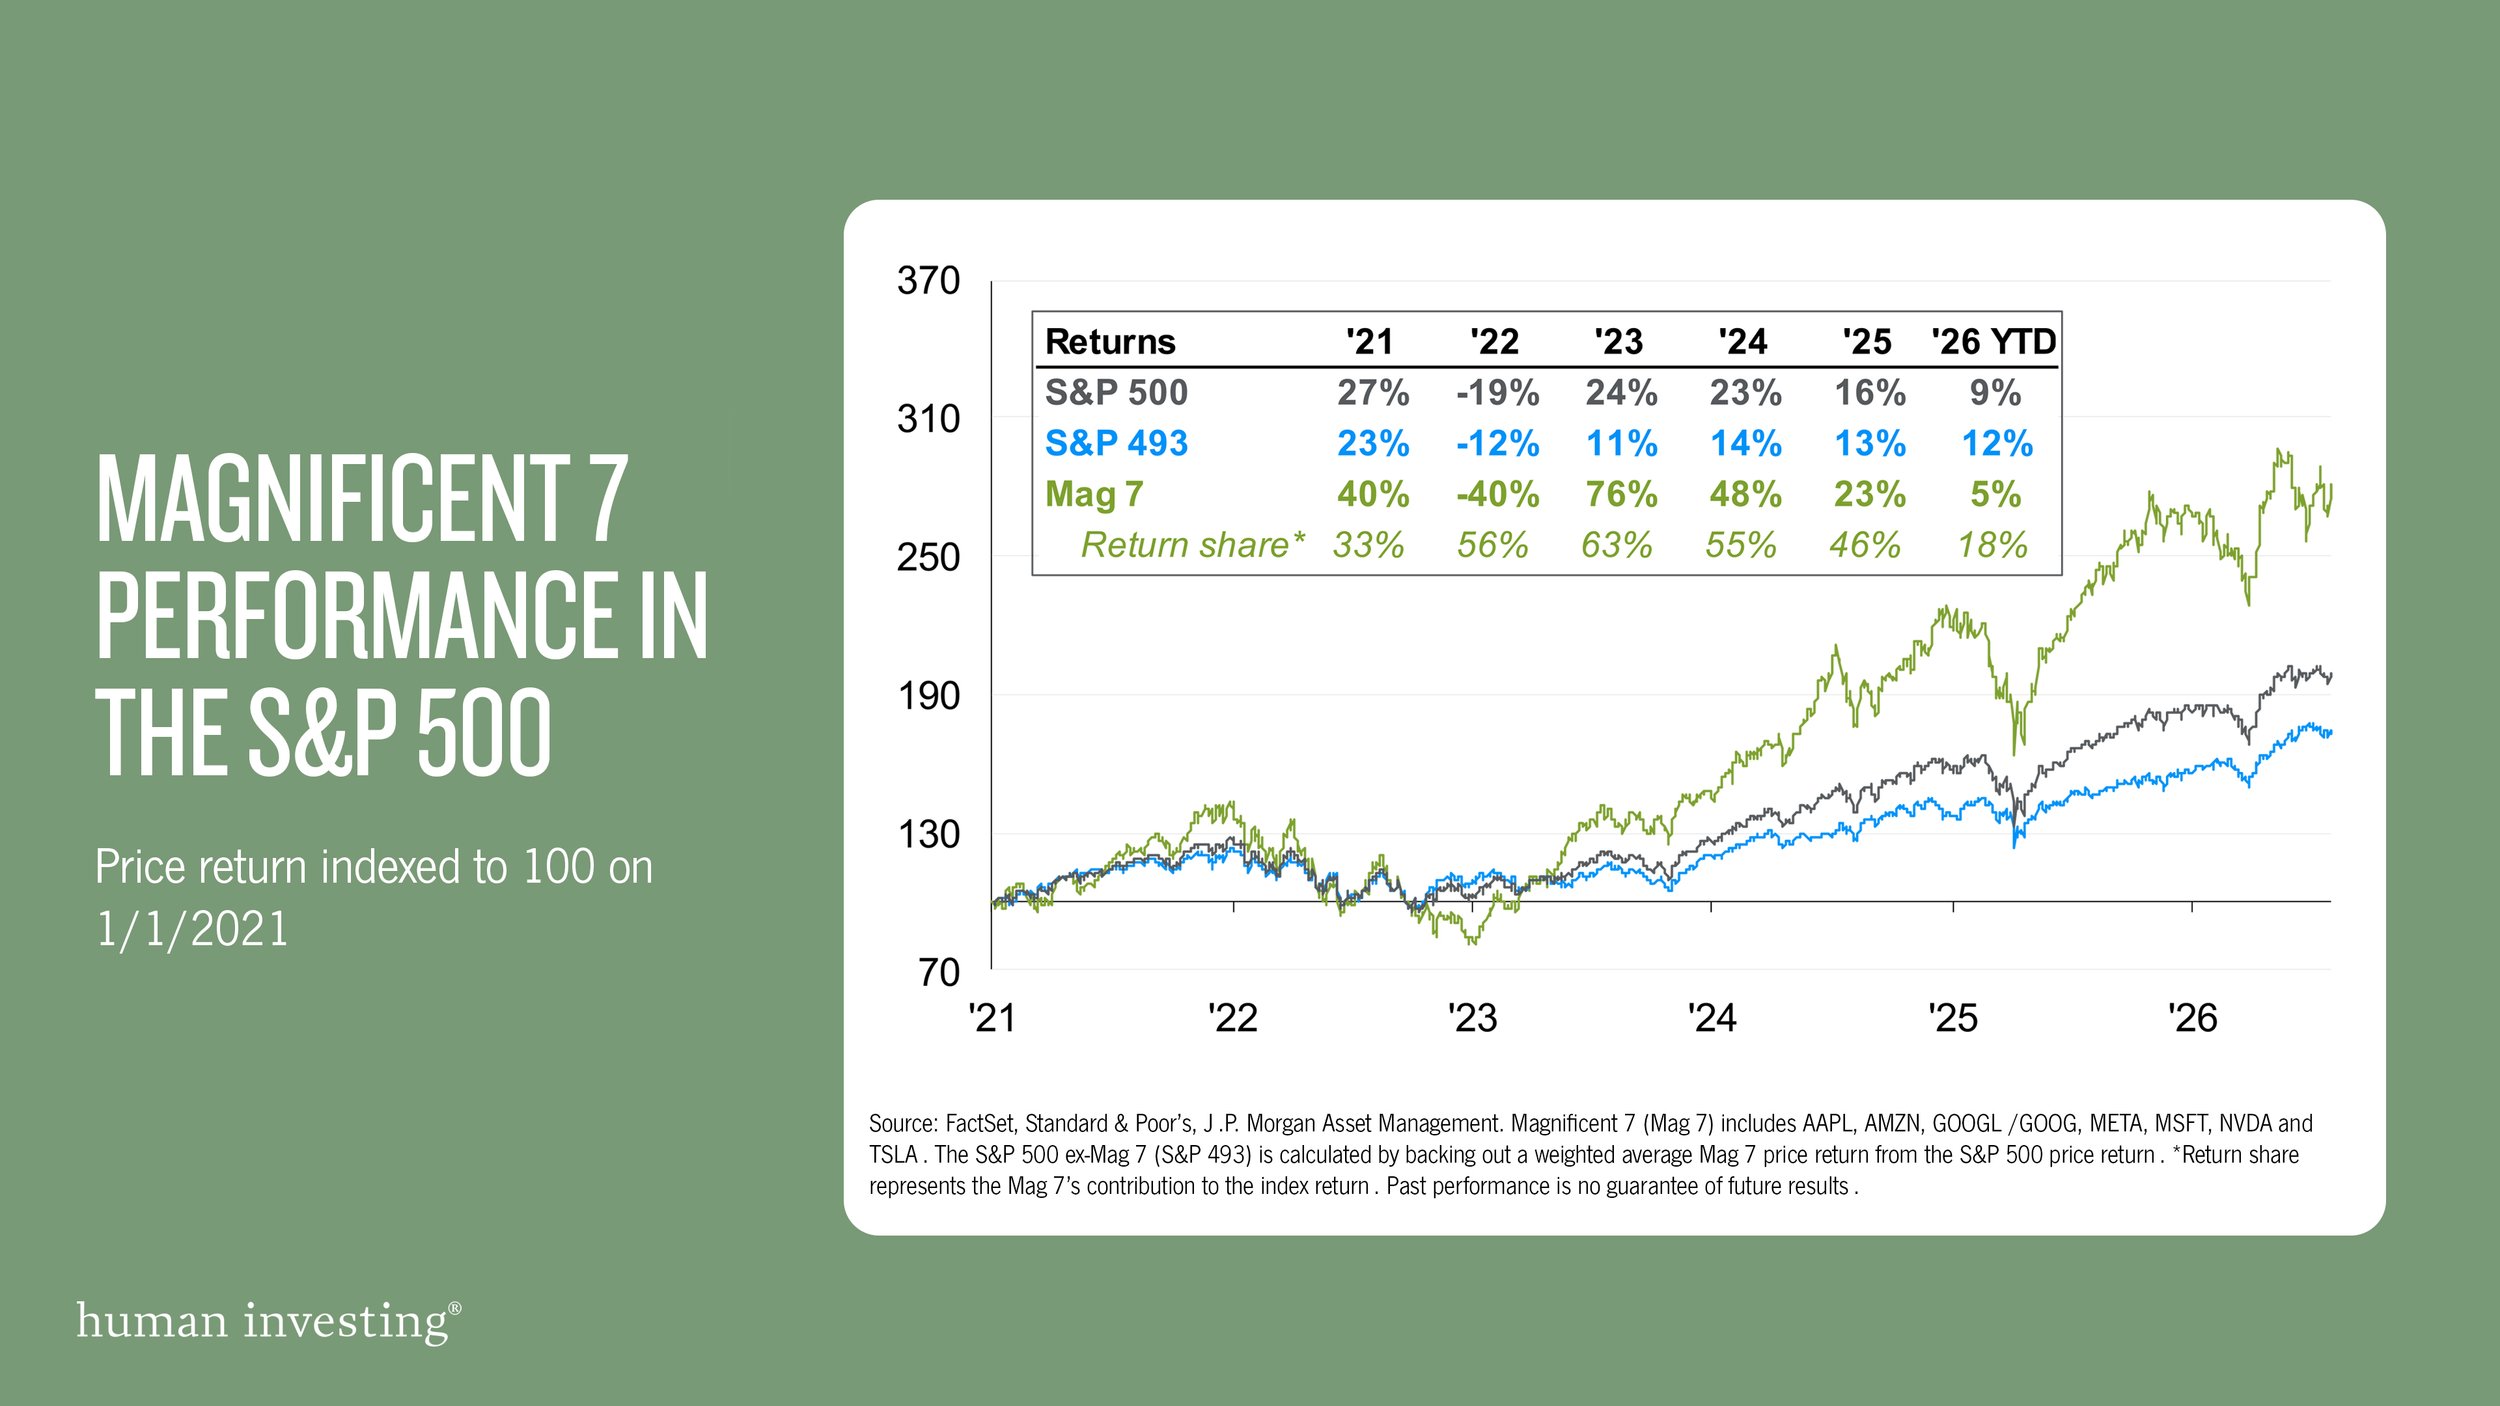
For the past several years, the story of the U.S. stock market was largely the story of seven companies: NVIDIA, Apple, Microsoft, Amazon, Alphabet, Meta, and Tesla. Together, they are often referred to as the “Magnificent Seven,” or simply the “Mag 7.” 

In 2023, the Magnificent Seven gained approximately 76%, while the remaining 493 companies in the S&P 500 returned roughly 11%. In 2024, the Mag 7 gained another 48%, compared with approximately 14% for the rest of the index. 

Compounded over those two years, the Magnificent Seven appreciated roughly 160%, while the remaining 493 companies of the S&P 500 gained about 27%.

These returns were supported by business success. The companies delivered impressive earnings, benefited from the excitement surrounding artificial intelligence, and established themselves as leaders in some of the world’s most important industries. As a result, this relatively small group accounted for a significant share of the market’s gains.  

This year, something important has changed. The market has continued to move higher, but this time the gains have come from a much wider range of companies. Smaller companies generally have outperformed large companies, and international markets have outperformed large companies in the US. 

The market has continued to move forward, but it hasn’t needed the same seven companies to carry it. 

Why Broader Participation Matters 

A market supported by more companies is generally healthier than one carried by only a handful of names. Broader participation means the market is less dependent on the ongoing success of the same companies. 

One of the interesting realities of investing is that a great business doesn't always make a great investment. A company can continue growing while its stock underperforms simply because expectations have already become so high. 

The Magnificent Seven did not suddenly become seven bad businesses. They entered the year carrying high expectations, large positions within the index, and several years of extraordinary performance. Meanwhile, many other parts of the market entered the year with lower valuations and less enthusiasm. 

As investors began finding opportunities elsewhere, market leadership broadened. This shift is a normal part of how markets work. 

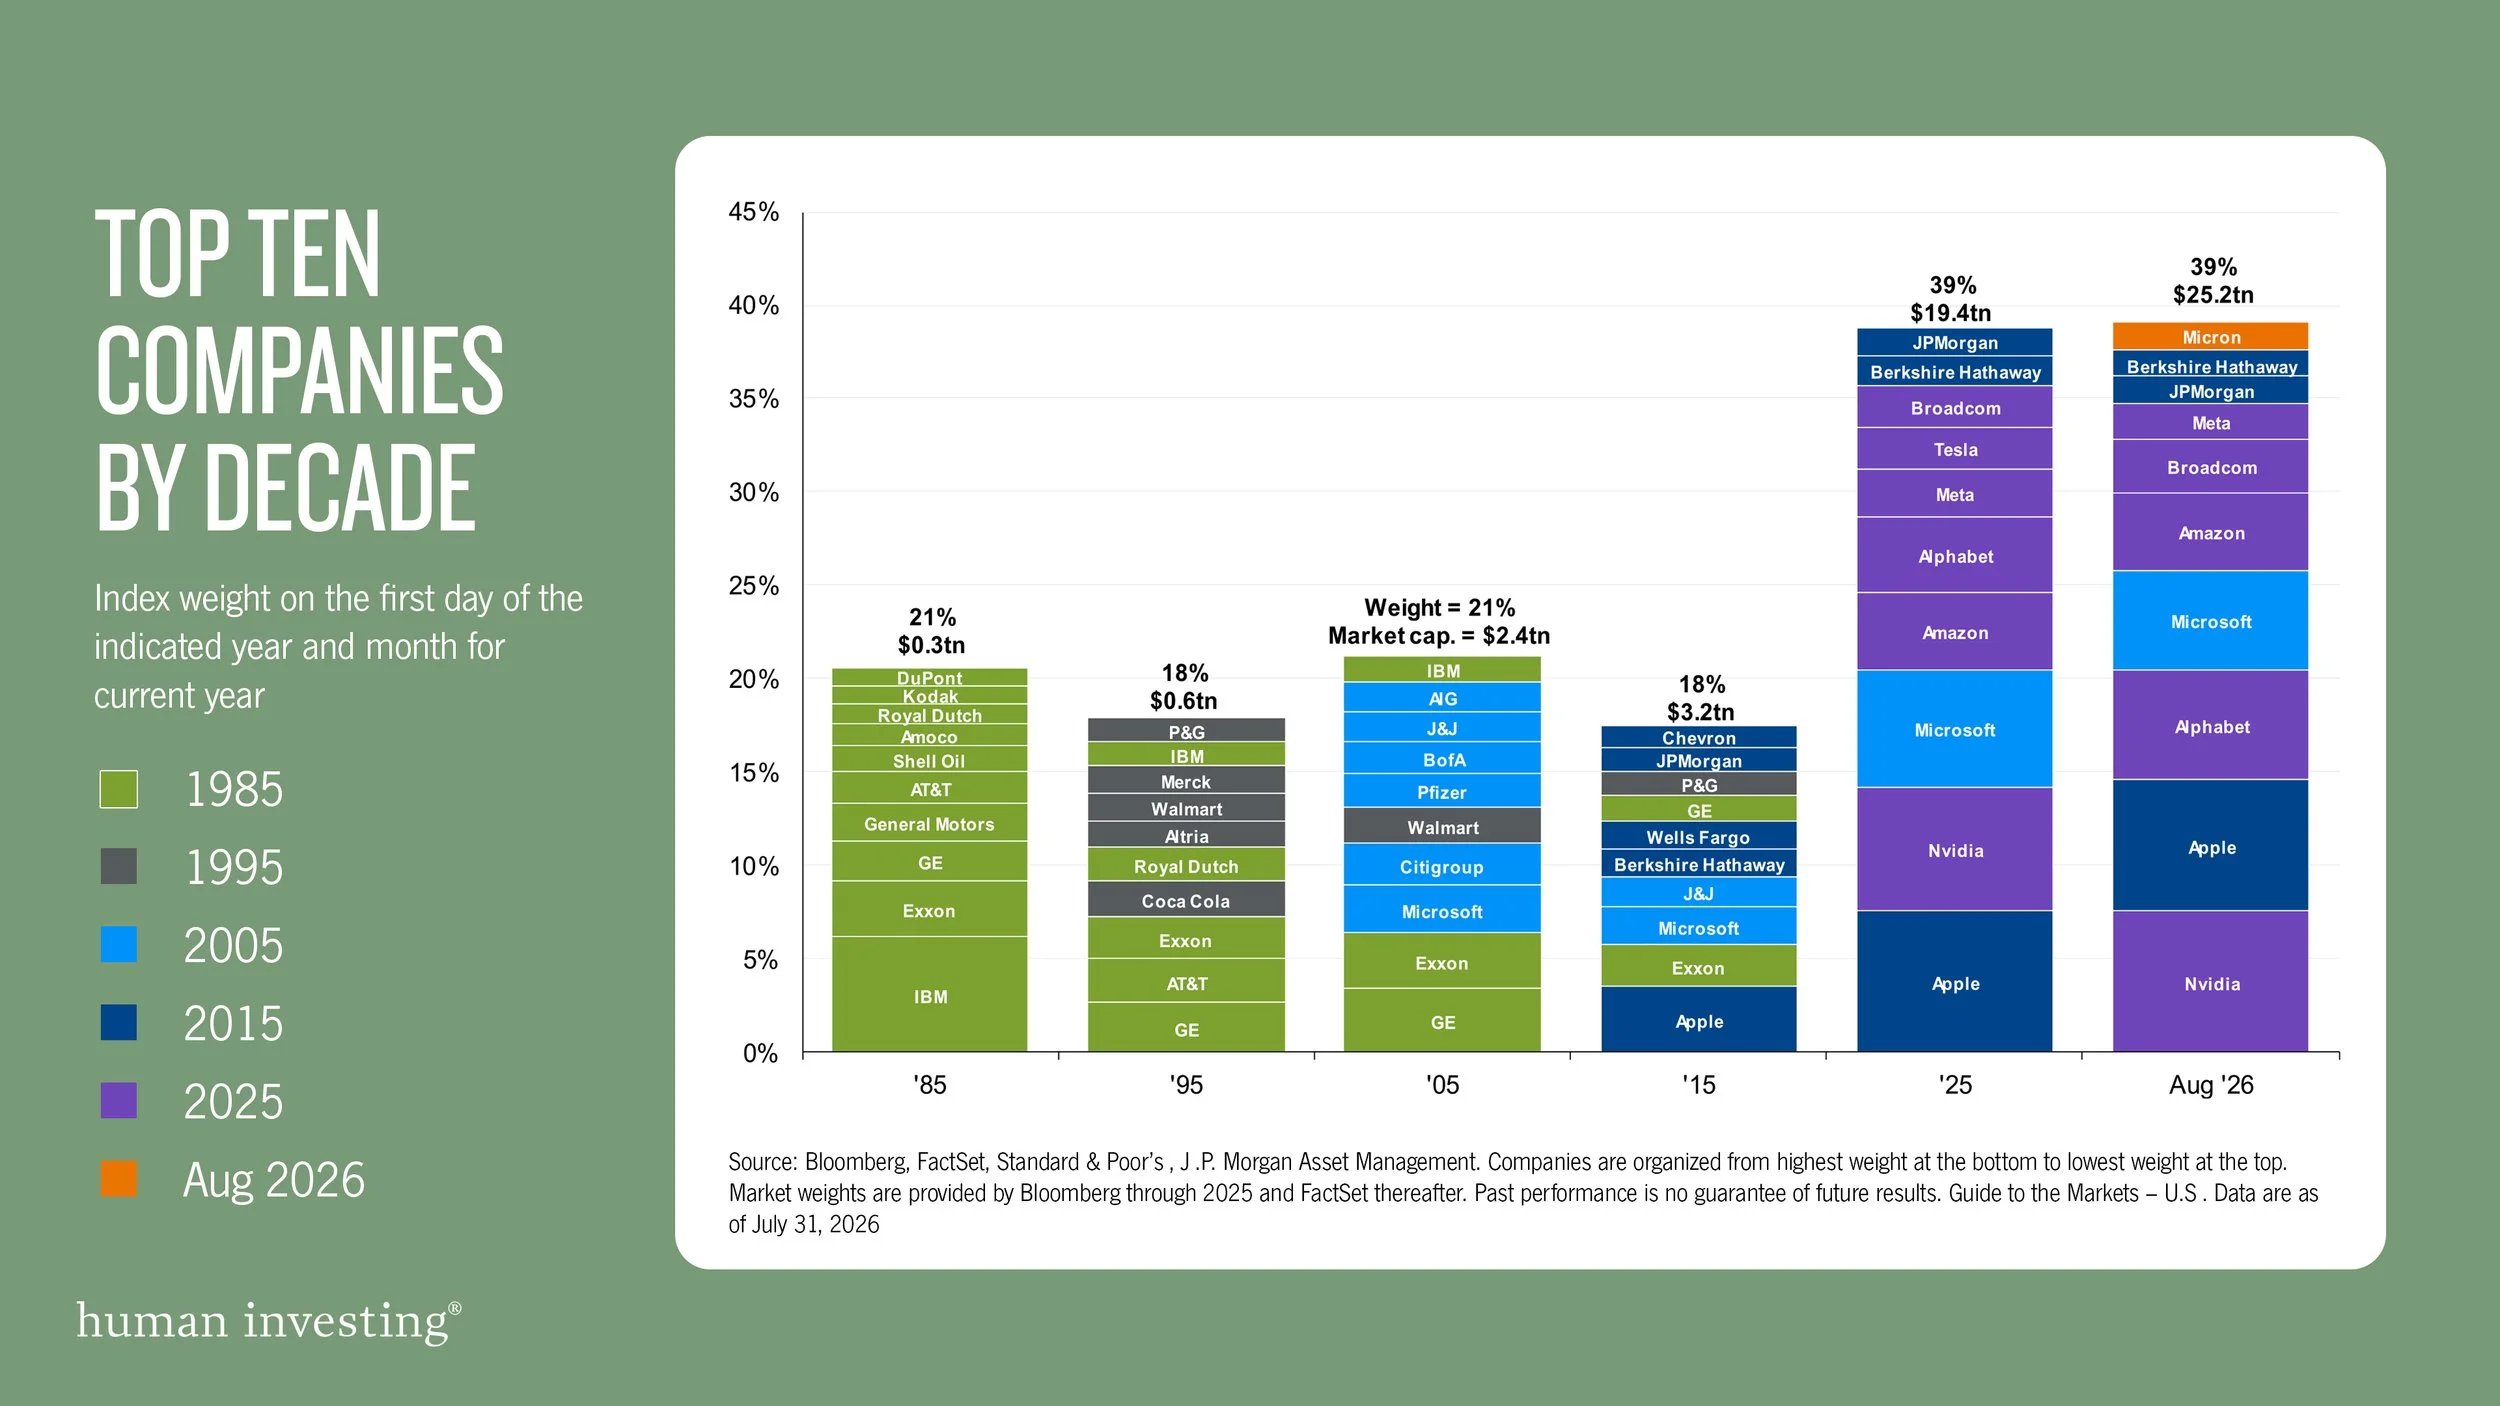
J.P. Morgan’s historical review of the ten largest companies in the S&P 500 shows how market leadership has changed across decades. The companies dominating the index in 1985 looked very different from those leading in 2005, 2015, or 2025. Some remained successful businesses for decades. Very few remained the market’s dominant investment leaders.   

The lesson is not that today’s largest companies are destined to fail. History simply gives us little reason to assume that the same group will lead forever. 

Seasons like this are where diversification proves its value 

When large technology companies lead the market for several years, it can begin to feel as though they are the only investments that matter. International stocks, smaller companies, and other parts of the market may receive far less attention. Then leadership quickly changes, often when few investors expect it. 

Diversification acknowledges that none of us knows exactly how the future will unfold. Rather than trying to predict the next winning sector, company, or country, it allows investors to participate in market growth as a whole. The result is a portfolio that is less dependent on any single outcome and better prepared for a range of possible futures. 

The Portfolio Serves the Plan

One of the reasons we spend so much time building a financial plan before building an investment portfolio is because the plan defines what success actually looks like. 

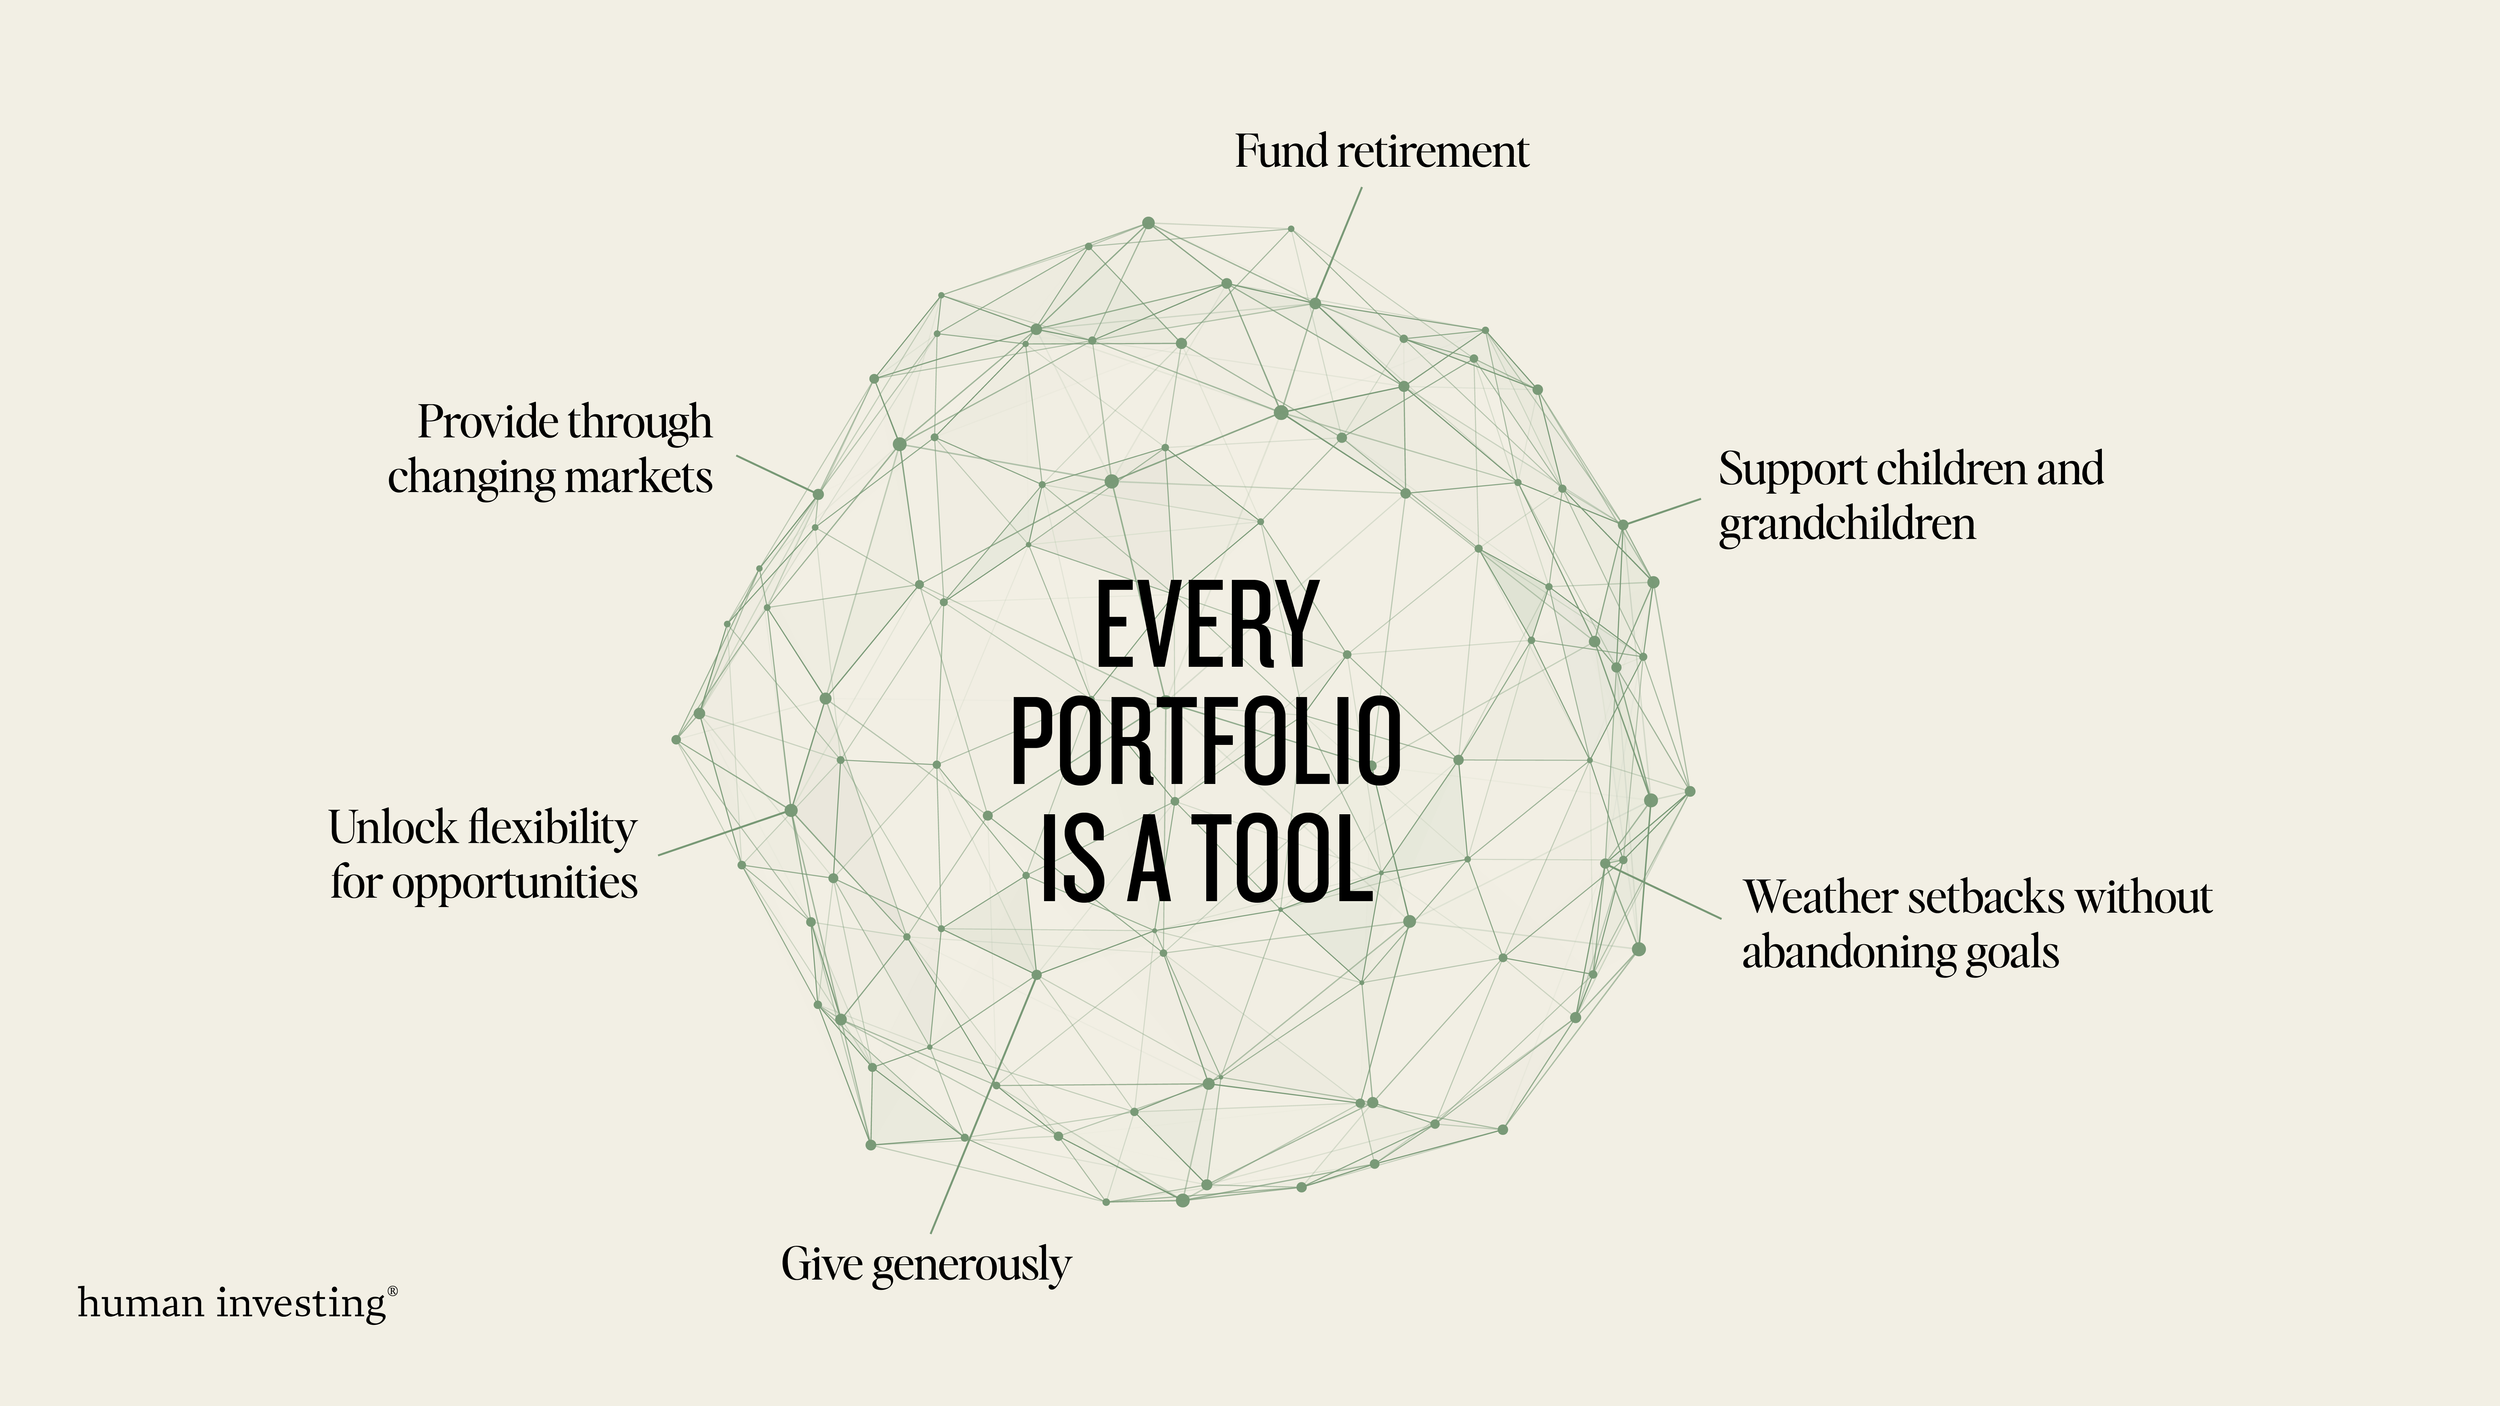
The portfolio then becomes a tool to support that plan. Its purpose may be: 

  • To fund retirement. 

  • To provide confidence that spending can continue through changing markets. 

  • To create flexibility for opportunities that arise unexpectedly. 

  • To support children and grandchildren. 

  • To give generously. 

  • To weather setbacks without having to abandon long-term goals. 

When a portfolio is anchored to a thoughtful financial plan, it becomes easier to stomach periods of change. There is less need to chase whatever happens to be performing best because the portfolio was never built around a single prediction in the first place. 

Instead, we ask a different question: Does this portfolio continue to provide a high probability of accomplishing the goals that matter most? 

That perspective doesn't eliminate uncertainty. It simply helps us respond to uncertainty with patience rather than reaction. 

Built for Uncertainty

None of this means the risks have disappeared. Markets will almost certainly face new challenges that we cannot anticipate today, and periods of volatility are inevitable. 

But this year has offered an important reminder: the market often does its best work while investors are focused on reasons it shouldn't. 

While leadership changes, narratives change, and headlines change, the importance of your goals does not. 

That is why we continue to believe in thoughtful financial planning, broad diversification, tax-wise investing, and the discipline to stay focused on what matters most. 

The objective has never been to predict every twist in the market. It is to build a financial plan and portfolio that can succeed through many different kinds of markets. 

At the beginning of the year, many investors would have predicted a very different outcome than the one we've experienced. 

We cannot know which companies, sectors, or countries will lead next… fortunately, we do not have to.


Disclosure:
This material is provided for informational and educational purposes only. It should not be construed as investment, legal, or tax advice, nor does it constitute a recommendation or solicitation to buy or sell any security. Investors should consult with a qualified financial professional before making any investment decisions. Rebalancing and asset allocation strategies do not ensure a profit or protect against loss in declining markets. There is no guarantee that any investment strategy will achieve its objectives. Any references to historical performance, academic studies, or research are based on past data and should not be considered indicative of future results. Past performance is not a guarantee of future outcomes. Advisory services offered through Human Investing, an SEC-registered investment adviser.


Related Articles

Hi Ground Episode 4: The Chase, The Crash, & Investing Sirens
 

E-mail us your questions, comments, and investing sirens: higroundpodcast@gmail.com

Episode 4 show notes

Part 1: The Allure of the Gamble

  • “'I couldn't breathe': South Korea's frenzied stock trading exposes margin loan risks.” Reuters, 19 July 2026 [Article]

  • The Frame by Samsung [Link]

  • Thaler, Richard. Johnson, Eric. “Gambling With the House Money and Trying to Break Even: The Effects of Prior Outcomes on Risky Choice.” Research Gate, June 1990 [Article]

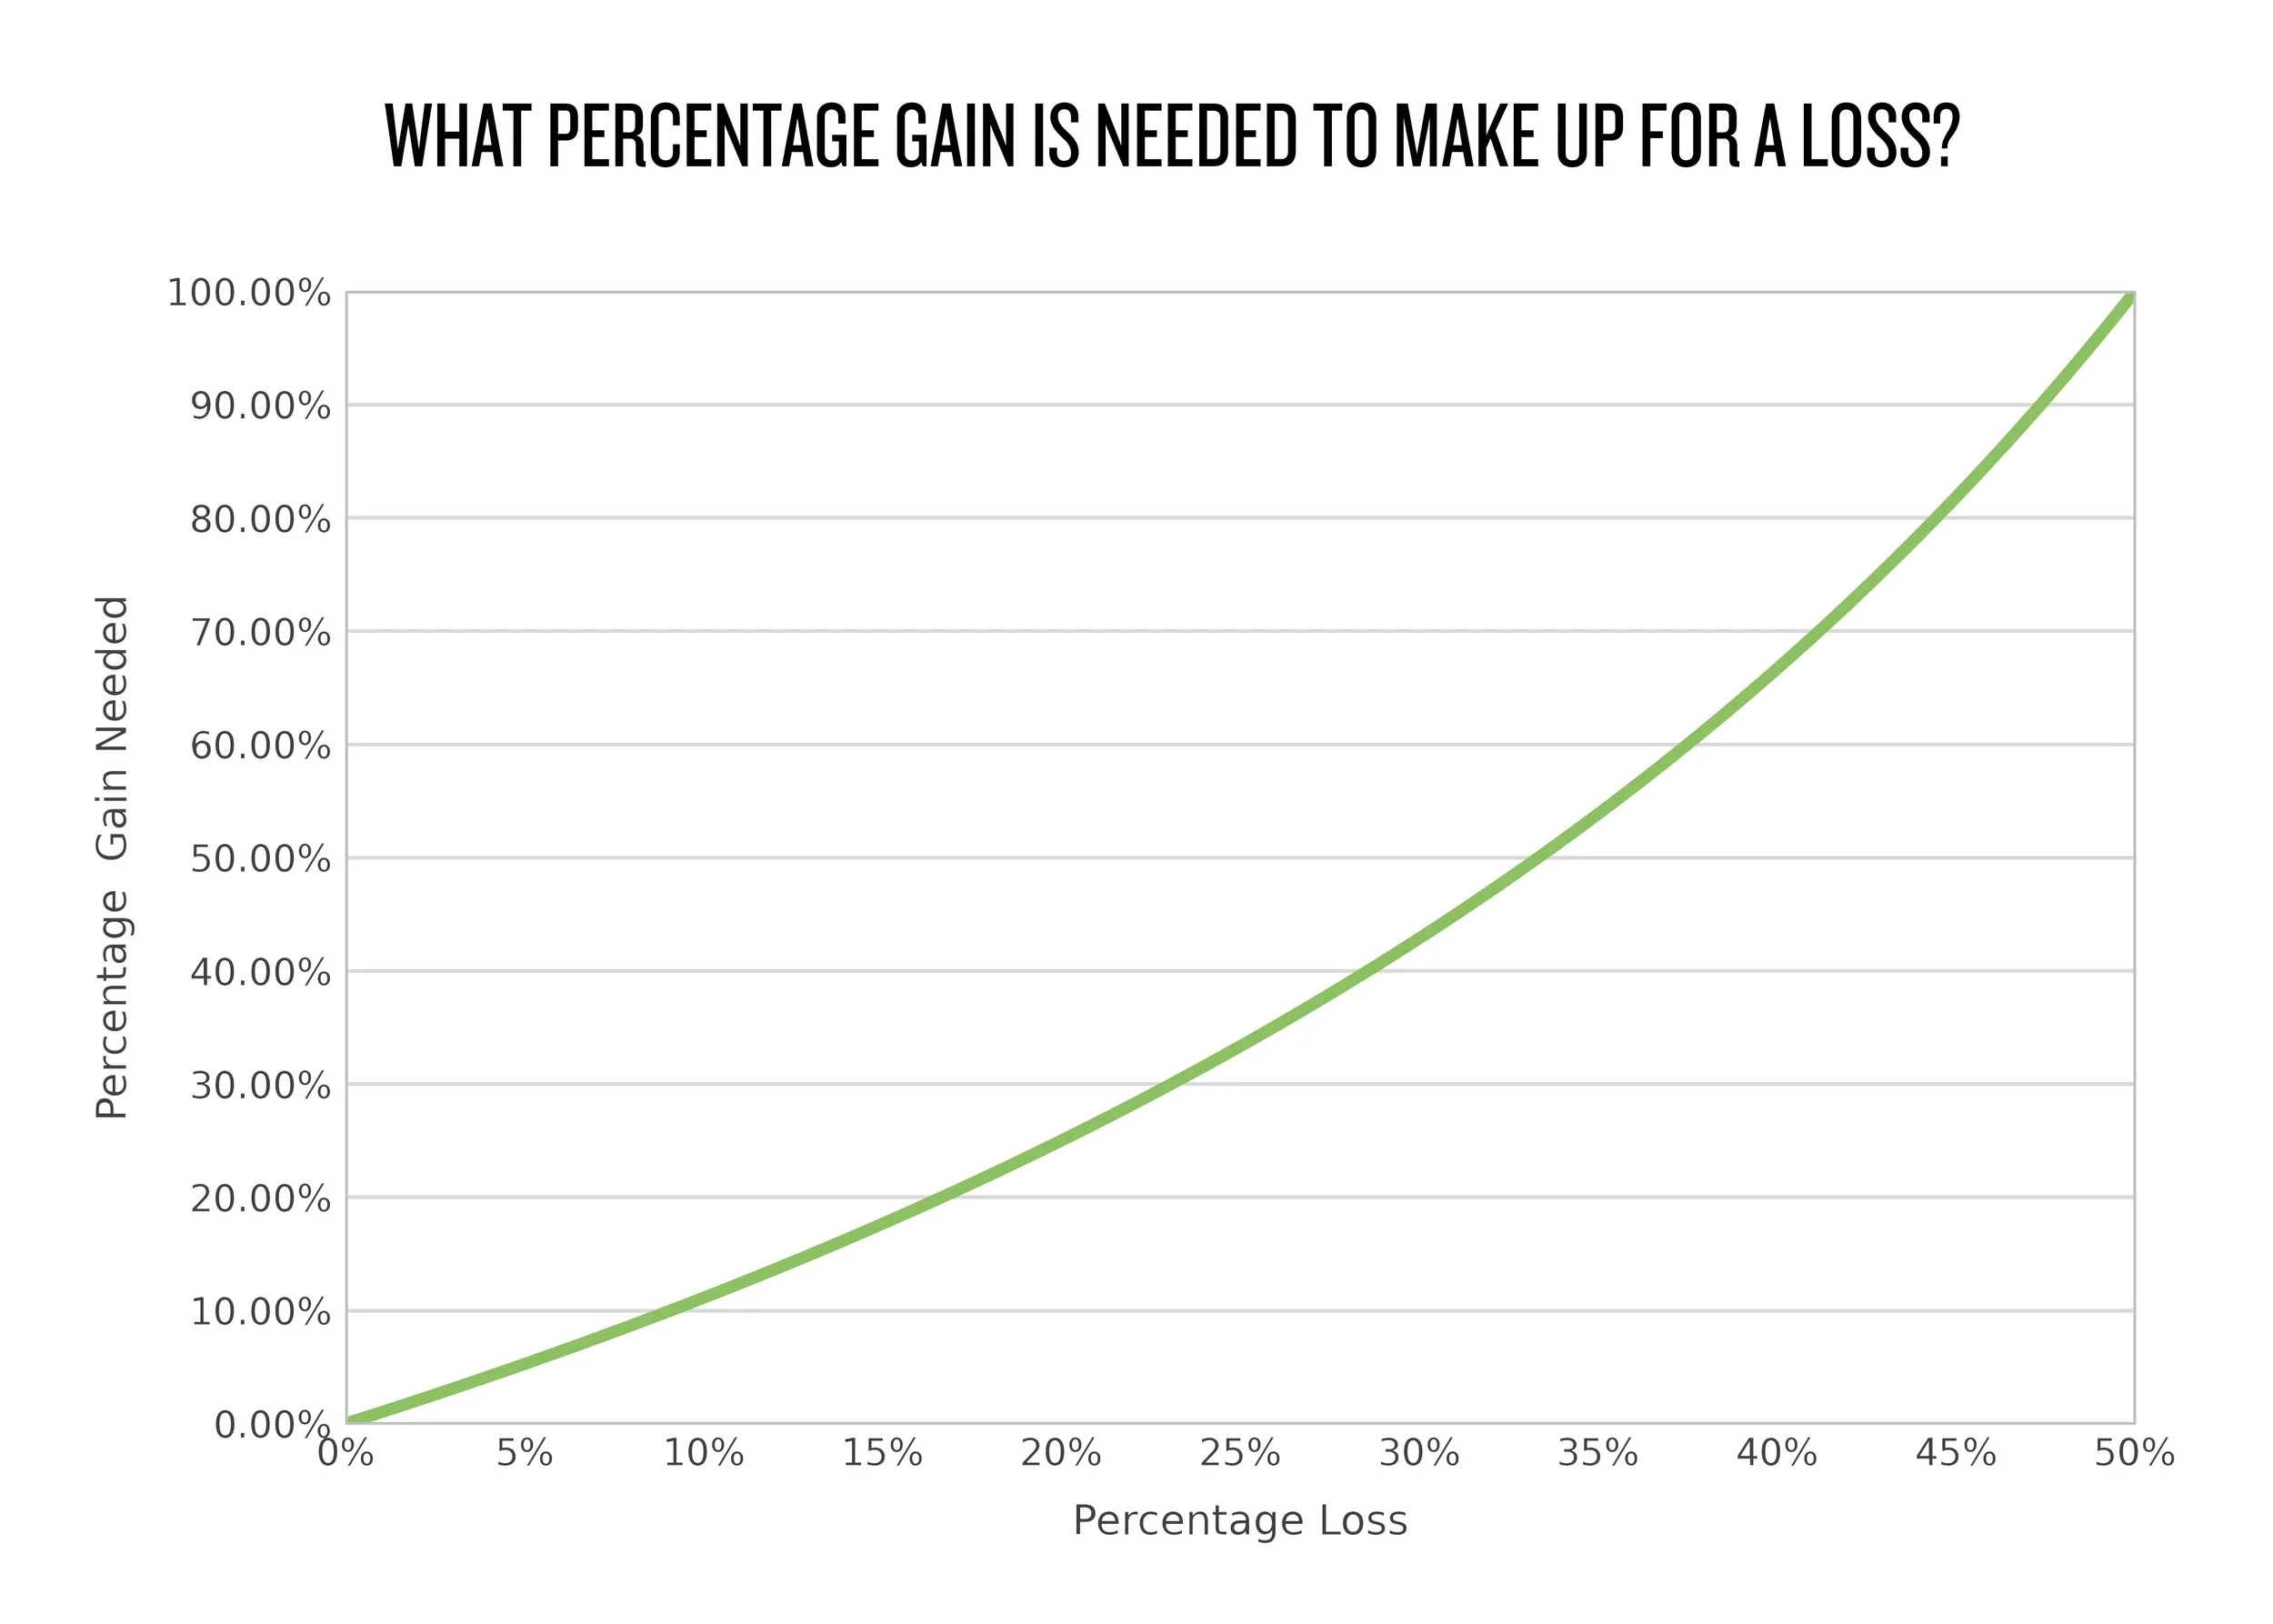
  • Chart: What percentage gain is needed to make up for a loss?


Part 2: The Odyssey Sirens

Part 3: Rip City Update

  • “Tom Dundon using a tired playbook.” Bald Faced Truth by John Canzano, 25 July 2026 [Article]

  • “Trail Blazers, city of Portland finally meet, but distance to arena deal remains ‘significant’.” The Athletic, 30 July 2026 [Article]

  • 4.14.2004: Kobe Bryant Nails the Winning 3 in Double OT [Video]

Part 4: Local Gems

  • Call Ja Morant Hotline [Link]

  • Suttle Lodge Boat House, Deschutes National Forest, Oregon [Link]


Disclosure:
This material is provided for informational and educational purposes only. It should not be construed as investment, legal, or tax advice, nor does it constitute a recommendation or solicitation to buy or sell any security. Investors should consult with a qualified financial professional before making any investment decisions. Rebalancing and asset allocation strategies do not ensure a profit or protect against loss in declining markets. There is no guarantee that any investment strategy will achieve its objectives. Any references to historical performance, academic studies, or research are based on past data and should not be considered indicative of future results. Past performance is not a guarantee of future outcomes. Advisory services offered through Human Investing, an SEC-registered investment adviser.


Related Articles

Hi Ground Episode 3: 2026 Halftime Report: Stock Market, Oregon Real Estate & Risk


Disclosure:
This material is provided for informational and educational purposes only. It should not be construed as investment, legal, or tax advice, nor does it constitute a recommendation or solicitation to buy or sell any security. Investors should consult with a qualified financial professional before making any investment decisions. Rebalancing and asset allocation strategies do not ensure a profit or protect against loss in declining markets. There is no guarantee that any investment strategy will achieve its objectives. Any references to historical performance, academic studies, or research are based on past data and should not be considered indicative of future results. Past performance is not a guarantee of future outcomes. Advisory services offered through Human Investing, an SEC-registered investment adviser.


Related Articles

Hi Ground Episode 2: Why is my paycheck disappearing so fast?


Disclosure:
This material is provided for informational and educational purposes only. It should not be construed as investment, legal, or tax advice, nor does it constitute a recommendation or solicitation to buy or sell any security. Investors should consult with a qualified financial professional before making any investment decisions. Rebalancing and asset allocation strategies do not ensure a profit or protect against loss in declining markets. There is no guarantee that any investment strategy will achieve its objectives. Any references to historical performance, academic studies, or research are based on past data and should not be considered indicative of future results. Past performance is not a guarantee of future outcomes. Advisory services offered through Human Investing, an SEC-registered investment adviser.


Related Articles

Hi Ground Episode 1: Is SpaceX Actually Going To Do Well?


Disclosure:
This material is provided for informational and educational purposes only. It should not be construed as investment, legal, or tax advice, nor does it constitute a recommendation or solicitation to buy or sell any security. Investors should consult with a qualified financial professional before making any investment decisions. Rebalancing and asset allocation strategies do not ensure a profit or protect against loss in declining markets. There is no guarantee that any investment strategy will achieve its objectives. Any references to historical performance, academic studies, or research are based on past data and should not be considered indicative of future results. Past performance is not a guarantee of future outcomes. Advisory services offered through Human Investing, an SEC-registered investment adviser.


Related Articles

Building Lasting Resilience in an Age of AI
 

“Assuming AI doesn’t take my job first.” We’ve heard some version of that line from clients all year, almost always delivered with a nervous laugh. But behind the humor sits a question a lot of people are wrestling with right now.

Every meaningful shift in technology brings a mix of optimism and concern, and artificial intelligence is no different. For some, this is still a conversation about what might happen. For others, it has already shown up in tangible ways, whether your role has changed, been eliminated, or you're watching your industry transform in real time.

If that's where you are, the uncertainty isn't theoretical, and it isn't just financial. Work is tied to identity, routine, and a sense of progress, which makes disruption especially hard to process. And even if nothing has changed for you yet, it's difficult to ignore the possibility that it could.

Your Most Important Asset

For most people in the accumulation phase of life, the most important asset isn't a number in your portfolio: it's your ability to earn income over the next decade or more. When that ability feels less certain, everything connected to it can feel less stable.

When that uncertainty sets in, the natural instinct is to try to predict what happens next: Should I pivot? Is this temporary? Am I already behind? It's understandable, but what if the path ahead is too uncertain to plan around with confidence?

A more useful shift is to move from prediction to preparation. Rather than guessing the outcome, focus more on understanding how to remain steady across a range of possibilities.

Start With What You Can See

Financial stress often grows in the space between what's happening and what's understood. Not knowing how long savings will last can feel heavier than the actual number, and not knowing which expenses are fixed and which are flexible can make every decision feel harder than it needs to be.

The starting point is visibility. When the future feels undefined, the mind fills in the gaps (usually with worst-case scenarios). Taking even small steps to map the situation eases that pressure, because it turns something vague into something concrete. The numbers don't have to change; they just have to be visible.

In practice, that often starts with mapping your monthly spending in simple terms. What's essential? What's adjustable? A mortgage and insurance premiums are fixed, but a planned trip or a streaming subscription can flex if they need to. This isn't about building a perfect budget. It's about seeing your situation clearly enough to make decisions from a place of information rather than panic.

From there, structured planning does the rest. Turning a broad concern into a set of defined scenarios — What if my income drops 20%? What if I'm out of work for six months? — makes it possible to act with intention, even when the future stays uncertain. A plan that only works when everything goes right tends to feel fragile. Building in room for strain is what makes it hold up.

Margin Changes the Experience

Two households can face the same disruption and experience it very differently. What separates those experiences is often margin.

Cash doesn't eliminate risk, but it creates time. Time is what makes good decisions possible. With room to breathe, you can weigh options, wait out a market, take the right job instead of the first one. Without it, choices narrow and decisions become reactive instead of intentional.

The most useful way to measure margin is through the lens of time: how many months of essential expenses could I cover if my income changed? The number doesn't need to be perfect, but it gives you a runway. If margin already exists, the goal is to protect it. If it doesn't, the goal is to begin restoring it gradually as circumstances allow.

Some households add a second layer of flexibility by putting a line of credit in place while income is stable. A home equity line of credit (HELOC) is a common example. The purpose isn't to rely on it; it's to have access to it if needed. These options are far easier to secure before they're necessary, and much harder to obtain once income has already changed.

While this example is not specifically about AI disruption, it illustrates the broader value of financial flexibility when circumstances change unexpectedly. One family we worked with ran into this while moving between homes. They found the right next home before their current home had sold, creating a temporary cash gap that their savings alone couldn’t comfortably cover. Because they had established a HELOC while their income and balance sheet were still strong, they were able to bridge the timing difference without rushing the sale of their old home or liquidating investments in a way that would have created an unnecessary tax bill. Once the previous home sold, the line was paid back down. What the HELOC provided was time and the flexibility to make decisions from a position of stability instead of pressure.

Margin doesn't stop the disruption, but it shapes how you respond to it.

Optimizing Your Plan Has a Ceiling

During stable periods, optimization feels like the natural move. There are opportunities everywhere to maximize tax efficiencies, increase savings, and align decisions around long-term growth. Each move is prudent on its own. But the more tightly a plan is optimized, the less room it leaves to adjust when something changes.

Retirement accounts illustrate the tension. They're powerful tools for building wealth, but they're built with constraints and hard to access when you need the money now. Assets that remain accessible before traditional retirement age may be less efficient by the numbers, but they offer something the optimized version can't: room to adjust.

The same pattern shows up in spending. As income rises, fixed commitments tend to rise alongside it. Bigger payments rarely feel restrictive in the moment, but when income changes or priorities shift, they can quickly reduce your ability to adjust.

Debt works similarly. Paying down a smaller obligation like a car loan creates real breathing room. Aggressively paying down a mortgage may improve the long-term math, but it locks money into your house that you can't easily get back if you need it.

Optimization assumes the future will look like the present, and flexibility assumes it might not. That's the difference between a plan that holds and a plan that breaks.

Another Form of Resilience

Visibility, margin, and flexibility are forms of resilience. There's another, less visible but increasingly important: what AI can’t replicate.

AI will keep reshaping how work gets done. It can already draft, analyze, and model at remarkable speed, and it will only get better. But the people who become most valuable (employees) won’t simply be the ones who know how to use AI. They’ll be the ones others trust when the stakes are high.

That kind of trust, the trust built when people share what's at stake, is what makes teams hold together when disruption hits. It's earned by showing up, by working through uncertainty together, by taking responsibility when outcomes aren't guaranteed.

AI can accelerate technical work, but it can’t replicate character, judgment, emotional steadiness, or genuine trust. In many ways, the rise of AI may make those qualities more valuable, not less. Used well, AI tends to amplify the people who already do good work, not replace them.

Create Your Adaptive Advantage

Preparing for uncertainty is less about reacting to every new development and more about maintaining a structure you can trust. In our experience, the people who navigate disruption well rarely anticipated every change. They took the time to understand their situation and made calculated adjustments along the way.

Alongside that structure, earning ability is something you can develop, not just protect. Staying current in your field, strengthening professional relationships, and gradually expanding into adjacent areas where your experience still applies all compound over time, even when the progress is hard to see in the moment.

If you're unsure where to begin, start small: understand your numbers, identify where you have flexibility, and take one step to strengthen your position. Clarity tends to build from there.

Preparation doesn't remove uncertainty, but it can keep uncertainty from making your decisions for you. In periods like this, that steadiness tends to matter more than most people expect.


Disclosure:
This material is provided for informational and educational purposes only. It should not be construed as investment, legal, or tax advice, nor does it constitute a recommendation or solicitation to buy or sell any security. Investors should consult with a qualified financial professional before making any investment decisions. Rebalancing and asset allocation strategies do not ensure a profit or protect against loss in declining markets. There is no guarantee that any investment strategy will achieve its objectives. Any references to historical performance, academic studies, or research are based on past data and should not be considered indicative of future results. Past performance is not a guarantee of future outcomes. Advisory services offered through Human Investing, an SEC-registered investment adviser.


Related Articles