Posts tagged income1
The Bond Market is Changing Retirement Math


Today's bond market may represent the most important shift in retirement strategy in over a decade. To understand why, we need to start with where equities have been. Over the 15 years ending in September 2026, the Vanguard S&P 500 ETF (VOO) generated an annualized return of more than 15%. For investors approaching or already in retirement, those returns may have helped create a welcome problem: their portfolios are larger and potentially more equity-heavy than they once expected.
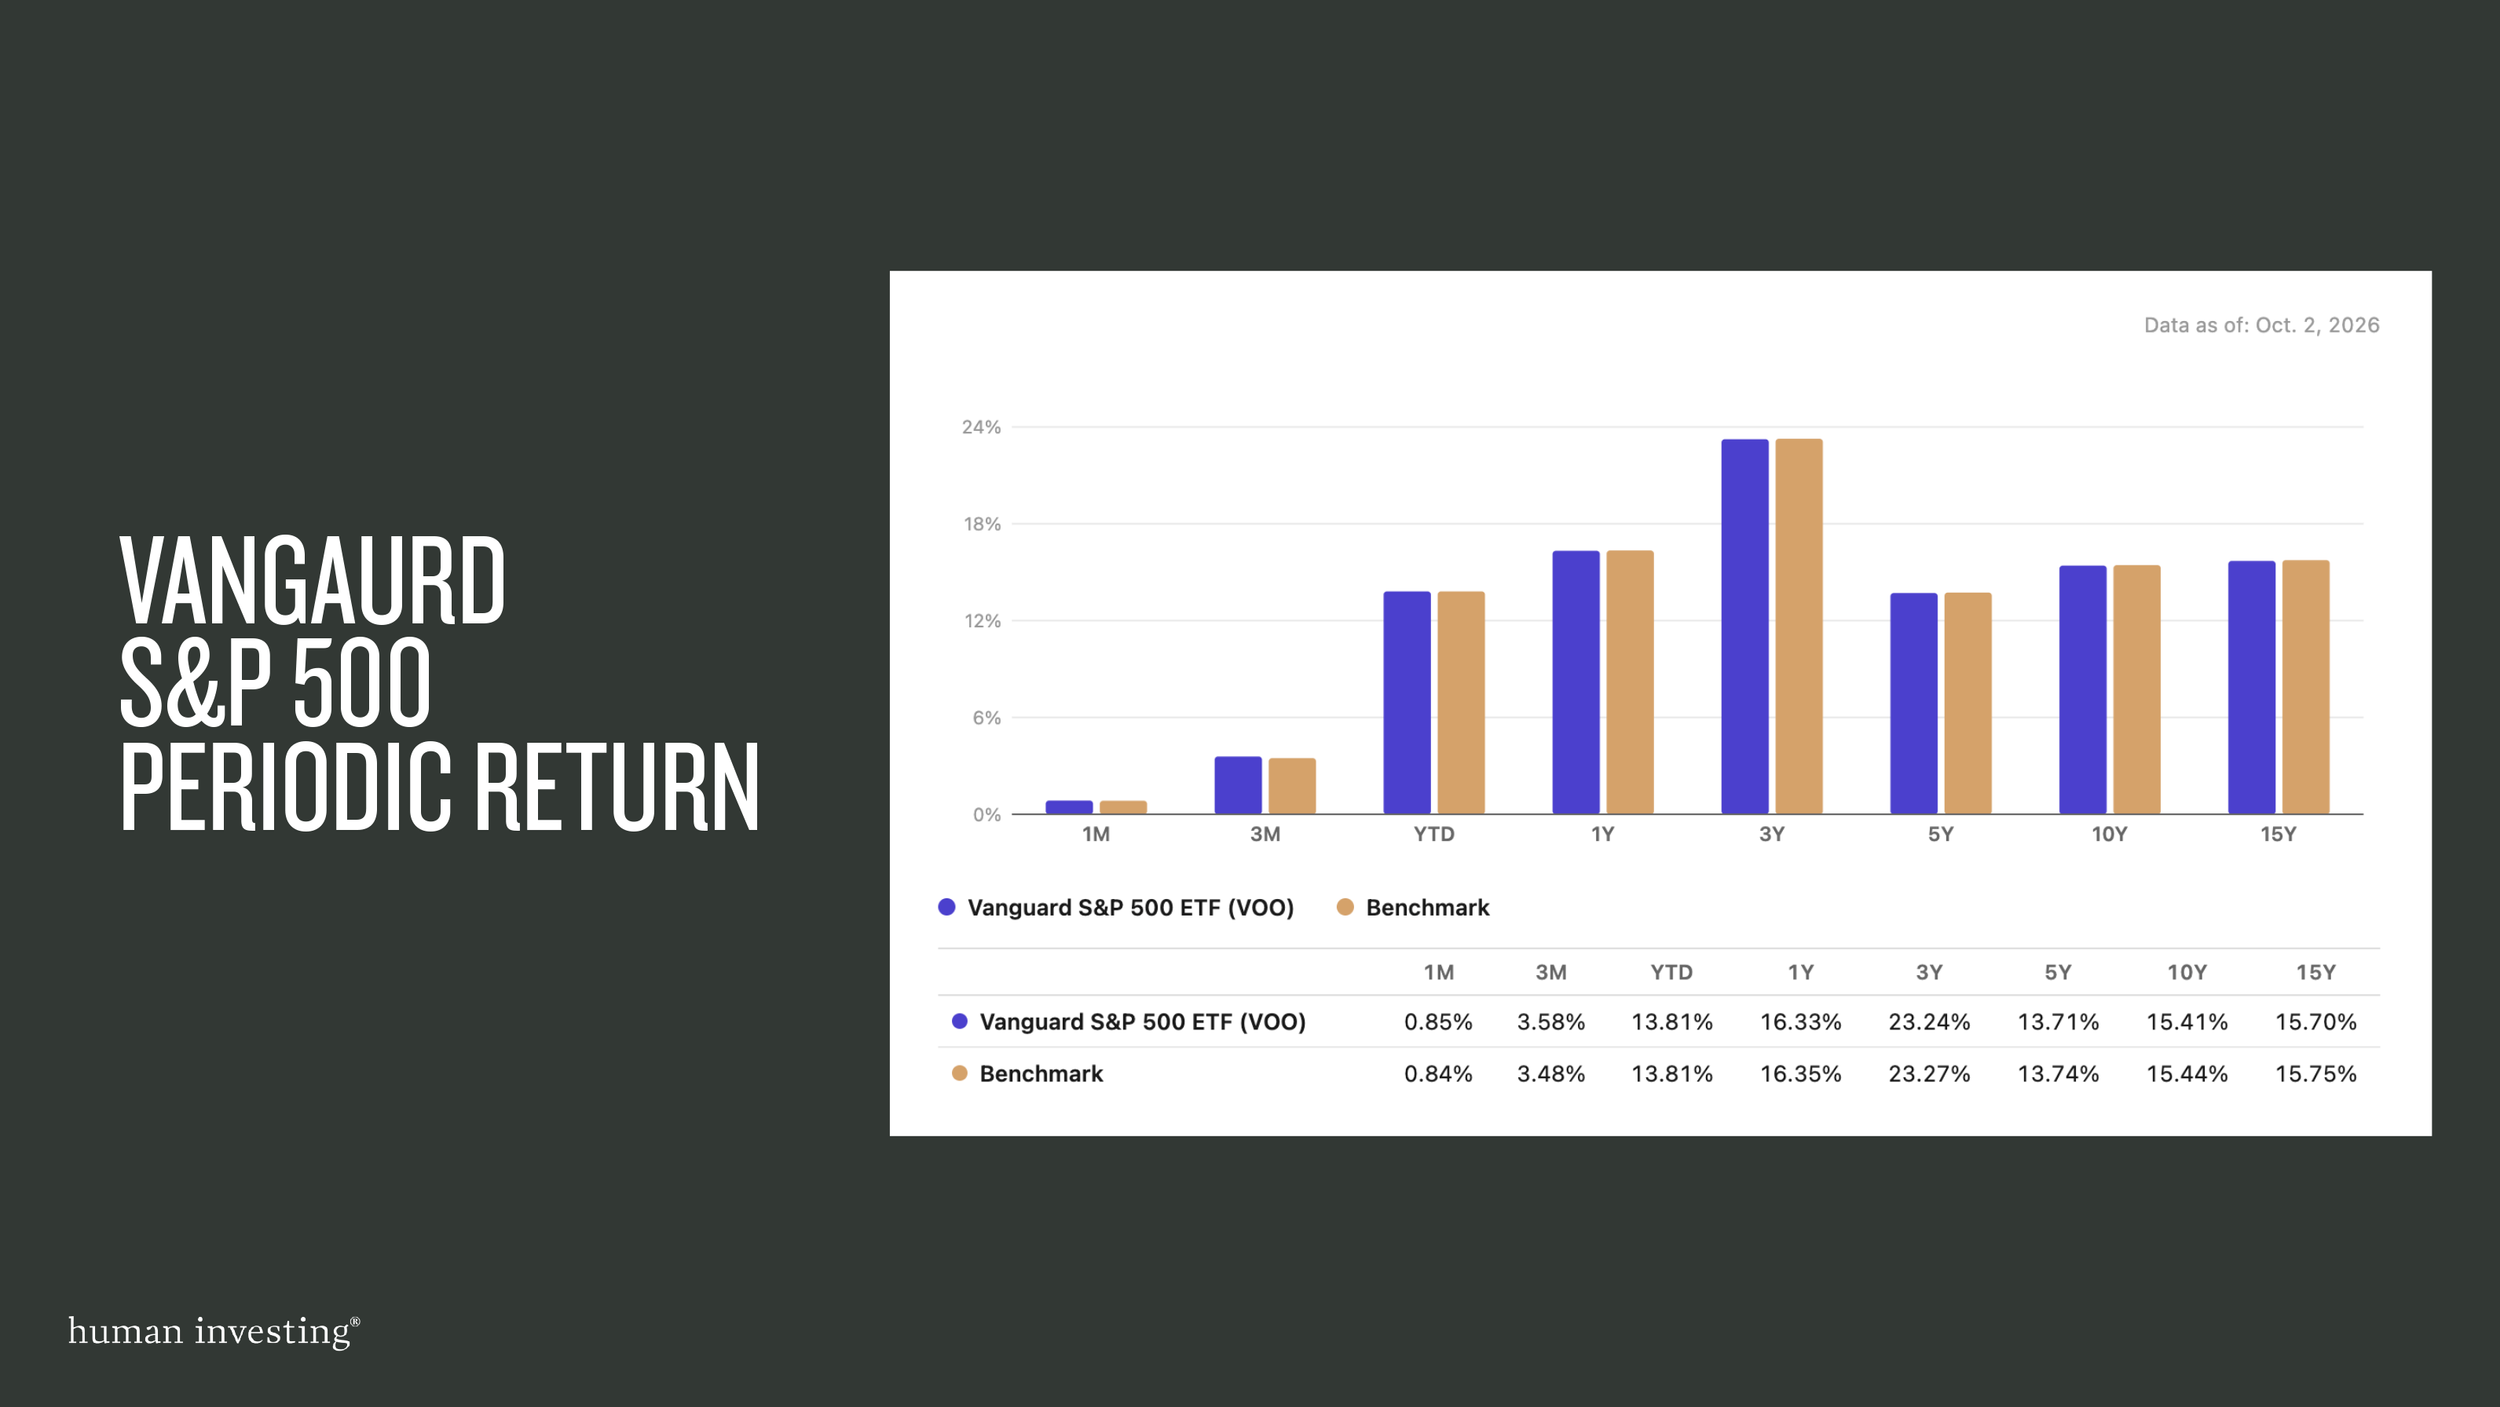
Note: The Benchmark here is the S&P 500. Data courtesy of YCharts.

The reason for an investor's portfolio being potentially over-exposed to equities based on their age could be for one of two reasons.

  1. They intentionally selected to be more aggressive based on their comfort level with risk and economic conditions.

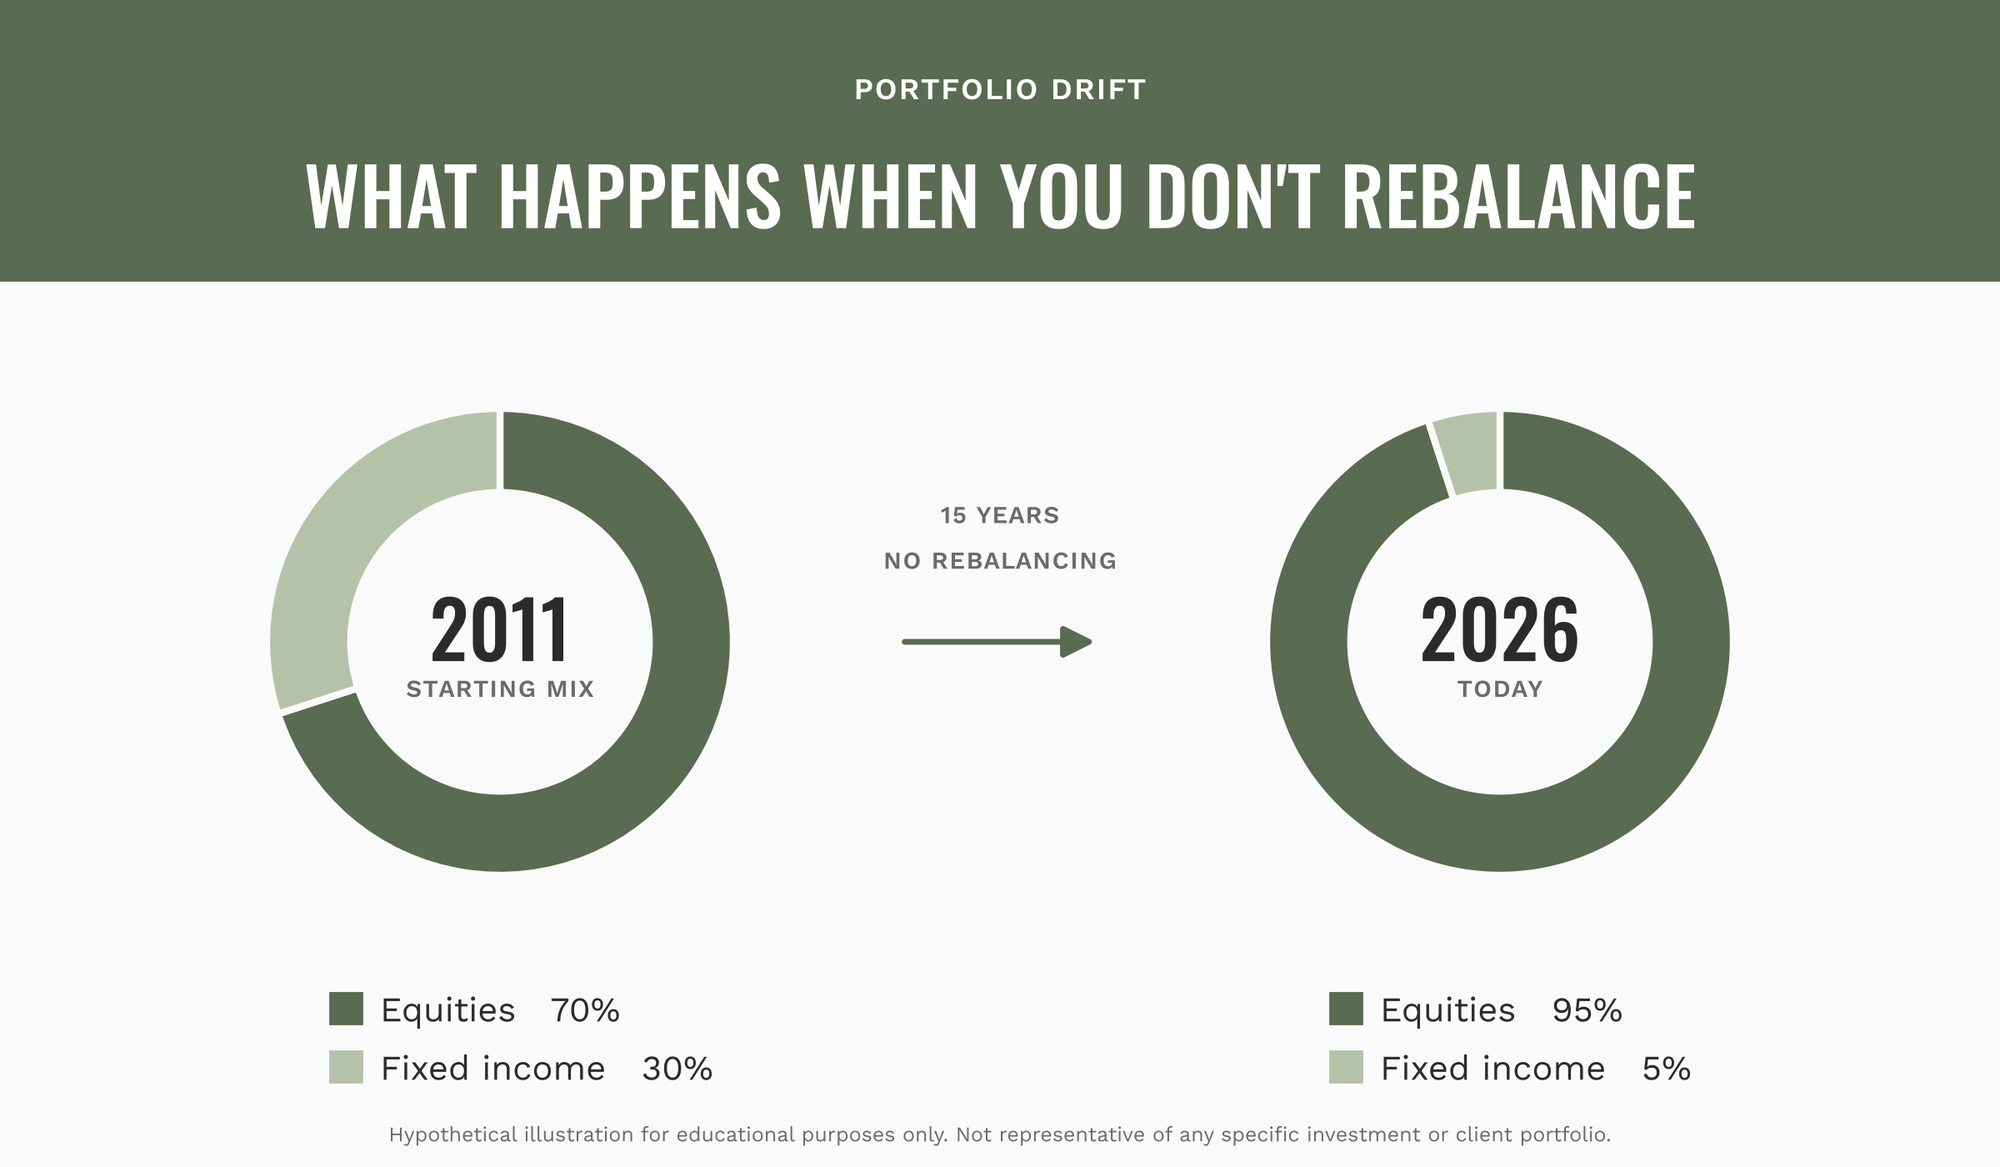
  2. They initially invested their portfolio in a more balanced methodology and did not rebalance their portfolio as equity markets grew. Take a portfolio that was invested in 70% equities and 30% fixed income 15 years ago. That portfolio left without rebalancing is now 95% equities and 5% fixed income in 2026. 
That 15% annualized return from the S&P 500 came with real volatility and its share of drawdowns. For many investors, those moments made it easy to avoid rebalancing. Whether it was COVID 19, peak tariff volatility in 2025, or more recently a steep increase in the price of oil with the closing of the Strait of Hormuz, there were plenty of reasons to hold tight.

The point being risk feels very different after you’ve been rewarded for taking it on for more than a decade.

While stocks were soaring, bonds went through a different period

For much of the 2010’s interest rates were low by historical standards. Then during the pandemic Treasury yields fell to extraordinary lows. For someone building a retirement portfolio, this presented a challenge. Imagine your financial plan required roughly a 5% rate of return to be considered “successful”. If high-quality bonds were yielding 1-2%, investors needed to find growth from somewhere else. Stocks were a great source of growth over the last 15 years, but we can never count on markets to repeat themselves.

One lesson our team applied during these years, and one we regularly enforce with clients, is that every financial plan has an implicit return hurdle. The lower the expected return from the conservative portion of a portfolio, the more work the growth portion of the portfolio has to do. Today that equation looks different.

The Bond Market Has Changed Dramatically & It’s Changing Retirement Math

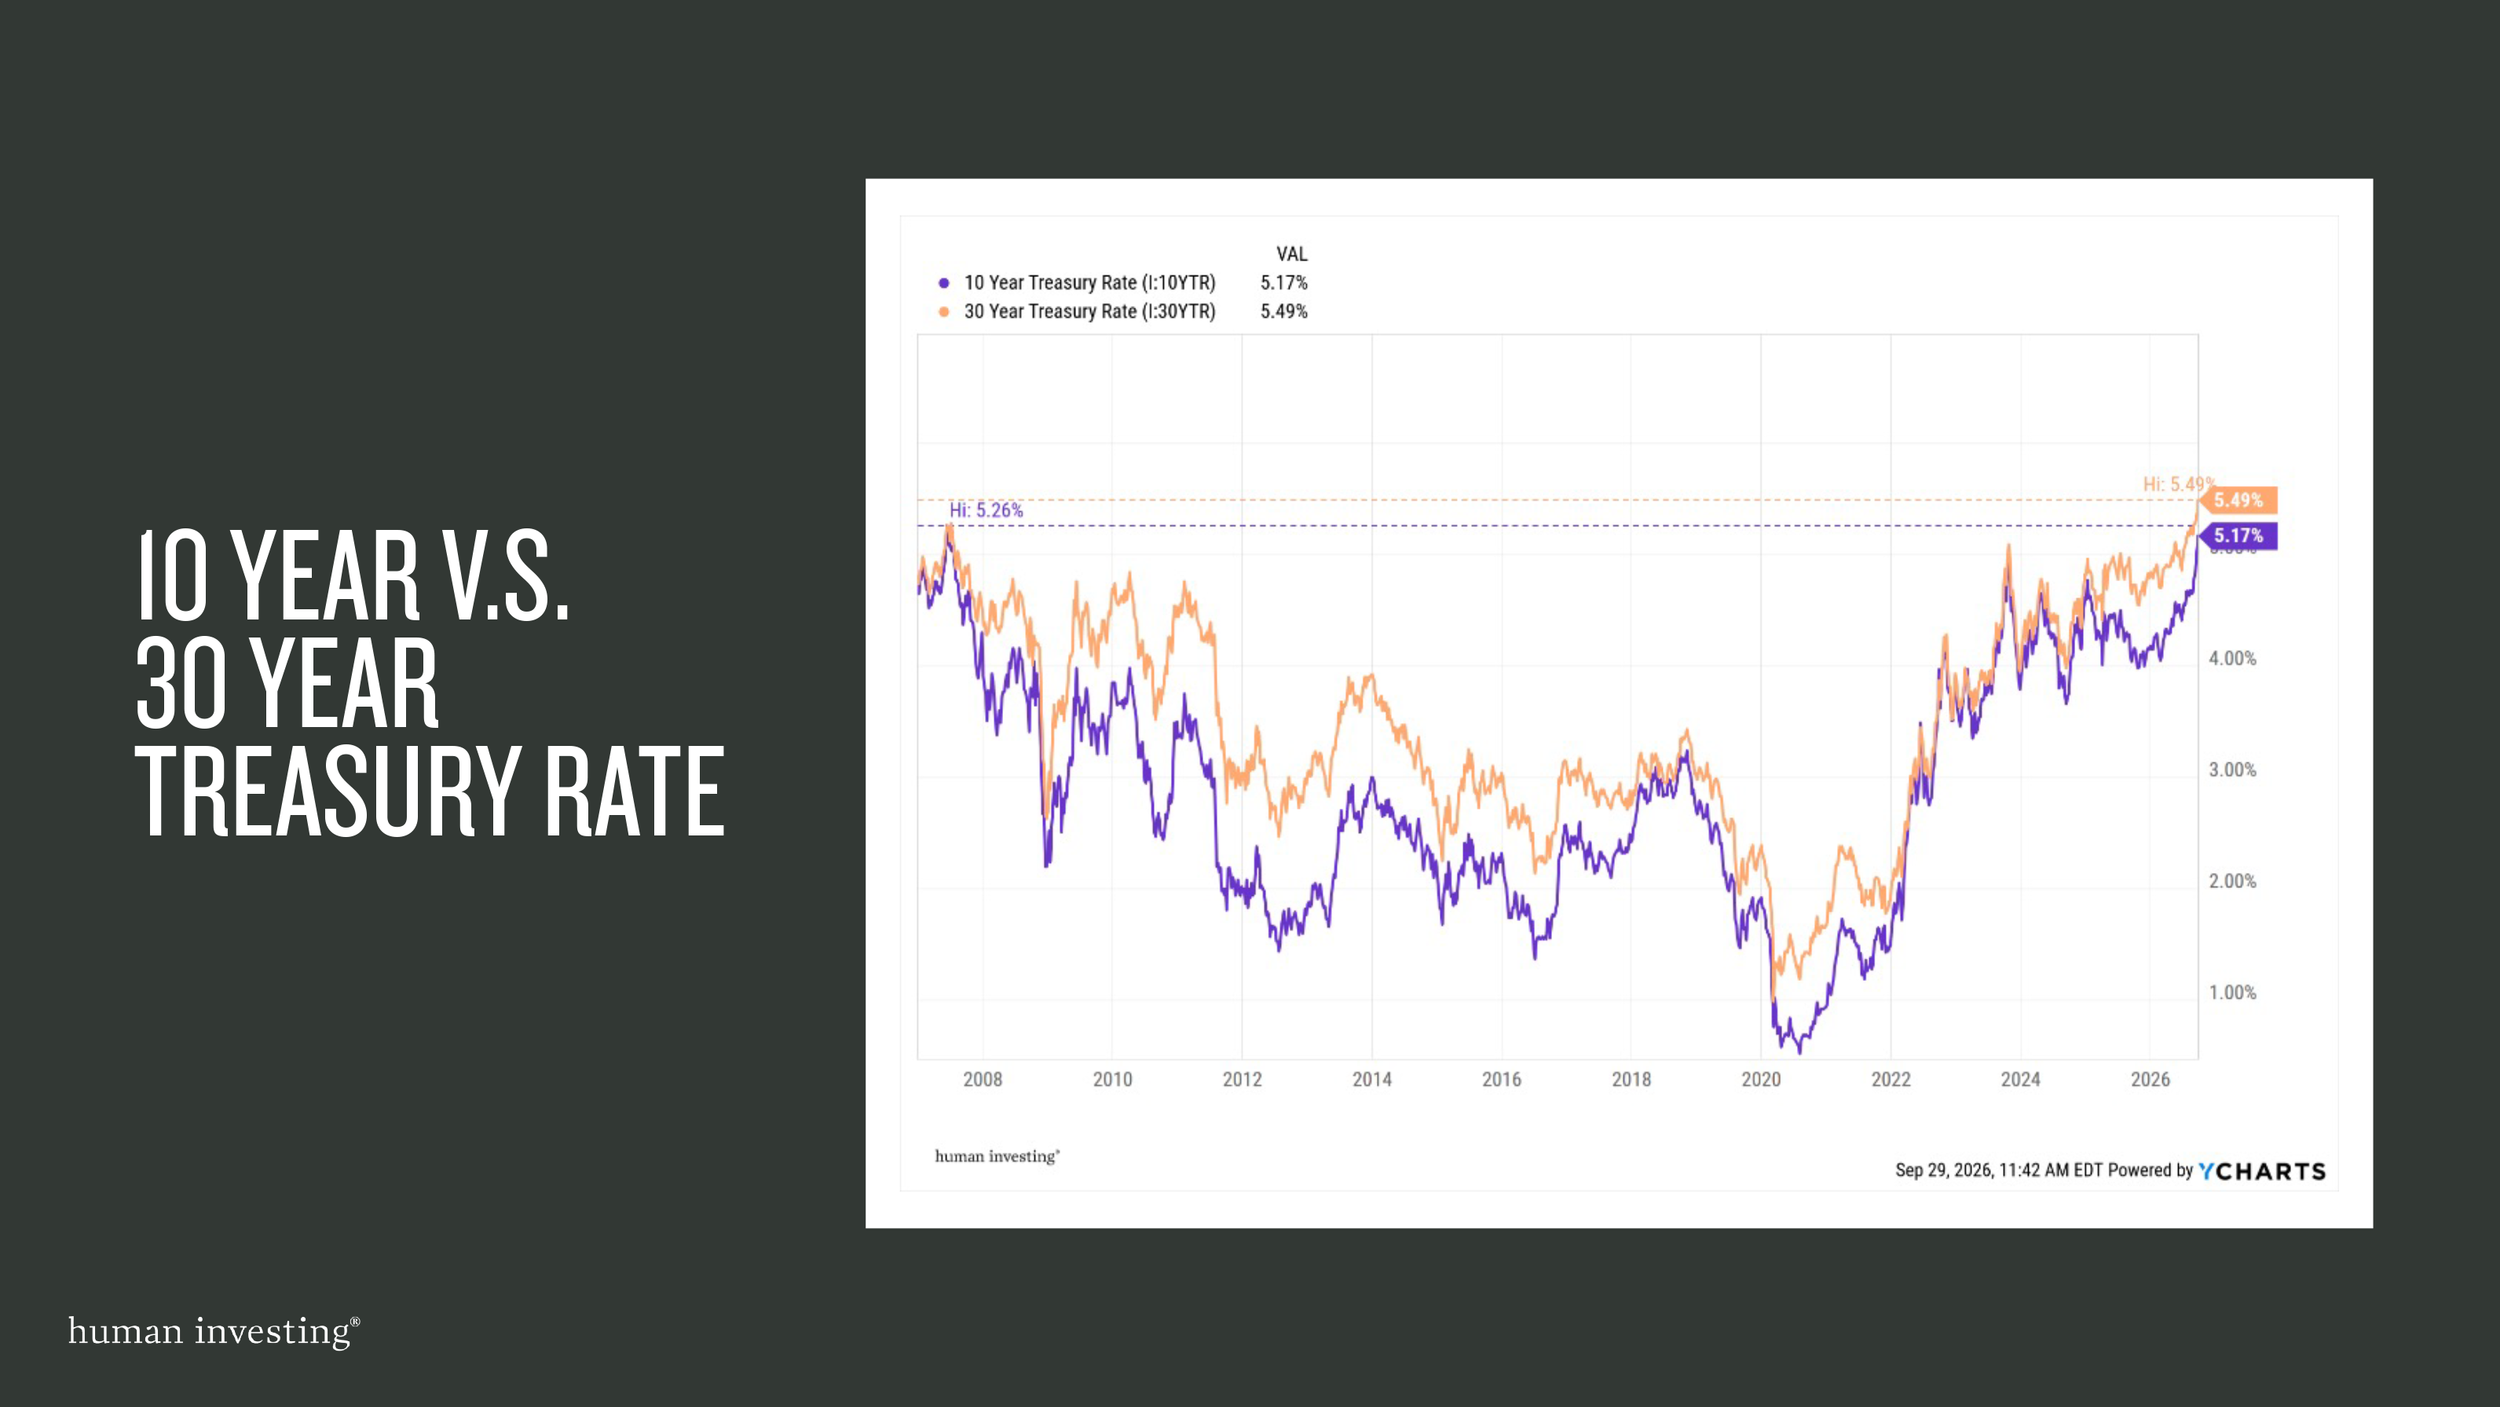
For investors looking to rebalance funds away from equities or cash and into bonds, it’s important to recognize that today’s starting point for the bond market is fundamentally different than it was for much of the past 15 years.  For a retiree, the important takeaway isn't why rates moved from below 1% to above 5%. It's what those higher yields mean for the role bonds can play in a retirement portfolio. Bonds can once again contribute meaningfully toward achieving your financial goals. And importantly, they can do so while playing the traditional roles we'd expect from fixed income: generating income, providing diversification and generally taking less risk than equities.
Data courtesy of YCharts.

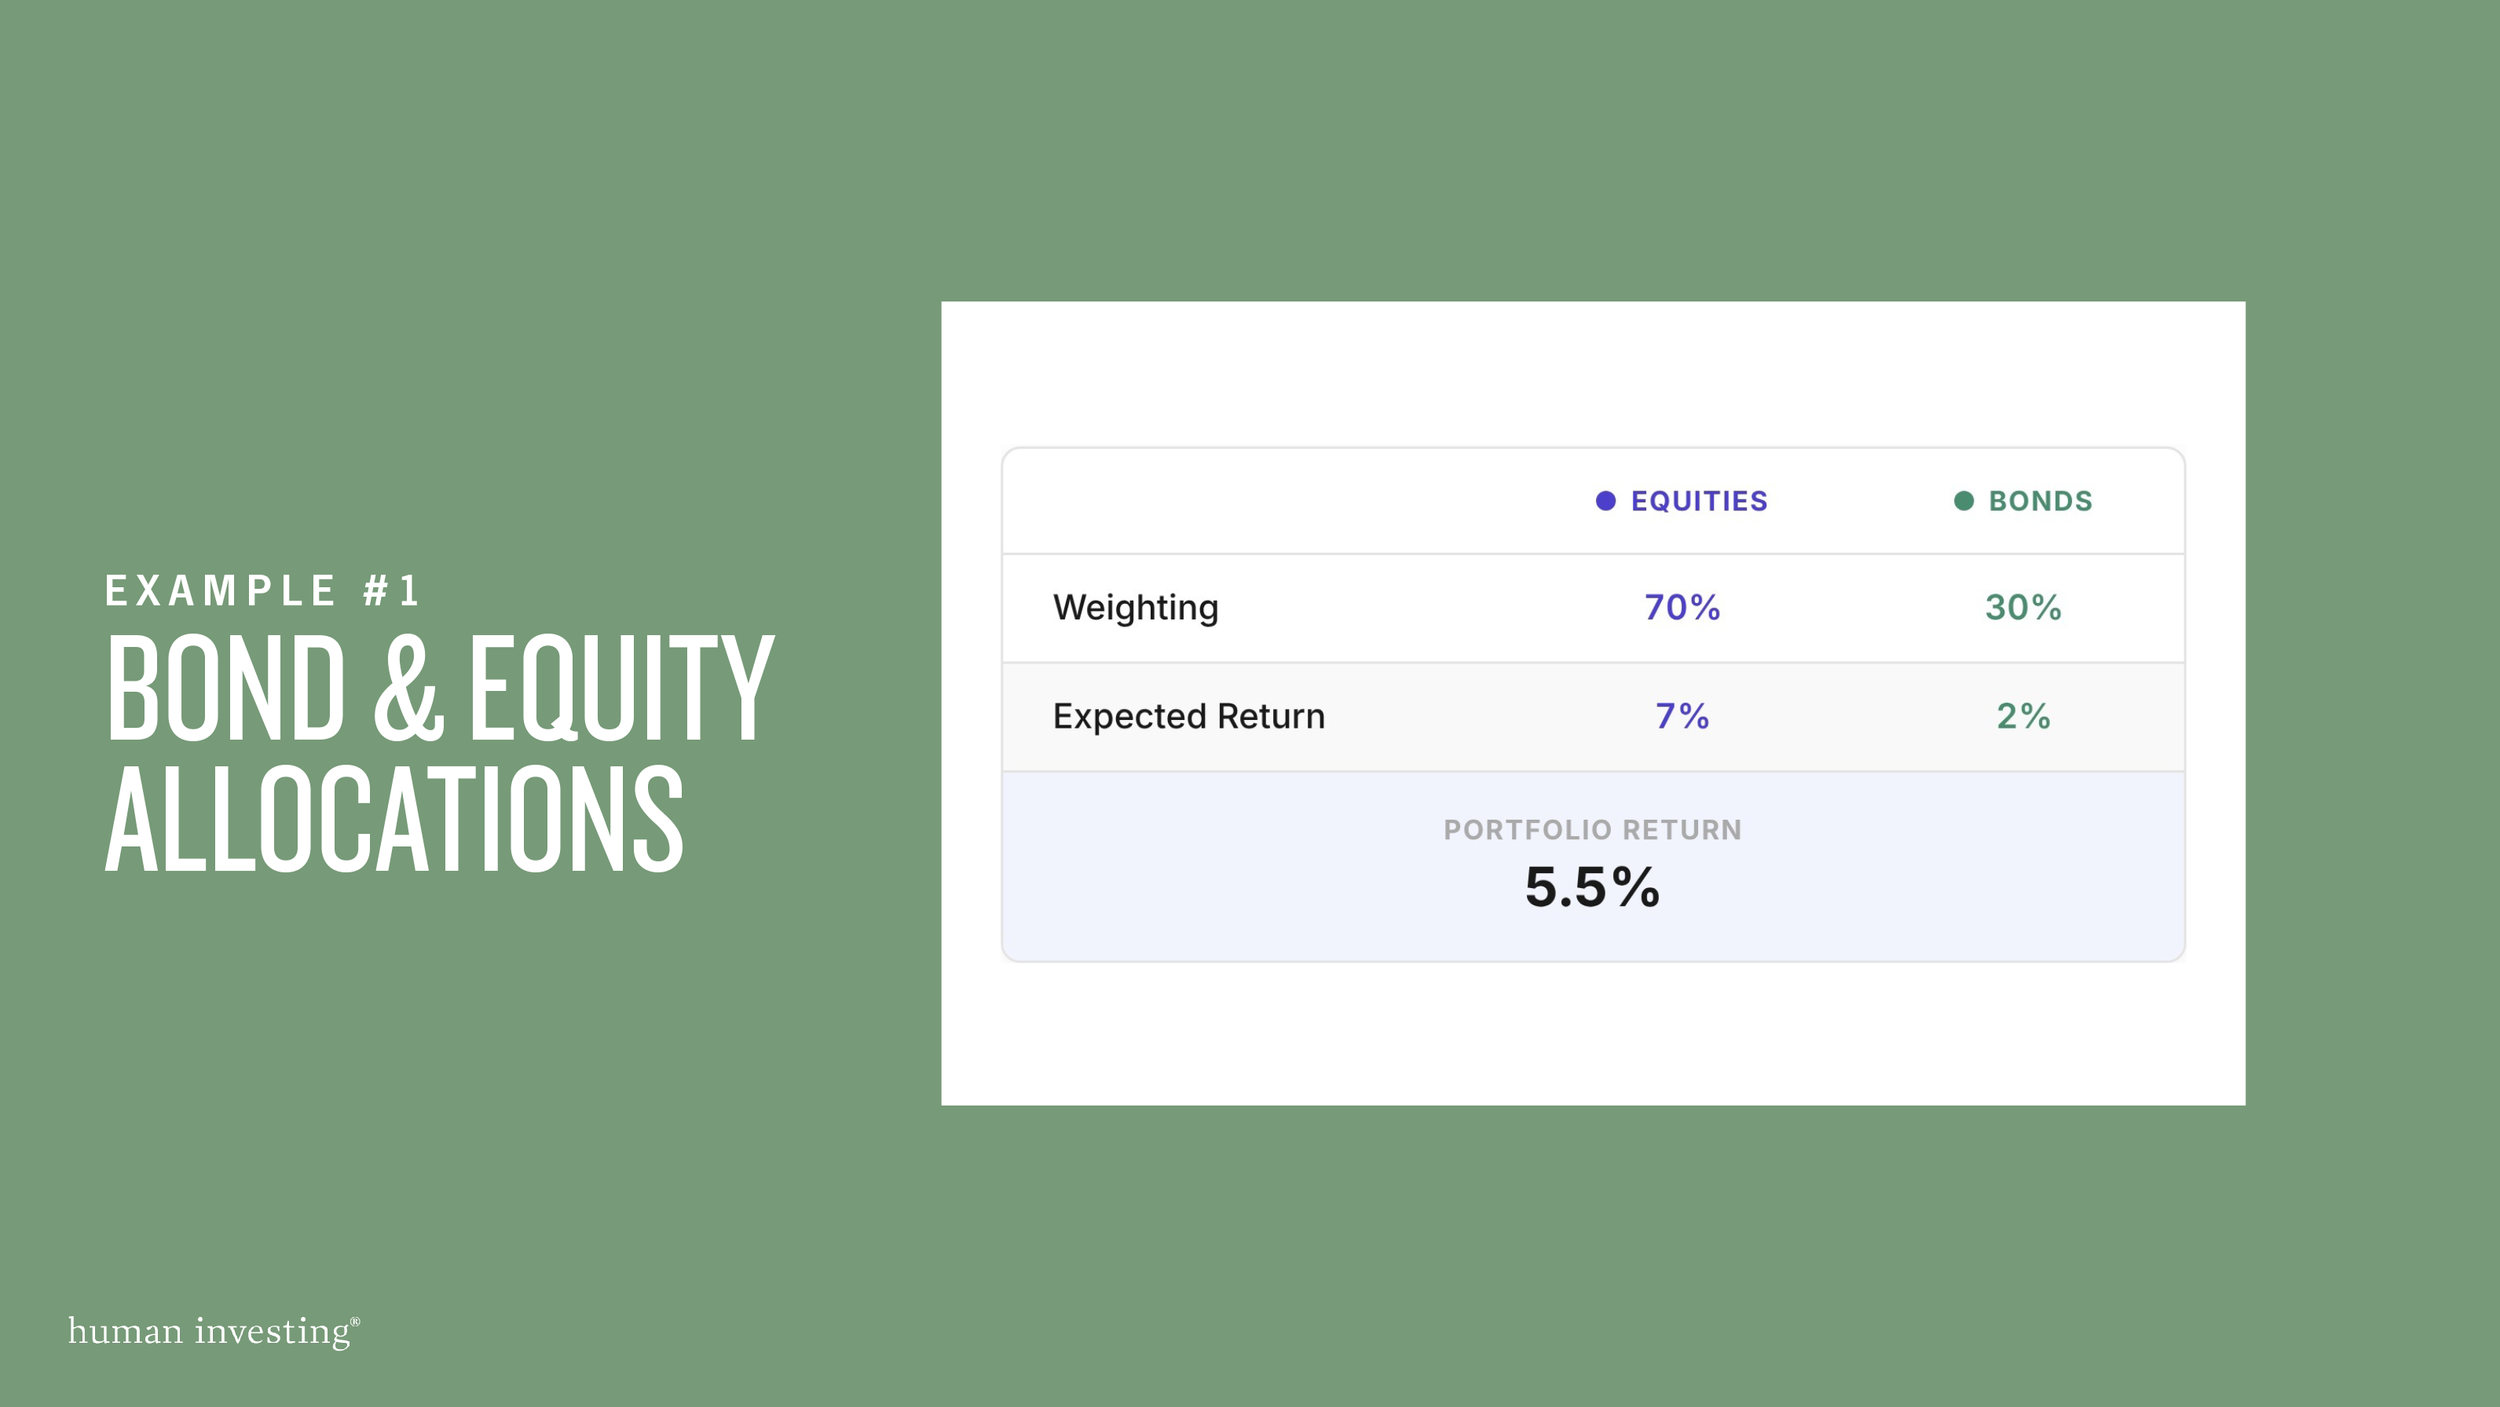
How does this change the Math for retirees? Let’s assume that someone has completed their financial plan. After accounting for spending, social security, inflation, taxes, longevity, and other goals the plan indicates that their portfolio needs to earn between 5.25% and 5.5% over the long run for their plan to succeed. This leads to the key question:

“How much risk do I need to take to reasonably pursue the return this plan requires?”

In 2020, answering that question was difficult. With high-quality bonds offering very low yields, a portfolio targeting a moderate return generally needed to rely more heavily on equities for growth.
All numbers used in the above table are examples and should be used as educational material, not advice. (Nerd Wallet)

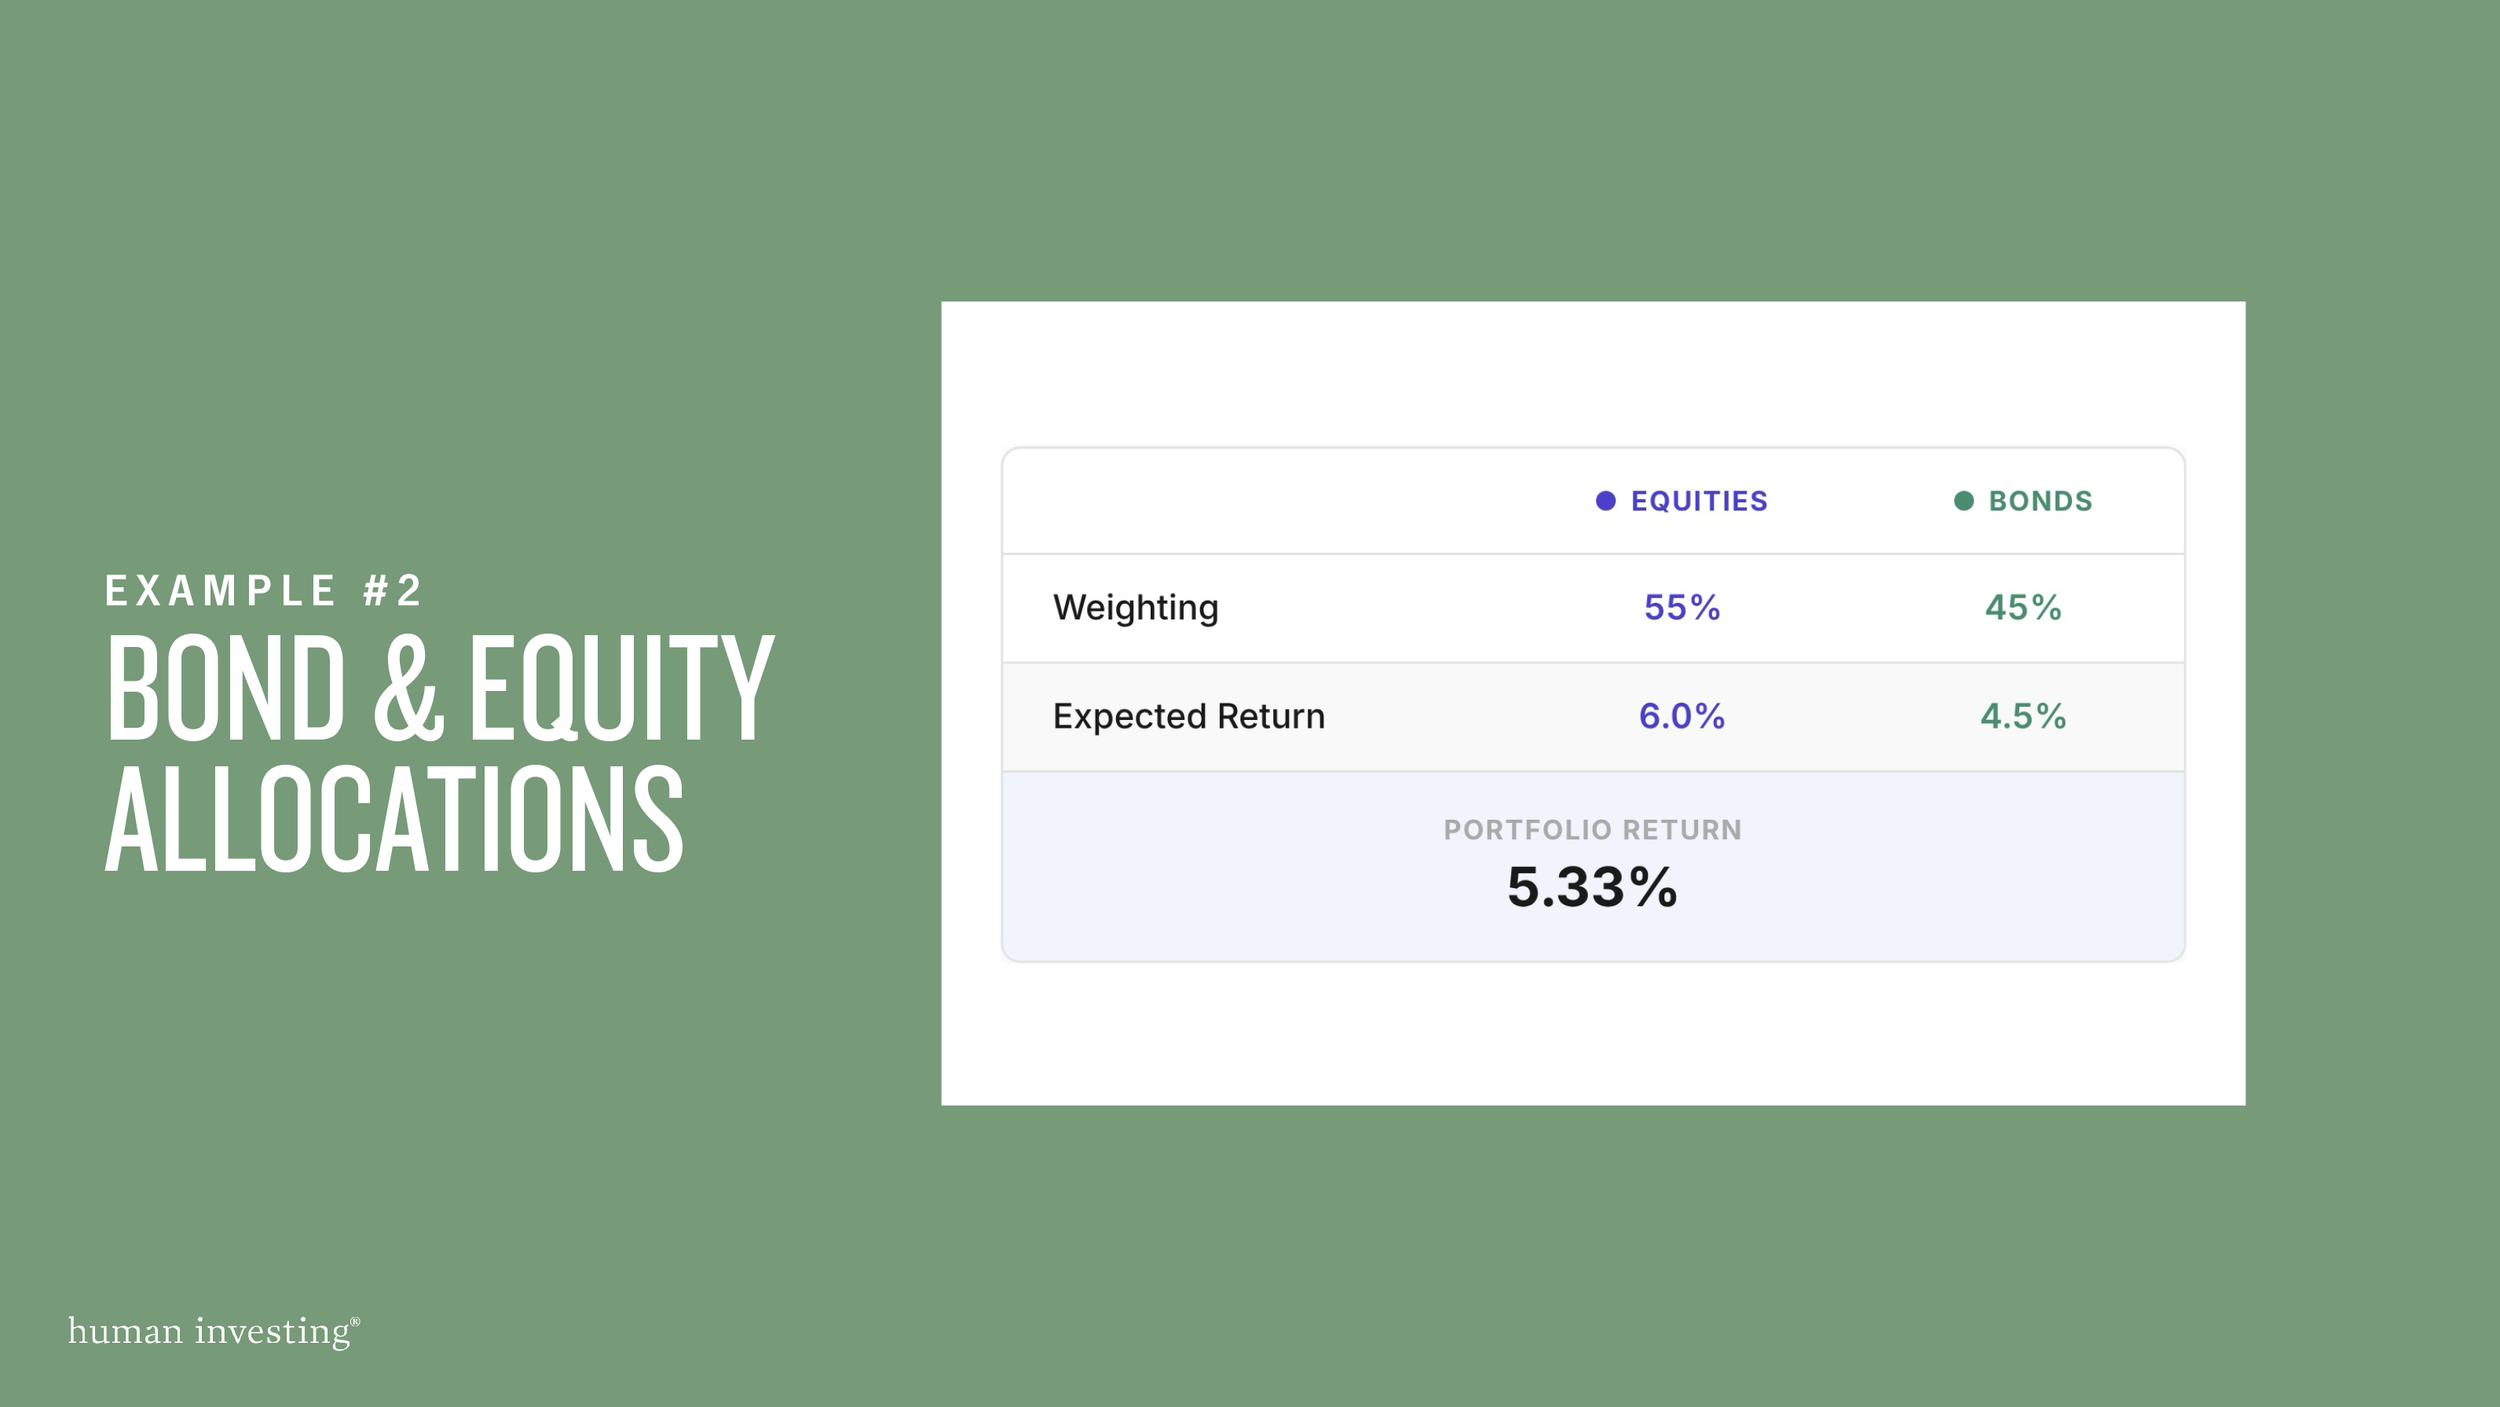
Today, higher starting bond yields allow us to potentially accomplish two things at once:

  • Use a more conservative expected return assumption for equities rather than relying on the exceptional returns of the recent past.

  • Increase the bond allocation while still maintaining an expected portfolio return consistent with the financial plan.
All numbers used in the above table are examples and should be used as educational material, not advice. (Nerd Wallet)

The point isn't that retirees no longer need stocks. It's that bonds can now contribute considerably more toward the portfolio's return objective, potentially reducing how much equity risk is required.

Today's Higher Yield Also Provides Something Bonds Didn't Have in 2020: A Cushion

As a reminder, when rates rise, existing bond prices fall, and when rates fall existing bond prices rise. That’s why 2022 was such a painful year for bond investors. But there's another part of the equation that sometimes gets overlooked: the income you're receiving from the bond.

In the chart below, Fidelity looks at the Bloomberg U.S. 7–10 Year Treasury Index and estimates the effect of a 100-basis-point (or 1-percentage-point) move in yields. August 2020 shows that if at that time rates went up 1% the index would fall 7.2% and if rates decreased 1% it would return a positive 8.2%.

Compare that to today where the starting yield is 5% where if rates increase 1% the index would decrease 1.9% vs. if rates decrease by 1% the index would increase 11.9%.
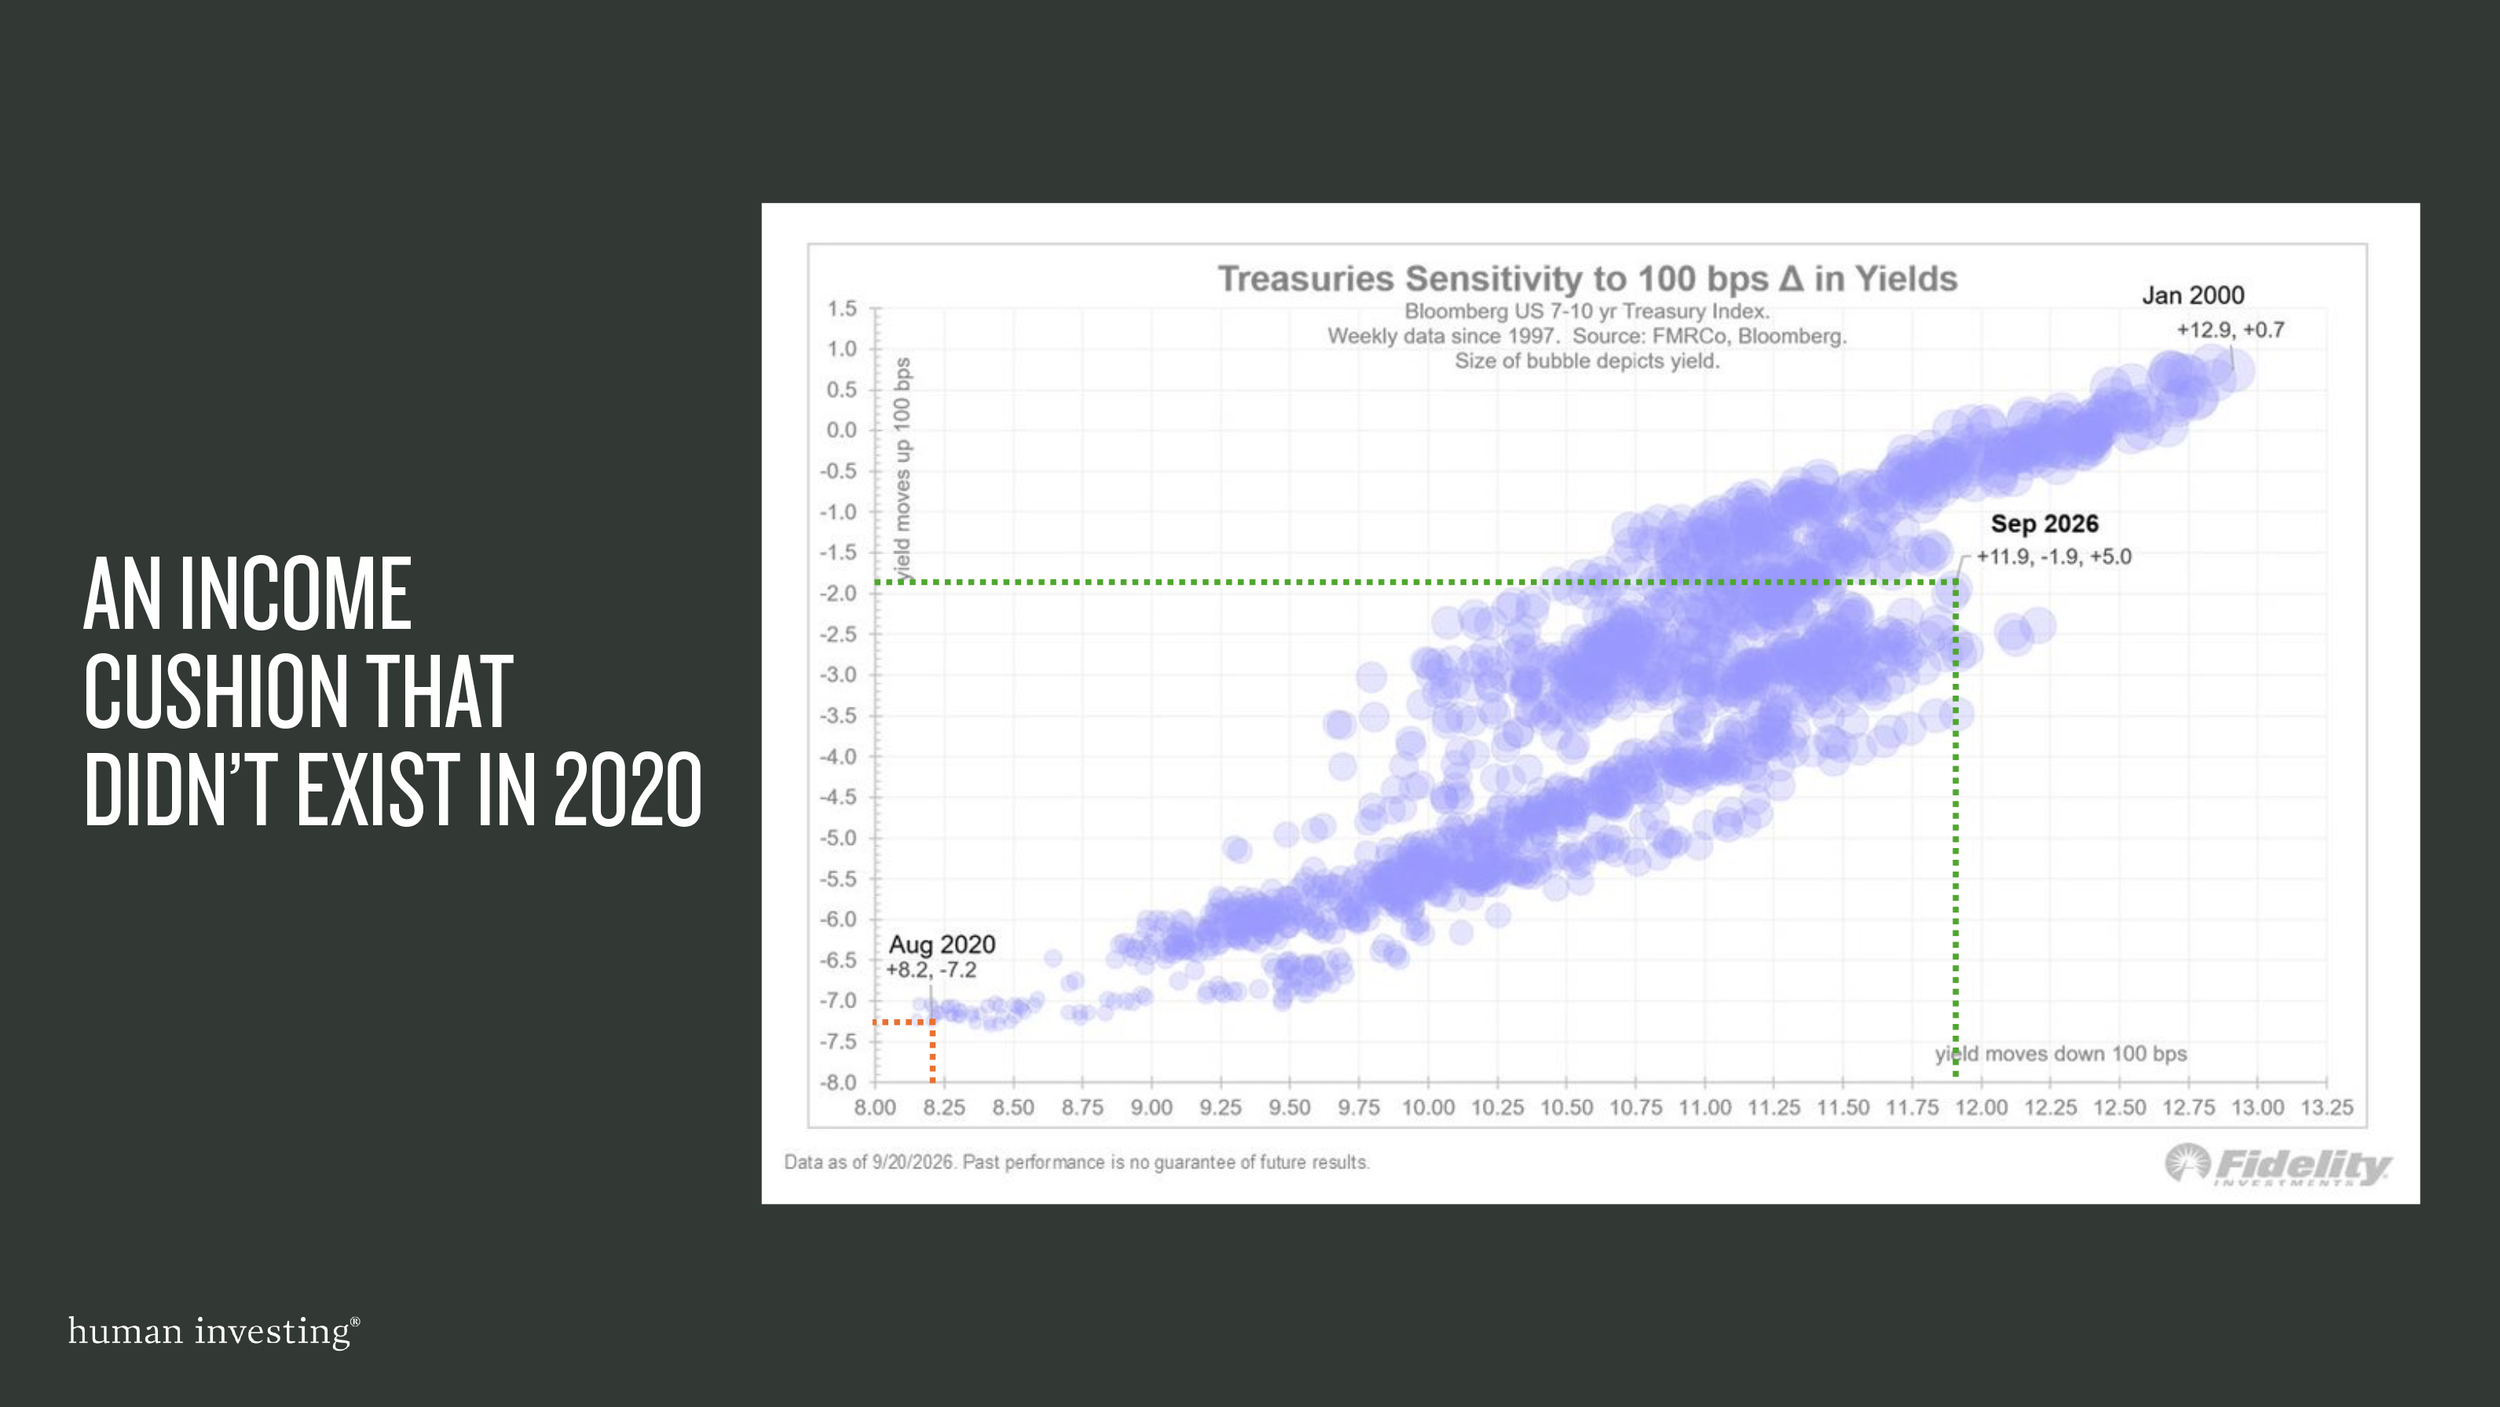
This scenario occurs when the investor is starting with considerably more yield. Higher yields don't eliminate interest-rate risk. But they change the starting point. When yields were near zero, there was very little income available to offset falling bond prices. With yields around 5%, investors begin with considerably more income working in their favor. If rates decline, bond investors may benefit from both the income they are receiving and price appreciation.

This is by no means a prediction of where interest rates are heading. The key point is that the starting economics of owning bonds are considerably different today then is was at any point over the last 15 years.

So, What Now?

A few closing thoughts for investors considering what this changing environment means for their portfolio.

This post is not a call to get out of stocks. My hope is that this post allows investors to review their portfolio and take inventory of their allocation. Reducing risk because you think the stock market is about to fall is market timing. Reducing risk because your financial plan no longer requires you to take as much risk is financial planning. This post is asking you to consider the latter.

For individuals nearing or already in retirement, the consequences of investment risk are also different than they were earlier in life. For someone who is 35 and accumulating assets, volatility can actually be useful. They're continuing to buy investments and have decades before they'll need the money. The equation changes as retirement approaches. A significant market decline during the first few years of retirement can be particularly damaging because an investor may simultaneously be experiencing investment losses and withdrawing money from the portfolio to fund their lifestyle. That's when the amount of risk you take and the risk you actually need to take, becomes increasingly important.

Don’t start with your investment allocation; start with your plan. We have an amazing team of CFP’s at Human Investing who remind me of this frequently.

Instead of starting with questions like:

"Should I own 60% stocks?"

"Should I move from 70/30 to 60/40?"

"Are bonds attractive?"

"Is the stock market overvalued?"

Start with one step earlier: What does my money need to accomplish, and what rate of return does my financial plan require to get me there?

Once you understand that number, many of the other questions become easier to answer.

The goal of retirement investing isn't to earn the highest return possible. It's to earn the return necessary to accomplish your goals while taking an appropriate amount of risk along the way.

After 15 years of strong equity returns and a dramatic change in the bond market, this may be an especially good time for pre-retirees and retirees to revisit that calculation.


Disclosure: Human Investing is an SEC-registered investment adviser. Registration does not imply a certain level of skill or training. This content is for informational and educational purposes only and does not constitute personalized investment advice or a recommendation. Past performance is not indicative of future results. All investments carry risk, including potential loss of principal. Readers should consult with a qualified professional regarding their specific financial situation.
 

Related Articles

Ballpark Your Retirement Readiness With Our Simple Calculator


Being a financial advisor means friends and family feel comfortable asking you their most personal money questions. A friend pulled me aside at coffee last week with a question we hear all the time: How do you know when you can actually afford to retire?

This friend is single and in her 60s. She works part-time and has some savings and investments but feels uncertain about the future. How does anyone plan for the coming years, she wondered, when end-of-life costs are impossible to guess? How do we know how much we’ll be spending, or even where we’ll be living?

This situation is one of the most common reasons people hire us as financial advisors; we can analyze your exact circumstances and model how different choices will impact your finances over time.

But for inquiring minds at the coffee shop, here’s how you can ballpark your readiness.

Retirement Readiness Quick(ish) Calculation:

Give it a try below. Keep reading on for the full breakdown of each step.

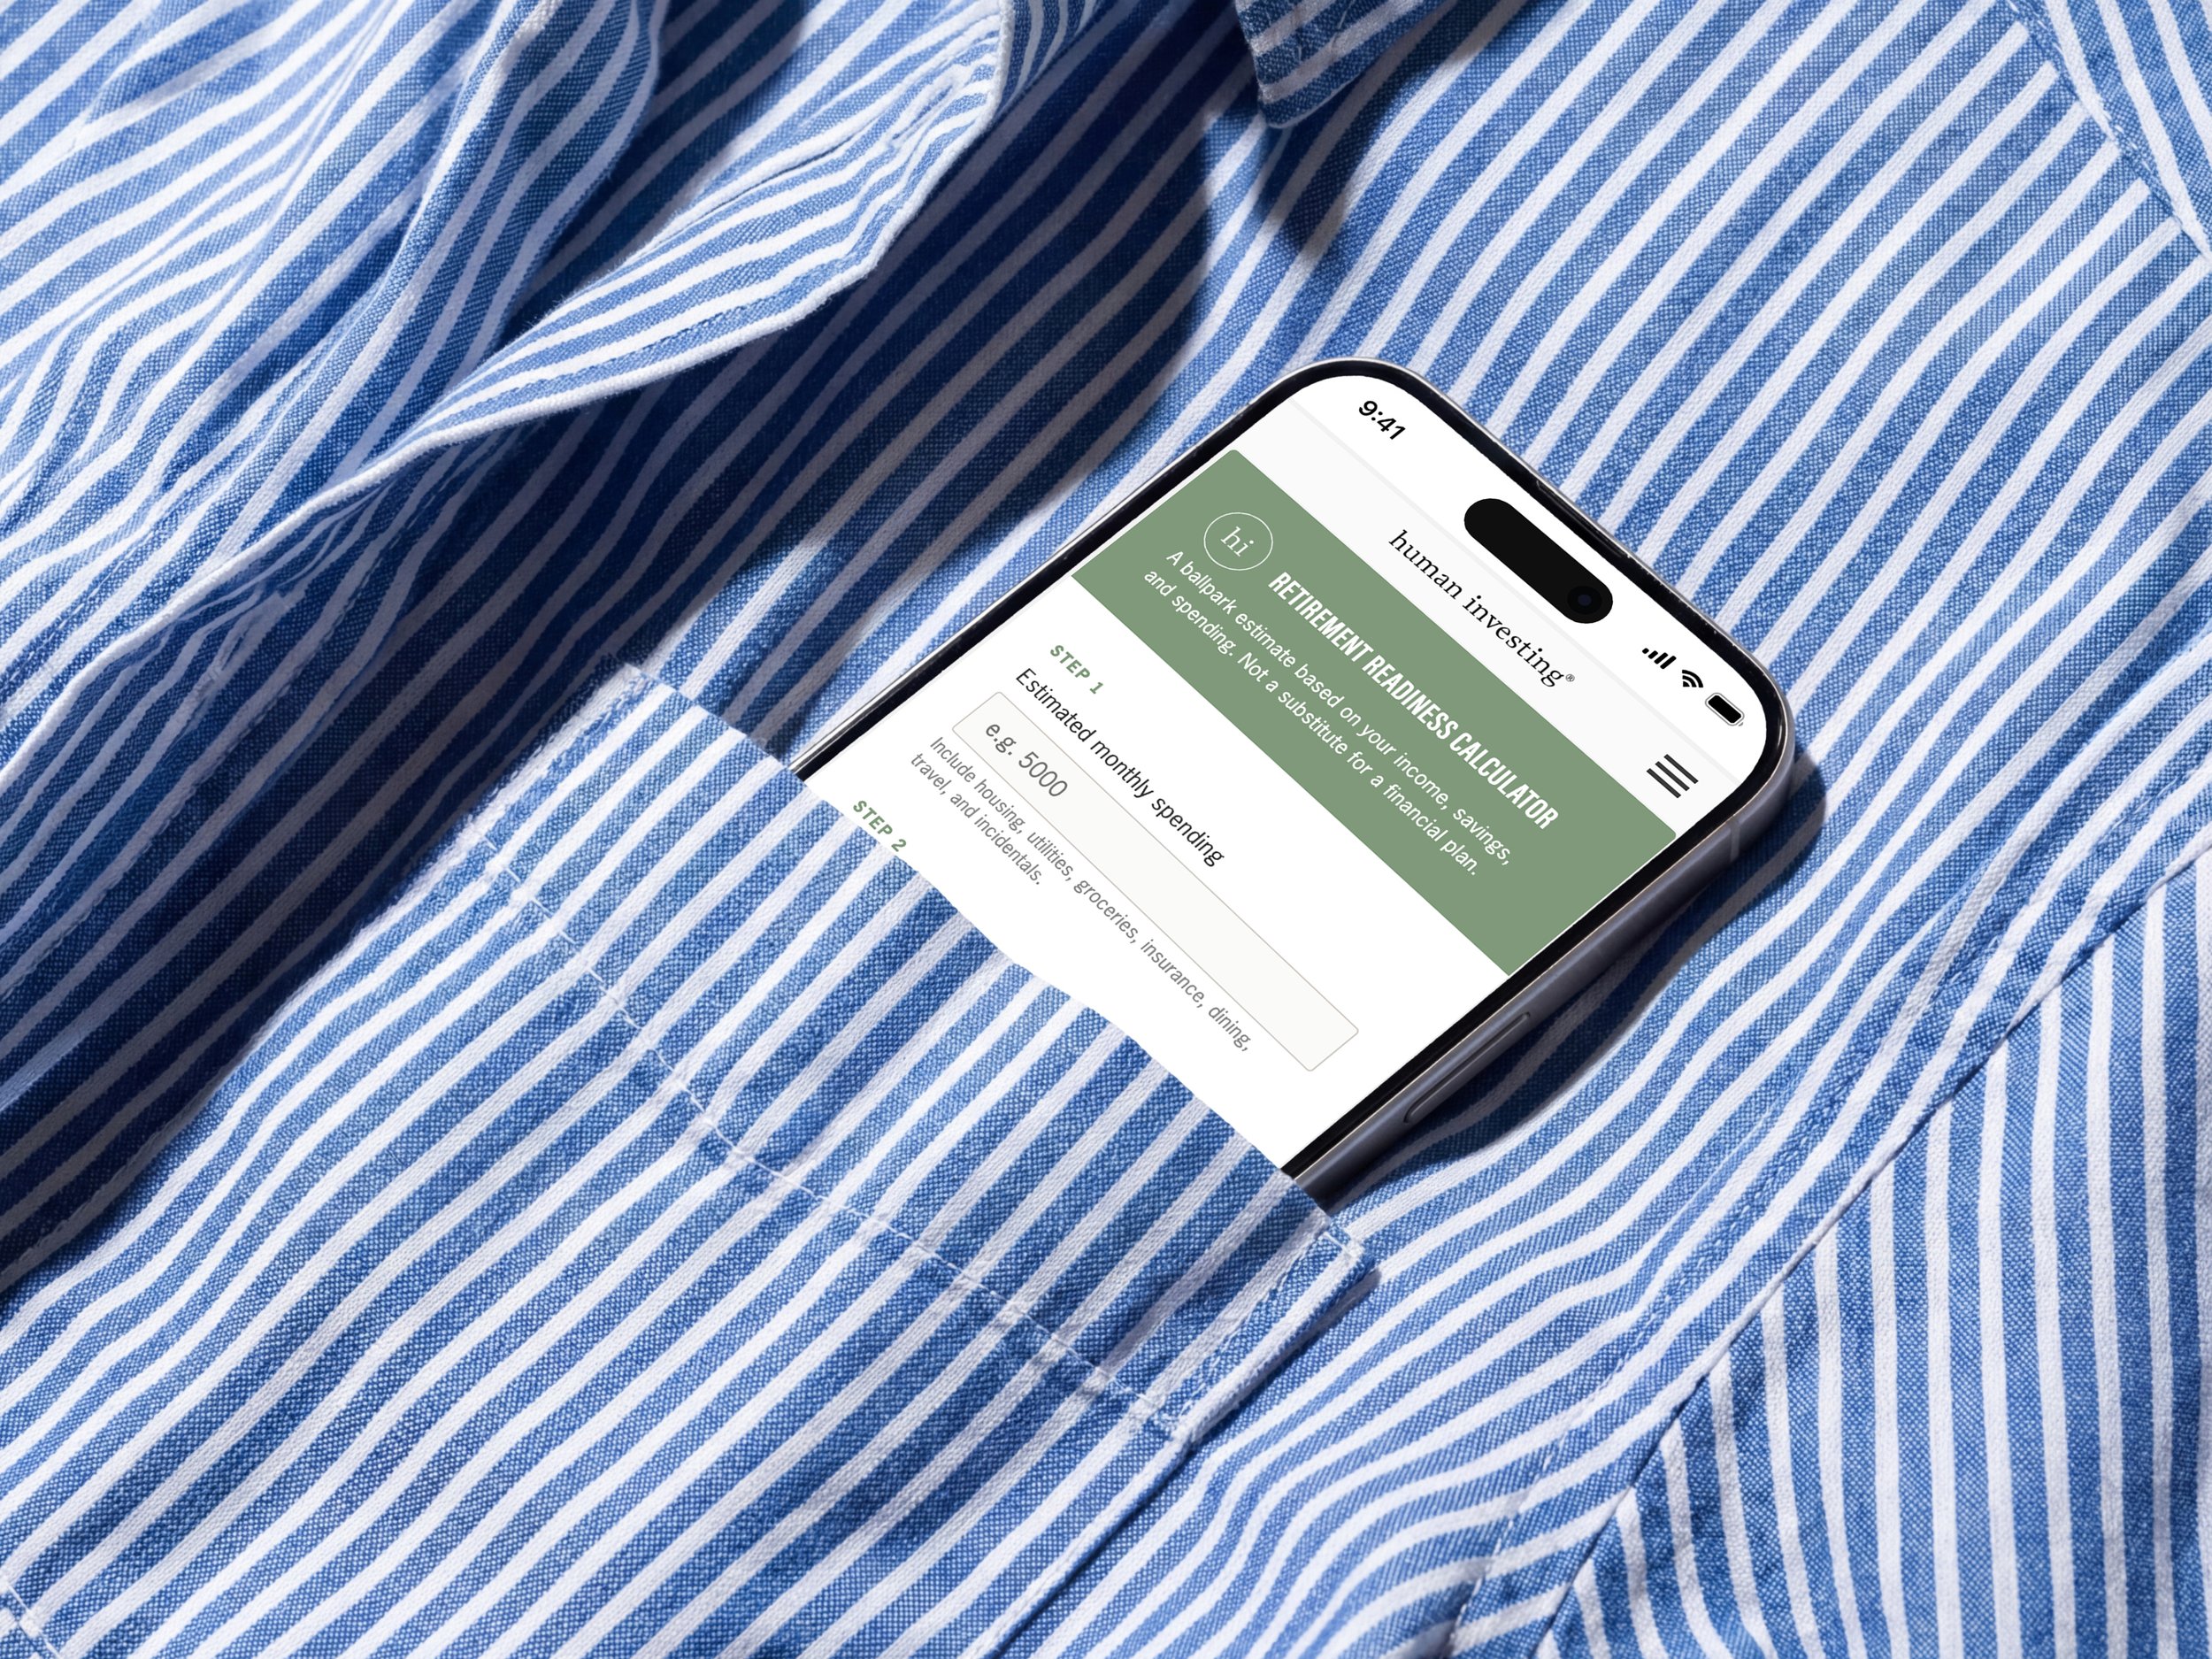
Retirement Readiness Calculator
Human Investing

Retirement Readiness Calculator

A ballpark estimate based on your income, savings, and spending. Not a substitute for a financial plan.

Step 1
Include housing, utilities, groceries, insurance, dining, travel, and incidentals.
Step 2
Find your estimated benefit at ssa.gov. Enter 0 if not applicable.
Step 3
Pension, annuity, rental income, or part-time work. Use gross income before taxes.
Step 4
Every dollar in IRAs, 401(k)s, 403(b)s, brokerage accounts. Exclude your emergency fund.

Investment income (4% rule / 12) —
Social Security —
Other income —
Total monthly income —
Estimated monthly spending —
Monthly surplus / shortfall —

This calculator uses a 4% annual withdrawal rate as a starting estimate. Your actual withdrawal rate may differ based on your timeline, tax situation, and plan. This is not financial advice.

  1. Estimate your current monthly spending. Include fixed expenses like your rent/mortgage, utilities, insurance, and groceries, as well as incidentals like shopping, restaurants, and vacations. If you know your mortgage will be paid off or you anticipate specific changes, like increased healthcare or vacation spending, you should adjust your estimate.

  2. Determine your Social Security benefit. Go to ssa.gov and look up your monthly benefit amount in the year you plan to retire or, if you know it, the year you will begin taking your benefit. (These years don’t need to be the same.) While there’s no universal best age to start taking your benefit, doing so later will translate into a larger monthly check.

  3. Add other reliable income to determine your total monthly inflow. Think pension, annuity, rental income, or a part-time job. (Use your gross income before taxes or deductions.)

  4. Add investment income:
    a. First, tally up your total invested assets. That means every dollar in an IRA, 401(k), 403(b), IAP, brokerage, or other investment or retirement account. Don’t include your emergency fund.
    b. Then, calculate your monthly withdrawals. Assume a withdrawal rate of 4%, a common starting place. Multiply your total invested assets by .04, then divide by 12. Example with $500,000 invested: $500,000 x 0.04 = $20,000. $20,000 / 12 = $1,666.67 monthly income from investments.

  5. Determine your total income. Add together your Social Security benefit, other income, and investment income.

  6. Calculate your potential shortfall. Subtract your total monthly spending from your total income. This amount is the shortfall you’ll need to cover your estimated expenses in retirement, hopefully with investment account withdrawals. Example: With a monthly spend of $5,000, a $1,200 monthly pension, and a Social Security benefit of $3,000, your total income is $4,200. Your shortfall is therefore $800, or $5,000 minus $4,200.

Nailing Down the Details

Ultimately, your retirement plan must consider what happens during a prolonged market decline, when to claim Social Security, healthcare costs, taxes, and many other factors.

The calculation above is a first step that can tell you whether retirement appears to be within reach and, perhaps more importantly, which questions deserve a closer look before you make the decision, such as:

  • Will my mortgage be paid off before I retire?

  • When should I take Social Security?

  • What are my priorities for spending, saving, and gifting?

A financial advisor can hone your retirement spending projection, factor in major expenses like a home upgrade after retirement, and account for family medical history. We also help people understand what an appropriate withdrawal rate might be. (We’ve used 4% in the calculation above, but this percentage is only a general rule.)

Critically, an advisor can guide you through the foundational decision of when to take Social Security if you’re eligible. This decision impacts nearly every aspect of retirement planning.

What if I Don’t Have Enough?

Any amount you can save for retirement is helpful. Clients who reach their 80s with $40,000 saved have a cushion that can protect against unexpected expenses, and people with $100,000 may be able to pay for a year or more of assisted living. Mindset matters, too. People who throw up their hands in mid-life and don’t save for retirement because they run into a challenging health problem or unexpected layoff tend to be worse off than those who can recognize bad times are often temporary, and pick up saving what they can, when they can.

We work with a wide range of clients, from those who retire early to those who start thinking about retirement much later in life. Our commitment to meaningfully help people at all asset levels is one of the reasons that I work at Human Investing. Regardless of your financial circumstances, the same advice applies: Stay flexible in your mindset about money. Do what you can, forgive yourself for past missteps, and seize new opportunities as they arise.


Disclosure: Human Investing is an SEC-registered investment adviser. Registration does not imply a certain level of skill or training. This content is for informational and educational purposes only and does not constitute personalized investment advice or a recommendation. Past performance is not indicative of future results. All investments carry risk, including potential loss of principal. Readers should consult with a qualified professional regarding their specific financial situation.
 

Related Articles

Closing The Gap For The Retirement Haves And Have-Nots
 

This article was originally published on Forbes.

Shutterstock

Shutterstock

The Employee Retirement Income Security Act (ERISA) was established in 1974 to give employees retirement income security. Why, then, after 40-plus years, are Americans so underprepared for retirement?

According to a 2015 study from the Government Accountability Office, "About half of households age 55 and older have no retirement savings (such as in a 401(k) plan or an IRA)." Even those who have saved have saved poorly. Among those households of residents ages 55 to 64 with some retirement savings, the median amount saved is $104,000. For those 65 to 74, the amount is roughly $148,000 per household. And, with 70% of the civilian population having access to a retirement plan and 91% access for government employees, it’s a wonder there is such a lack of retirement readiness.

There is no shortage of financial and intellectual capital being spent on a solution for retirement readiness. But most solutions have fallen short of narrowing the gap between the retirement haves and have-nots. So, what is the solution? My thoughts follow:

Government Plus Employer Plus Employee

First, the government is already involved in the regulation of retirement plans, as well as allowing for employers to deduct the expenses of having a plan, so why not go all in? Why not tell employers, “If you are going to get the deduction, you need to meet certain requirements that are great for employees, great for your business and great for our country”?

Those requirements could include auto-enrollment (as this has been a home-run for participation), auto-increase (as individuals get raises, they add a little more to their retirement) and an eligible age-based default option (eligibility for a great default option would be low-cost and diversified as you get from the likes of popular mutual fund providers with their index retirement glide path funds).

In order to qualify for a business deduction or incentive from the government, an employer would be required to match a certain amount. I’d propose 5%, with the employee required to commit 5% to get that amount. Why these amounts? Because if someone has a job for 40 years and invests in a basket of mutual funds growing at or around 8%, with both the employee and employer contributing at 5% each, they end up a millionaire (assuming a $36,000 annual salary, or $300 per month contributions, compounded monthly for 40 years.)

The Industry

In a recent Society for Human Resource Management (SHRM) study, more than 70% of HR professionals surveyed emphasized the importance a retirement savings plan. So, at a minimum, employees are aware of the need to save and desire to do so. While there is definitely a need amongst employees to save for retirement, there are several barriers that impact participants interest and willingness to save. First, trust among advisors is low. Second, many plans have a dizzying array of options, which negatively impacts deferral rates. Finally, not all employers offer to match contributions, which minimizes the incentive for employees to contribute to the 401(k) versus less automated choices, like an IRA.

So, what can the industry do to partner with employers and their workforce? There are two things in my view:

1. Understand the heart of ERISA. Advisors and their firms are to put the interests of the employee and their income security at the center of everything they are doing. If, somehow, the advice we are giving in any way conflicts with the employee and their security, then we should reassess what we are doing and meet the stated purpose of ERISA -- it doesn’t need to be any more complex.

2. In order to minimize the potential for anything but the fiduciary standard, any firm operating in the retirement space should be required to be a fiduciary and have no ability to be dually registered or receive commissions, kickbacks, trips or any other super-secret benefit.

Join the small percentage of firms that are truly fee-only and have no way of receiving any form of compensation other than from the client. Disclosing away conflicts is not the answer for the clients, as few read the disclosures they are provided. If we are going to serve clients well, eliminating the ability for the conflict to exist is the only reasonable route to go.

In conclusion, the government is already involved in both rule-making and incentives for companies and their employees to offer and invest in retirement plans. A model for offering a retirement plan that meets certain criteria in order to fully receive the incentive should be outlined and adhered to by companies and their employees. In partnership with the government, employers and employees, the financial services community should be held to a higher standard to eliminate the conflicts that keep retirement plans for becoming all they could be, which is for employee retirement income security.


Related Articles