Posts in Retirement Strategy
The Importance of Portfolio Rebalancing and Market Timing
 
loic-leray-fCzSfVIQlVY-unsplash.jpg

What a season it has been.  I hope and pray that each individual and family member receiving this note is healthy and safe.  My goal over the coming months is to increase the volume of written communication.  These notes will not replace our regular scheduled tax, planning, or portfolio updates.  Instead, they will supplement those conversations and provide a financial perspective that can be communicated efficiently in writing.  The purpose of this note is to discuss our position on market timing and portfolio rebalancing.

Portfolio Rebalancing

We believe that the financial plan is the seminal document for investors seeking to accomplish long term goals. Each financial plan is prescriptive in the amount of saving and portfolio return that is required to accomplish the goals outlined in the plan.  The asset allocation decision is an important one—given it considers risk tolerance, time horizon, and financial goals[1].

The goal of rebalancing is to minimize risk and recalibrate, rather than to maximize return.  The process of rebalancing takes the imbalance that is created by certain asset classes over time and recalibrates those asset classes.  It takes the asset allocation that was originally prescribed by the financial plan and reorients the portfolio to its intended mix of stocks, bonds, and cash.

For most portfolios, recalibration should occur a few times a year.  This is particularly true in retirement accounts, given there is no tax liability for creating gains.  In trust accounts as well as individual and joint accounts, there is a sensitivity to tax gains as a possible consequence of rebalancing.  Every effort is taken to minimize tax liability in those types of accounts.  However, it can be hazardous to let the concern over taxes negate the discipline of regularly rebalancing.  I can think of too many instances where a client avoided rebalancing their account out of concerns for taxes—only to have the market go down. The tax liability for rebalancing was ultimately dwarfed by the loss of principle due to the market decline.  In short, it is rarely advisable to let the tax tail wag the investment dog.

Market Timing

The most common question I receive is, “when should we sell out?”  My typical response is never.  If an investor has a financial plan, which accounts for planning-based return expectations and subsequent asset allocation, the portfolio should always be properly positioned for risk and return.  If the goal of “selling out” is to reduce risk, the action of selling implies the original allocation was incorrect. 

In the past, there have been a few occasions where dramatically reducing risk by selling equities and raising cash makes sense.  Or, to sell a portion of the stock investment and place the proceeds in bonds.  But those reasons have to do with new information about the client situation, which prompt a change in the asset allocation. As an example, years ago, we had a client let us know that their business was struggling, resulting in the potential that their retirement account would need to be tapped for an emergency.  Liquidating equities in their account was a response to a change of plans and circumstances—this is a plan modification and not market timing. 

There is ample research dating back to the 1980s which suggests timing the market[2] or being able to predict the direction of the market is challenging at best[3].  Therefore, we believe in rebalancing “to recapture the portfolio’s original risk-and-return characteristics”[4], and we rely on the financial plan as the authoritative document to prescribe the proper mix of stocks and bonds for each client we serve.


Sources

[1] Zilbering, Y., Jaconetti, C. M., & Kinniry Jr, F. M. (2015). Best practices for portfolio rebalancing. Valley Forge, Pa.: The Vanguard Group. Vanguard Research PO Box, 2600, 19482-2600.

[2] Brinson, G. P., Hood, L. R., & Beebower, G. L. (1986). Determinants of portfolio performance. Financial Analysts Journal, 42(4), 39-44.

[3] Butler, A. W., Grullon, G., & Weston, J. P. (2005). Can managers forecast aggregate market returns?. The Journal of Finance, 60(2), 963-986. 

[4] Zilbering, Y., Jaconetti, C. M., & Kinniry Jr, F. M. (2015). Best practices for portfolio rebalancing. Valley Forge, Pa.: The Vanguard Group. Vanguard Research PO Box, 2600, 19482-2600.


Related Articles

Providing Sound Advice in a World of Robinhood Investing
 

One of the interesting subplots in the finance industry during COVID-19 has been the rise of the day trader. Robinhood, an online brokerage and trading platform, acts as a proxy for many investors who are rapidly opening accounts at other brokerage firms including Charles Schwab, E*T, TD Ameritrade, Fidelity, etc.

Our firm works with thousands of employees via their company-sponsored retirement plans and has had many conversations end with a question/comment along the lines of, “What do you think of this Robinhood thing? Is it worth putting some money in there? Seems like (fill in the blank tech company) is making money! Should I buy some?”. So, I felt compelled to address the question(s) and provide some context around where a speculative trading account fits into a greater financial plan.

THE MAJOR PLAYERS

Source: Piper Sandler

Source: Piper Sandler

E*TRADE: more users opened accounts in the month of March than any full year on record.

Charles Schwab: 1 million new accounts so far in 2020.

Robinhood: 3 million users opened accounts in Q1 2020. For perspective, there have been 13 million accounts opened at Robinhood since its founding in 2013.

The GROWING appeal OF DAY TRADING

The barrier of entry has never been lower to open an account and buy shares of publicly traded companies. Because many individuals are at home, trading is as cheap and accessible as ever, and some firms have incentive offerings (like a free share of stock when you open an account). Pair that with the stock market reaching its low point for the year on March 23rd and having one of its fastest recoveries ever (in other words the last 5 months have been a winning proposition for many investors), and you get to the point where we are today.

YCharts1.png

Today could be a euphoric place for an investor owning stocks since March. To me, euphoria looked like TMZ coming out with a trading subscription service… yikes. Stocks have only gone up, and popular tech companies have led the way. Kudos to those who might have doubled their money on a company like TESLA, but the last 5 months do not paint a realistic picture of what investing looks like over the long haul.

the emotional rollercoaster of Owning single stocks

When talking about owning a single company, I like this example. Owning a company like Amazon over the last 10 years seems like a no brainer (today). If you had invested $10,000 10 years ago, it is worth over $268,000 today. However, when you see that over the last 10 years, an investor would have had to hold through down periods of -25% over 5 times to get to where the stock is today. In other words, the stock was down 25% of its high over 5 times. Holding a company through those periods can be difficult, emotional, and in my opinion, is an objective way of capturing what owning a stock (even one that has performed as well as Amazon) is like.

AMZN_chart (2).png
AMZN_chart (3).png

Investing advice for smarter day trading

Whether you are someone who has already played around, are thinking of dipping your toe in the water, or your ego is already as big as ever because you’ve been a successful trader for the last 5 months, here is some advice on what it looks like to invest in your long-term plan vs. speculating.

Boundaries, Boundaries, Boundaries: If you are going to buy a stock on your own, don’t have it impact your overall investment strategy and long-term plans. What does that mean? Invest a dollar amount that you would feel comfortable taking a 100% loss on.

A positive outcome can mean… many things: Recently the Winklevoss twins (yes those Winklevoss twins) were quoted saying that Elon Musk is going to mine gold on asteroids orbiting the Earth, thus decreasing the value of gold and increasing the value of bitcoin (I promise this isn’t fake). One scenario is that their theory is wrong but in the next 5 years, owning bitcoin could be a profitable trade. In the same light, if you have owned a technology company or a fund that tracks technology companies since March, you have probably made money. Does this make you the next great market predictor? Most likely not. At Human Investing, we have a saying "process over results". So, in these situations, whether or not your account is checking up on your process is equally or more important.

Trading Journal: If you are seriously interested in the market and having a brokerage account, a trading journal is imperative. If you have a prediction, write it down, track it, and review your track record. It’s not a bad idea to do this for a few weeks to test the waters before you open an account.

Small Losses Can Lead to Long-Term Positive Outcomes: Here’s a hypothetical, stay with me. You read this post, you open an E*TRADE account, and deposit $200. You end up buying a few stocks and start following the market. You are following investing influencers on social media, listening to podcasts, and even watching CNBC in the morning. Then life happens. You get a little bored, lose track of your password, reset your password, and lose track again (this version of you doesn’t have LastPass 😊). Six months go by, and you see that your $200 is now $50. As a byproduct of this experience, you realize that you are better off opening up a ROTH IRA at Vanguard contributing $100 a month into an age-based target-date fund because you now care more about retiring comfortably. Your $150 loss on your account made you realize:
  1. You are not interested in picking stocks and it isn’t easy.

  2. You educated yourself about the market, the benefits of a ROTH IRA, and moved the needle on helping yourself retire.

Time will tell if this Robinhood movement is a fad or a long-term trend. Either way, if you have questions, want to grab coffee via zoom and talk markets, or talk longer-term planning, our team is here to be a resource.

Other Articles You Might Enjoy On This Subject

* Inside Story On Robinhood

* WSJ video on Robinhood


Related Articles

Equity Returns Are in Your Favor: The Positives Outweigh the Negatives
 
michal-parzuchowski-GikVY_KS9vQ-unsplash (1).jpg

“Stocks are too risky for me.”

“You shouldn’t invest anything in stocks unless you’re prepared to lose all of it.”

“Investing is just another form of gambling.”

I have heard these concerns and many other reasons why people are nervous about investing, particularly in stocks. The ups and downs of the stock market can be difficult to stomach. This year, we saw one of the fastest drops in history as COVID-19 hit the world. The S&P 500 was down just over 30% from the beginning of 2020. Then stocks rallied back. At the end of July, the S&P 500 was positive for the year 2020. This is a wild ride no matter how you look at it.

The fear of short-term losses in investing is referred to as “myopic loss aversion”. The idea is that the fear of short-term losses scares investors away from riskier assets like stocks. As such, investors tend to invest more conservatively than they should, resulting in lower long-term returns.

Long-term stocks are a wonderful tool to grow your assets above the rate of inflation. Growing your savings and spending power over time is attractive, and for many it is essential to achieve their financial goals. The volatility of stocks along the way? No one looks forward to that. 

How risky are stocks in any given year?

If we look at historical returns for the S&P 500, a curious picture emerges:

s&p 500.jpg

Since 1937, the S&P 500 has had a positive return in 63/83 years, or 76% of the time. For reference, that is a solid “C” and a passing grade in any class I have taken.

For example, pretend you put $100 in the stock market on January 1 every year. In years with a positive return (76% of the time), on average you would see that $100 grow by 19.61% to $119.61. In years with a negative return (24% of the time), you would see that $100 shrink by an average of -12.19% to $87.81. Long-term, the odds are in your favor to grow your assets.

Invest with a Stable Foundation

There are certainly risks to owning stocks. It is important to ensure you have an emergency fund  to cover unexpected job loss or life expenses. It is also important to determine how much risk you can handle, both financially & emotionally, so you are not tempted to panic and sell when you see your account balance go down. A financial plan may be helpful to illustrate the dangers of investing too conservatively or too aggressively and may help to determine the risk that makes best sense for you.

If you need help understanding the risks and benefits of investing in equities, please contact our team at Human Investing. 


Related Articles

$5 Today is Worth More than $5 Tomorrow
 

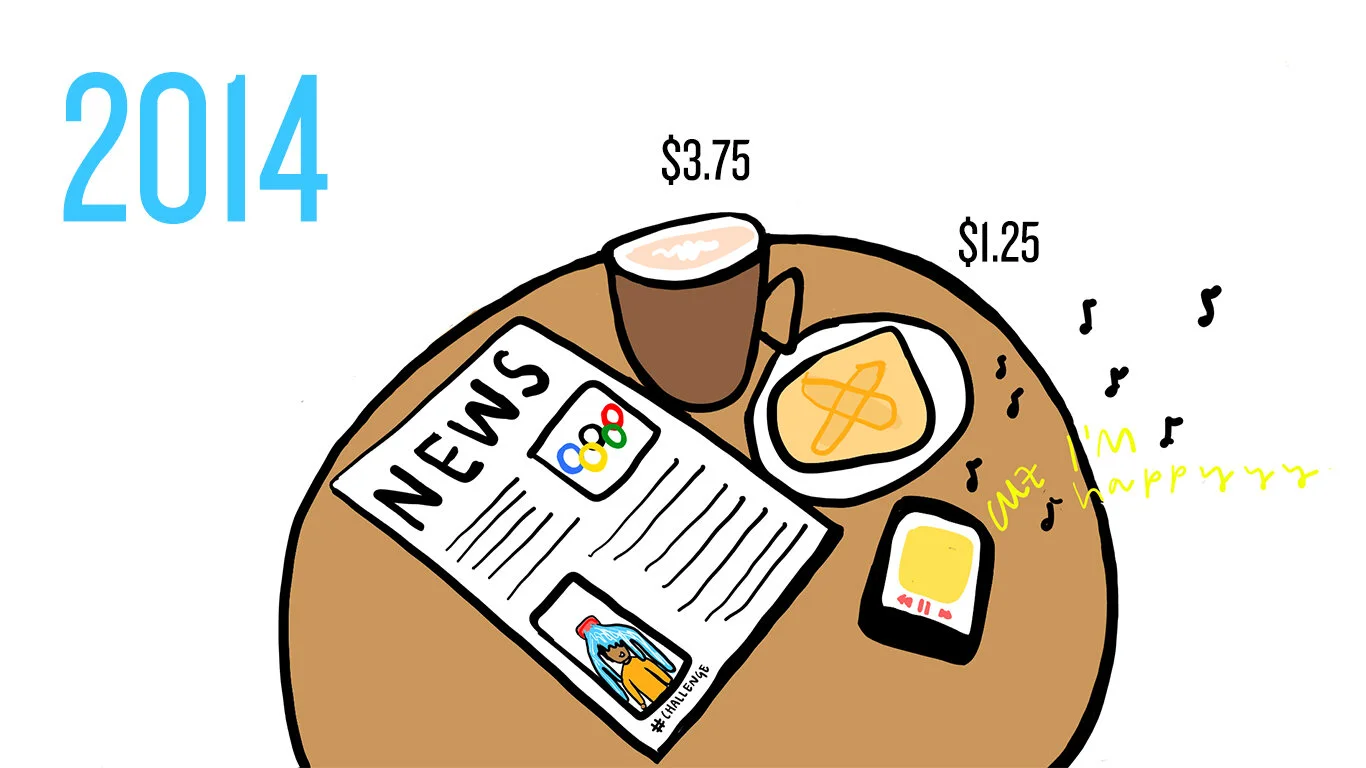
Saving your hard-earned dollars is a better game plan than frivolously spending money. However, keeping your savings in cash (not investing the dollars) is also risky. This risk is called inflation. To substantiate inflation, we found the increase in price of Stumptown Coffee Roasters lattes since 2014.  

**This article is not about Stumptown increasing the costs of their lattes. Suppliers, just like buyers, pay more for the goods they buy when inflation is rising. Stumptown consistently ranks among the best coffee shops in Portland!**

Flashback! It’s 2014…

You have $5.00 to go spend at Stumptown Roasters. That will buy you a delicious medium latte for $3.75 and a shortbread cookie for $1.25. Treat yourself!

2014.jpg

Let’s say, instead of spending that $5.00 in 2014, you put it under your mattress for safe keeping. You find the $5.00 a few years later and still frequent Stumptown. We are going to run through a few scenarios of the purchasing power of that same $5.00 bill.

Two years have passed, and it is now 2016.

Your beloved medium latte now costs $4.00, and the shortbread cookie costs $1.35. You find $.35 in your pocket (does finding coins ever happen anymore?!), so you make the purchase possible.

2016.jpg

Four years have passed, and it is now 2018.

That same tasty medium latte now costs $4.50, and the shortbread cookie costs $1.50. You might be going home hungry.

2018.jpg

Fast forward six years to 2020…

Your medium latte now costs $4.75, and the shortbread cookie costs $1.60. Assuming you would leave the barista a tip, your $5.00 bill cannot even buy you a coffee. You might be going home thirsty and hungry.

2020.jpg

Magnifying inflation’s effects on bigger life decisions

In this example, the cost of a coffee and a cookie only changed by $1.33 over six years. While that may not seem significant (the increase is less than $2!), the cost of goods did increase by 26%. If you apply that percent increase to a larger purchase like a home, a car, or education savings, you may not be able to afford what you intended.

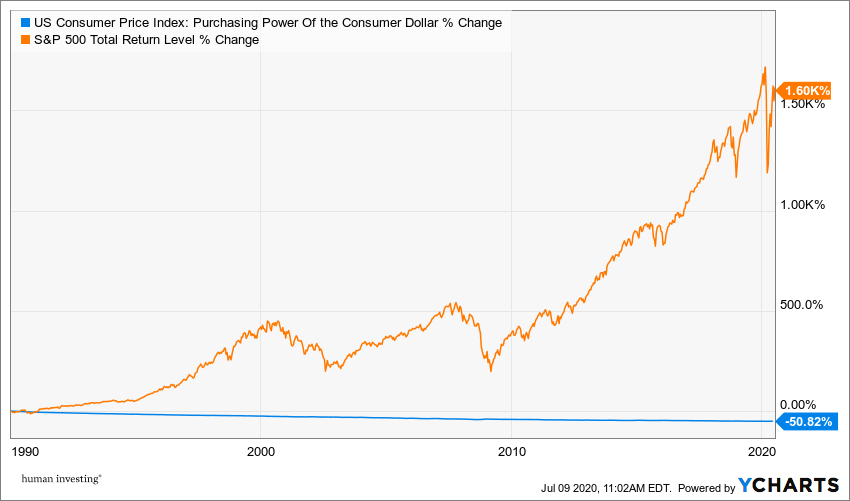
One way to maintain purchasing power is to invest the $5.00 into the stock market. If you bought the S&P 500 in 2014, then that same $5.00 would be worth around $9.40 today in 2020, which is enough to pay for a coffee and cookie from Stumptown. For simplicity purposes, we only looked at the rising cost of coffee and S&P 500 return since 2014. To further substantiate the decrease of purchasing power over time, we included a chart that compares the S&P 500 total return to the purchasing power of a dollar since 1990. 

Coffee Chart.png

If you have questions or need help preparing an investment strategy for your savings, please contact our team at Human Investing. We drink good coffee.  


Related Articles

Test Your Financial Literacy With These 5 Core Questions
 

The financial world can be a confusing place filled with jargon, technicalities, and little to no guarantees. Research suggests that those who are financially literate tend to have better financial outcomes. Financially literacy is typically measured by asking some core financial concept questions. Let’s walk through some financial literacy questions from the National Financial Capability Study, and explain the why behind the answer. Feel free to guess and score yourself at the end:


Question 1 - interest:

Suppose you had $100 in a savings account and the interest rate was 2% per year. After 5 years, how much do you think you would have in the account if you left the money to grow?

A. Less than $102
B. Exactly $102
C. More than $102


Answer: C, more than $102.

Explanation: The key part here is “After 5 years”. We are told the interest rate is 2% per year. That means every year, 2% gets added to our principal balance. To break it down year by year:


q1 copy.jpg

The interest earned increases each year. This is due to compound interest: the original principal ($100) grows, and the interest you earned previously (in year 2, $2) both earn interest. At the end of 5 years, we have $110.41 which is C More than $102.

Why this matters: Interest affects you when you save money to grow it, or borrow money to pay it back later. Knowing how interest can work for or against you is critical for financial success.

Question 2 - inflation:

Imagine the interest rate on your savings account was 1% per year and inflation was 2% per year. After 1 year, how much would you be able to buy with the money in this account?

A. Less than today
B. Exactly the same
C. More than today


Answer: A, Less Than today.

Explanation: They key here is the inflation rate is higher than the savings rate. Inflation is growing at 2%, meaning the price of goods (rent, utilities, food, cars, etc.) is going up by 2% each year. The cost of $100 of goods today will be $102 in 1 year. Your interest on savings is growing at 1% a year. That means in 1 year you will have $101 to spend on goods. In 1 year, you will have $101 to buy $102 worth of goods. Your ability to buy is A less than today.

Why this matters: Even if you keep your money “safe” in the bank or under the mattress, inflation is going to make that money less and less valuable. Thus why investing is so important. Investing can be scary due to downturns in the market, but ultimately the odds are in your favor to grow your money over time. Unless you can save significant portions of your income, growing your savings faster than inflation is critical for being able to retire.

q2 copy.jpg

Question 3 - Risk Diversification:

Buying a single company’s stock usually provides a safer return than a stock mutual fund.

A. True
B. False


Answer: B, False.

Explanation: To answer this question correctly, it is important to understand both risk and that a mutual fund owns a variety of companies. They keyword here is safer. Financial markets have two types of risk: market risk and company-specific risk (aka systematic risk and nonsystematic risk respectively).

Market risk refers to risk all companies face. Examples of market risk include a change to the US tax code, a global pandemic, or shifts in consumer tastes like a shift from fast food to organic freshly prepared food. You will always face market risk because every company is exposed to these risks. Company-specific risk refers to risks unique to one company. Examples of company-specific risk include sudden changes in management, a press release about product defects, mass recalls, or a superior/cheaper product released by a rival company. Because you own a variety of companies in a stock mutual fund, you diversify away (i.e. reduce your risk) if any single, specific company has a terrible event.

Why this matters: Don’t invest all your money in one company. Especially if you work for that company, and your compensation is based on the company doing well. By spreading out your investments, you reduce your risk of catastrophic returns, and smooth out the ride so you can sleep at night.

Question 4 - interest of the life of a loan:

A 15-year mortgage typically requires higher monthly payments than a 30-year mortgage, but the interest paid over the life of the loan will be less

A. True
B. False


Answer: A, True.

Explanation: Because of the shorter life of the mortgage loan, you pay less interest. Remember in question 1, interest compounds every year. When you borrow money, that compounding works against you. Therefore, the faster you are paying off debt, the less time for interest to compound and grow the total amount you have to payoff. The monthly payments are typically larger, but the overall interest paid is less.

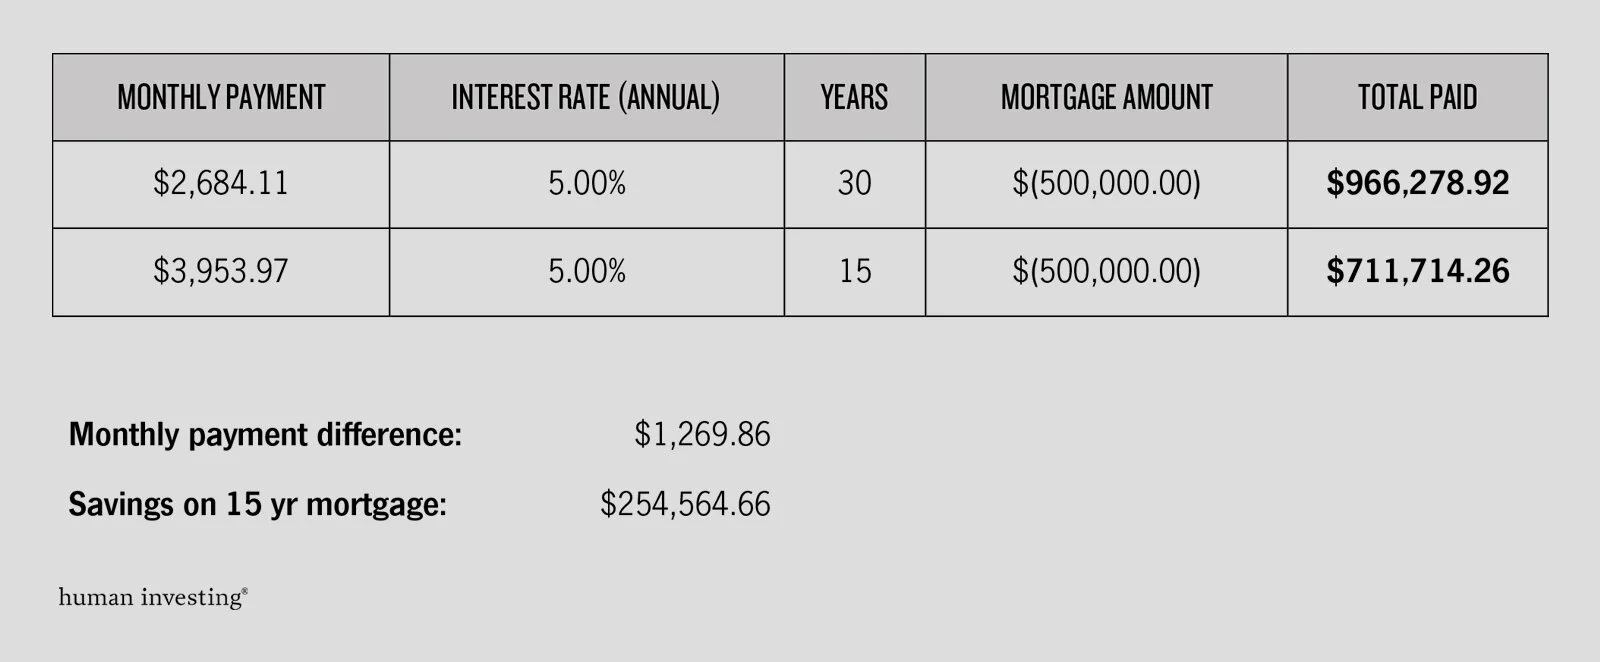
To illustrate with numbers, let’s look at the difference between a 15 year & 30 year mortgage, assuming a 5% interest rate for both:

q3 copy.jpg

Why this matters: You can see from the example how much money is saved by opting for a 15 year mortgage. Can you afford that extra monthly payment? That’s worth investigating, but you’ll never explore your choices if you don’t know what they are. You can also usually get a lower interest rate for shorter term debts, which saves you even more money. Anytime you borrow any amount of money, the faster you can pay it off, the less you will pay total. Even if you don’t get a lower rate on the debt, if you pay off the principal sooner, that means there’s less interest compounding against you. When looking to borrow money, evaluate what term (length of time) works best for you and your budget. You want to minimize your cost of borrowing, but you also want to give yourself enough flexibility that you’re confident you will make all those payments on time, regardless of what life brings.

Question 5 - Bond prices and interest:

If interest rates rise, what will typically happen to bond prices?

A. They will fall
B. They will stay the same
C. They will rise


Answer: A, they will fall.

Explanation: This is the question most people get wrong. A bond is government or corporate debt. The government or company pays you coupons (interest payments) based on the issued interest rate. At the end of the bond’s life, it matures, and you get the principal back.

Imagine Disney issues bonds paying 5% interest, the current market rate. You purchase a bond for $1,000, and you get a $50 coupon payment from Mickey Mouse every year until the bond matures. If interest rates rise next year (say to 8%), and Disney issues new bonds, they will issue them at the new interest rate. Your neighbor Laura decides to buy $1,000, and she gets an $80 coupon from Mickey Mouse every year. Because interest rates rose, the value of your bond paying $50/month goes down in value, less than $1,000, because the $1,000 could buy Laura’s bond paying $80/month. The reverse if also true. If rates had fallen to 3%, Laura’s bond would only pay her $30, and your $50/month bond would be worth more than $1,000.

Why this matters: Interest rates change over time. This causes bond prices to change. Bonds will still be less volatile than equities, but they do also fluctuate in value. Don’t panic when you see interest rates rise, and your bond prices going down in value. This is both normal and expected. Rising interest rates are also usually a healthy sign for the economy, and so your equities will generally be rising in value to help offset the loss in value of your bonds. The reverse is also true here. Falling interest rates tend to indicate a less healthy economy (think about when rates have dropped significantly & quickly; the 07-08 financial crisis and COVID-19) which means falling stock prices. Because they don’t tend to move together (uncorrelated), bonds and stocks are an excellent pair for smoothing out your investment returns.

How did you do?

If you got some questions wrong, I hope you understand the why behind the answers and how to utilize this knowledge to better your financial life. If you have questions about financial vocabulary or systems you’d like me to blog about, please email me at andrewg@humaninvesting.com. If want to talk to an advisor, please email us at hi@humaninvesting.com.


Related Articles